Project what today's money will buy in future, and the return you need to keep up.
| Year | Buying power | Price of basket | Saved, real |
|---|
Inflation and savings rates are your own assumptions, not forecasts. Real figures are shown in today's money.
Money sitting still is quietly shrinking. This inflation purchasing power calculator looks forward rather than back: tell it an amount, a number of years and the inflation rate you expect, and it shows what that money will really buy. If you want to look backwards with actual price data instead, our UK inflation calculator uses historic ONS figures from 1988 onwards, while this tool helps you plan ahead.
Quick answer: An inflation purchasing power calculator uses real value = amount ÷ (1 + i)^years. At 3% inflation, £10,000 kept for ten years will only buy what £7,441 buys today, while a £10,000 kitchen will cost about £13,439, so savings taxed at 20% need at least 3.75% before tax to keep pace.
In This Guide
What Is Purchasing Power?
Purchasing power is the amount of real stuff a sum of money can pay for. When prices rise each year, every pound covers a little less, even though the number in your account has not moved. The tool uses two linked formulas: future price = amount × (1 + i)^years and real value = amount ÷ (1 + i)^years, where i is the yearly inflation rate.
Say Tom puts £10,000 aside for a kitchen he plans to fit in ten years. At 3% inflation, the same kitchen will cost about £13,439 by then, and his untouched £10,000 will only buy what £7,441 buys today. If his account pays 4% and he pays 20% tax on the interest, he earns 3.2% after tax, which just edges ahead of inflation. To break even he needs at least 3.75% before tax.
How to Use the Inflation Purchasing Power Calculator
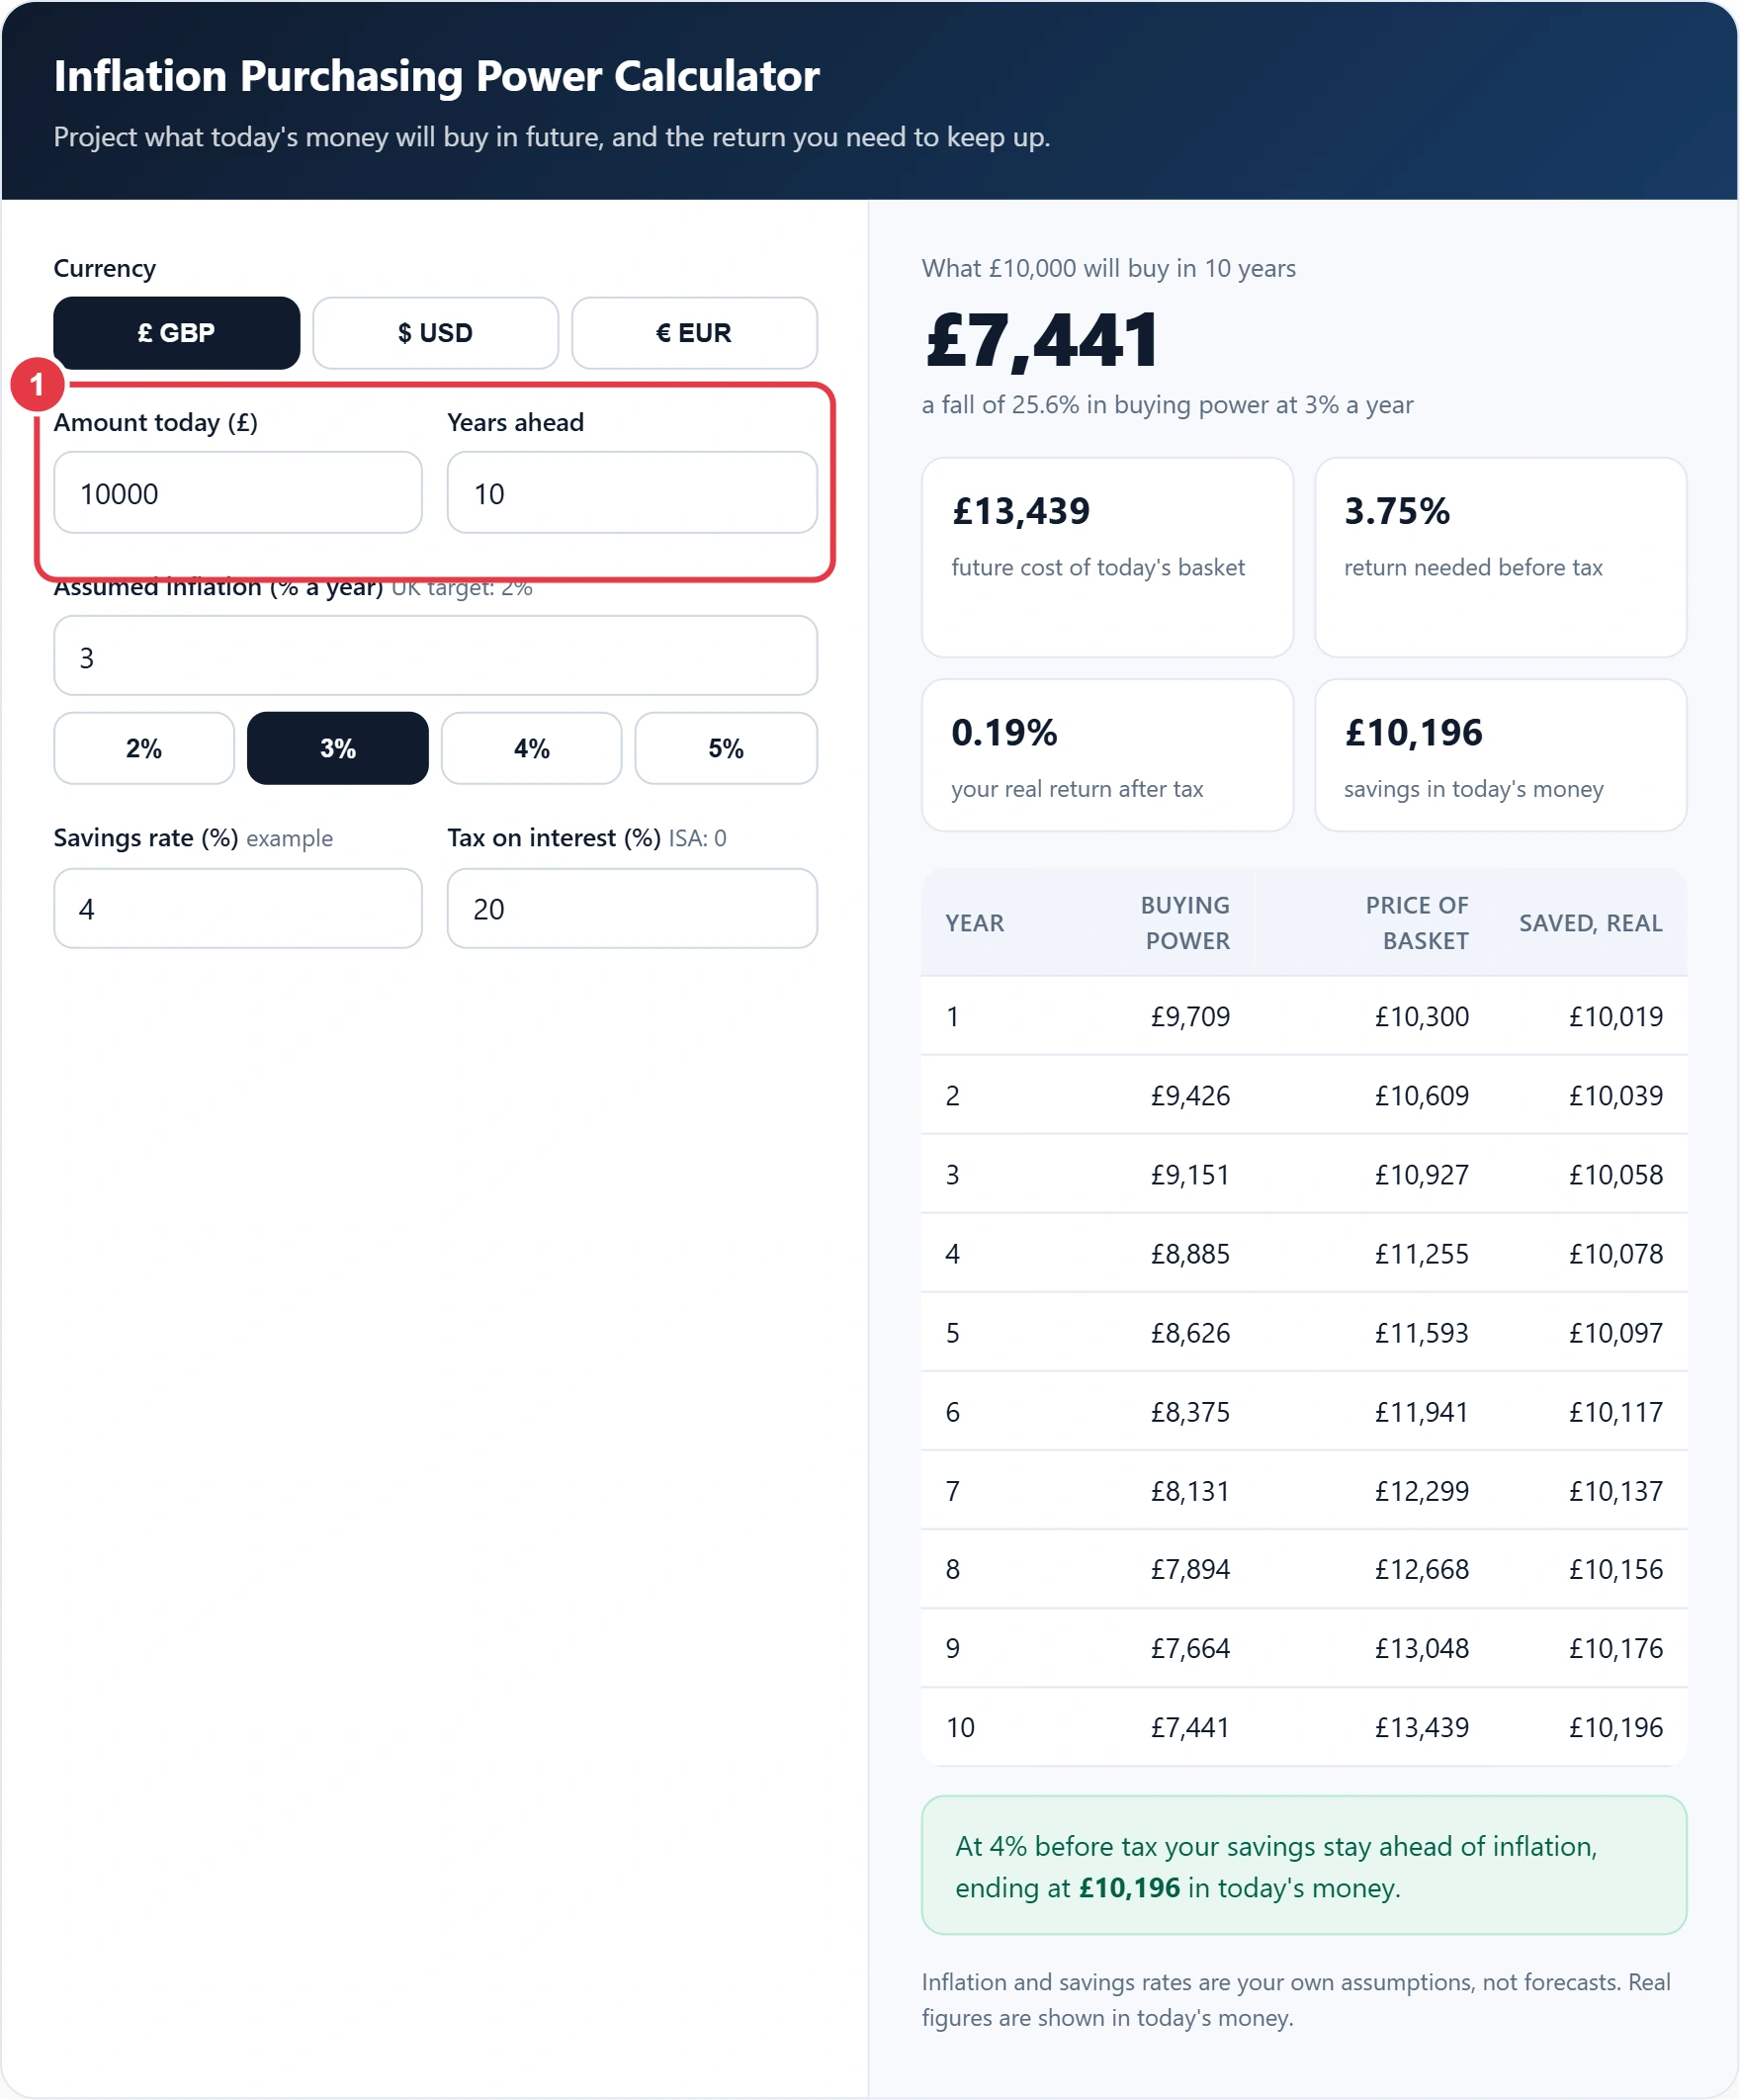
Step 1: Enter the Amount and Years
Choose your currency, then type the sum you are thinking about and how far ahead you want to look. This could be savings for a goal, a fixed pension income or a lump sum you are holding in cash.
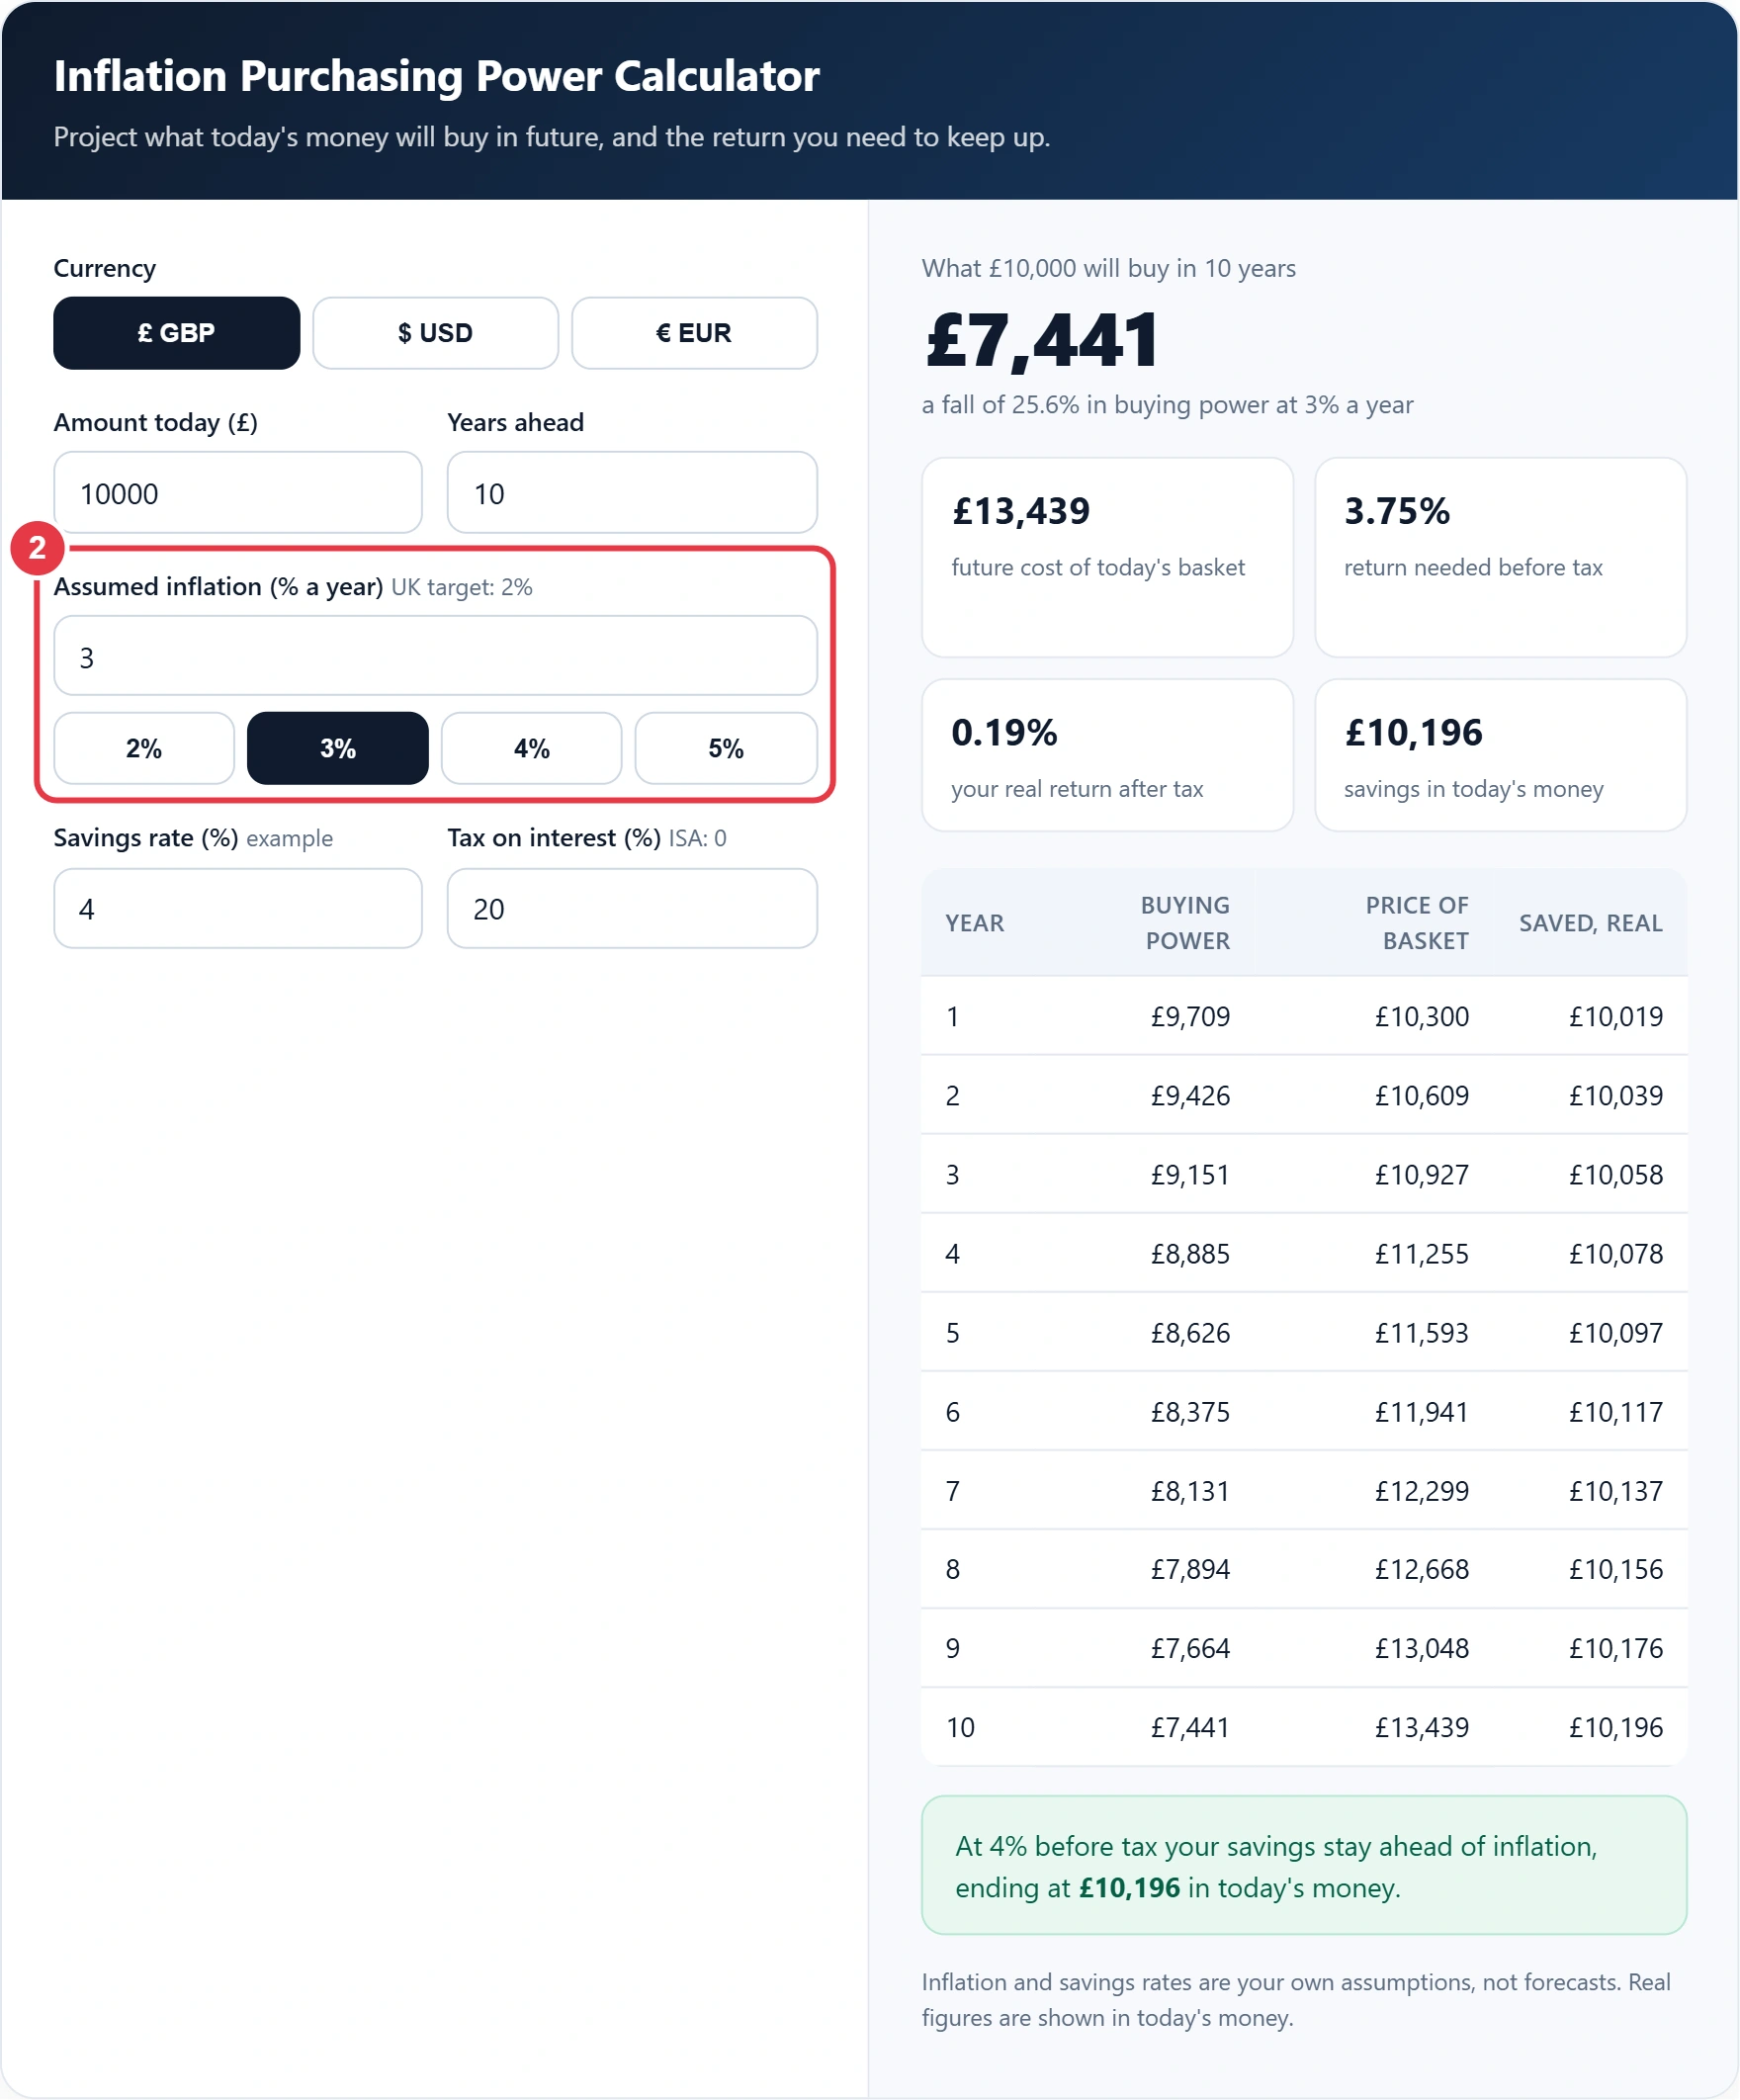
Step 2: Set an Inflation Rate
Nobody knows future inflation, so test a few rates. The Bank of England aims for 2% inflation over time, but actual rates have often run above that, so trying 3% or 4% gives a more cautious picture.
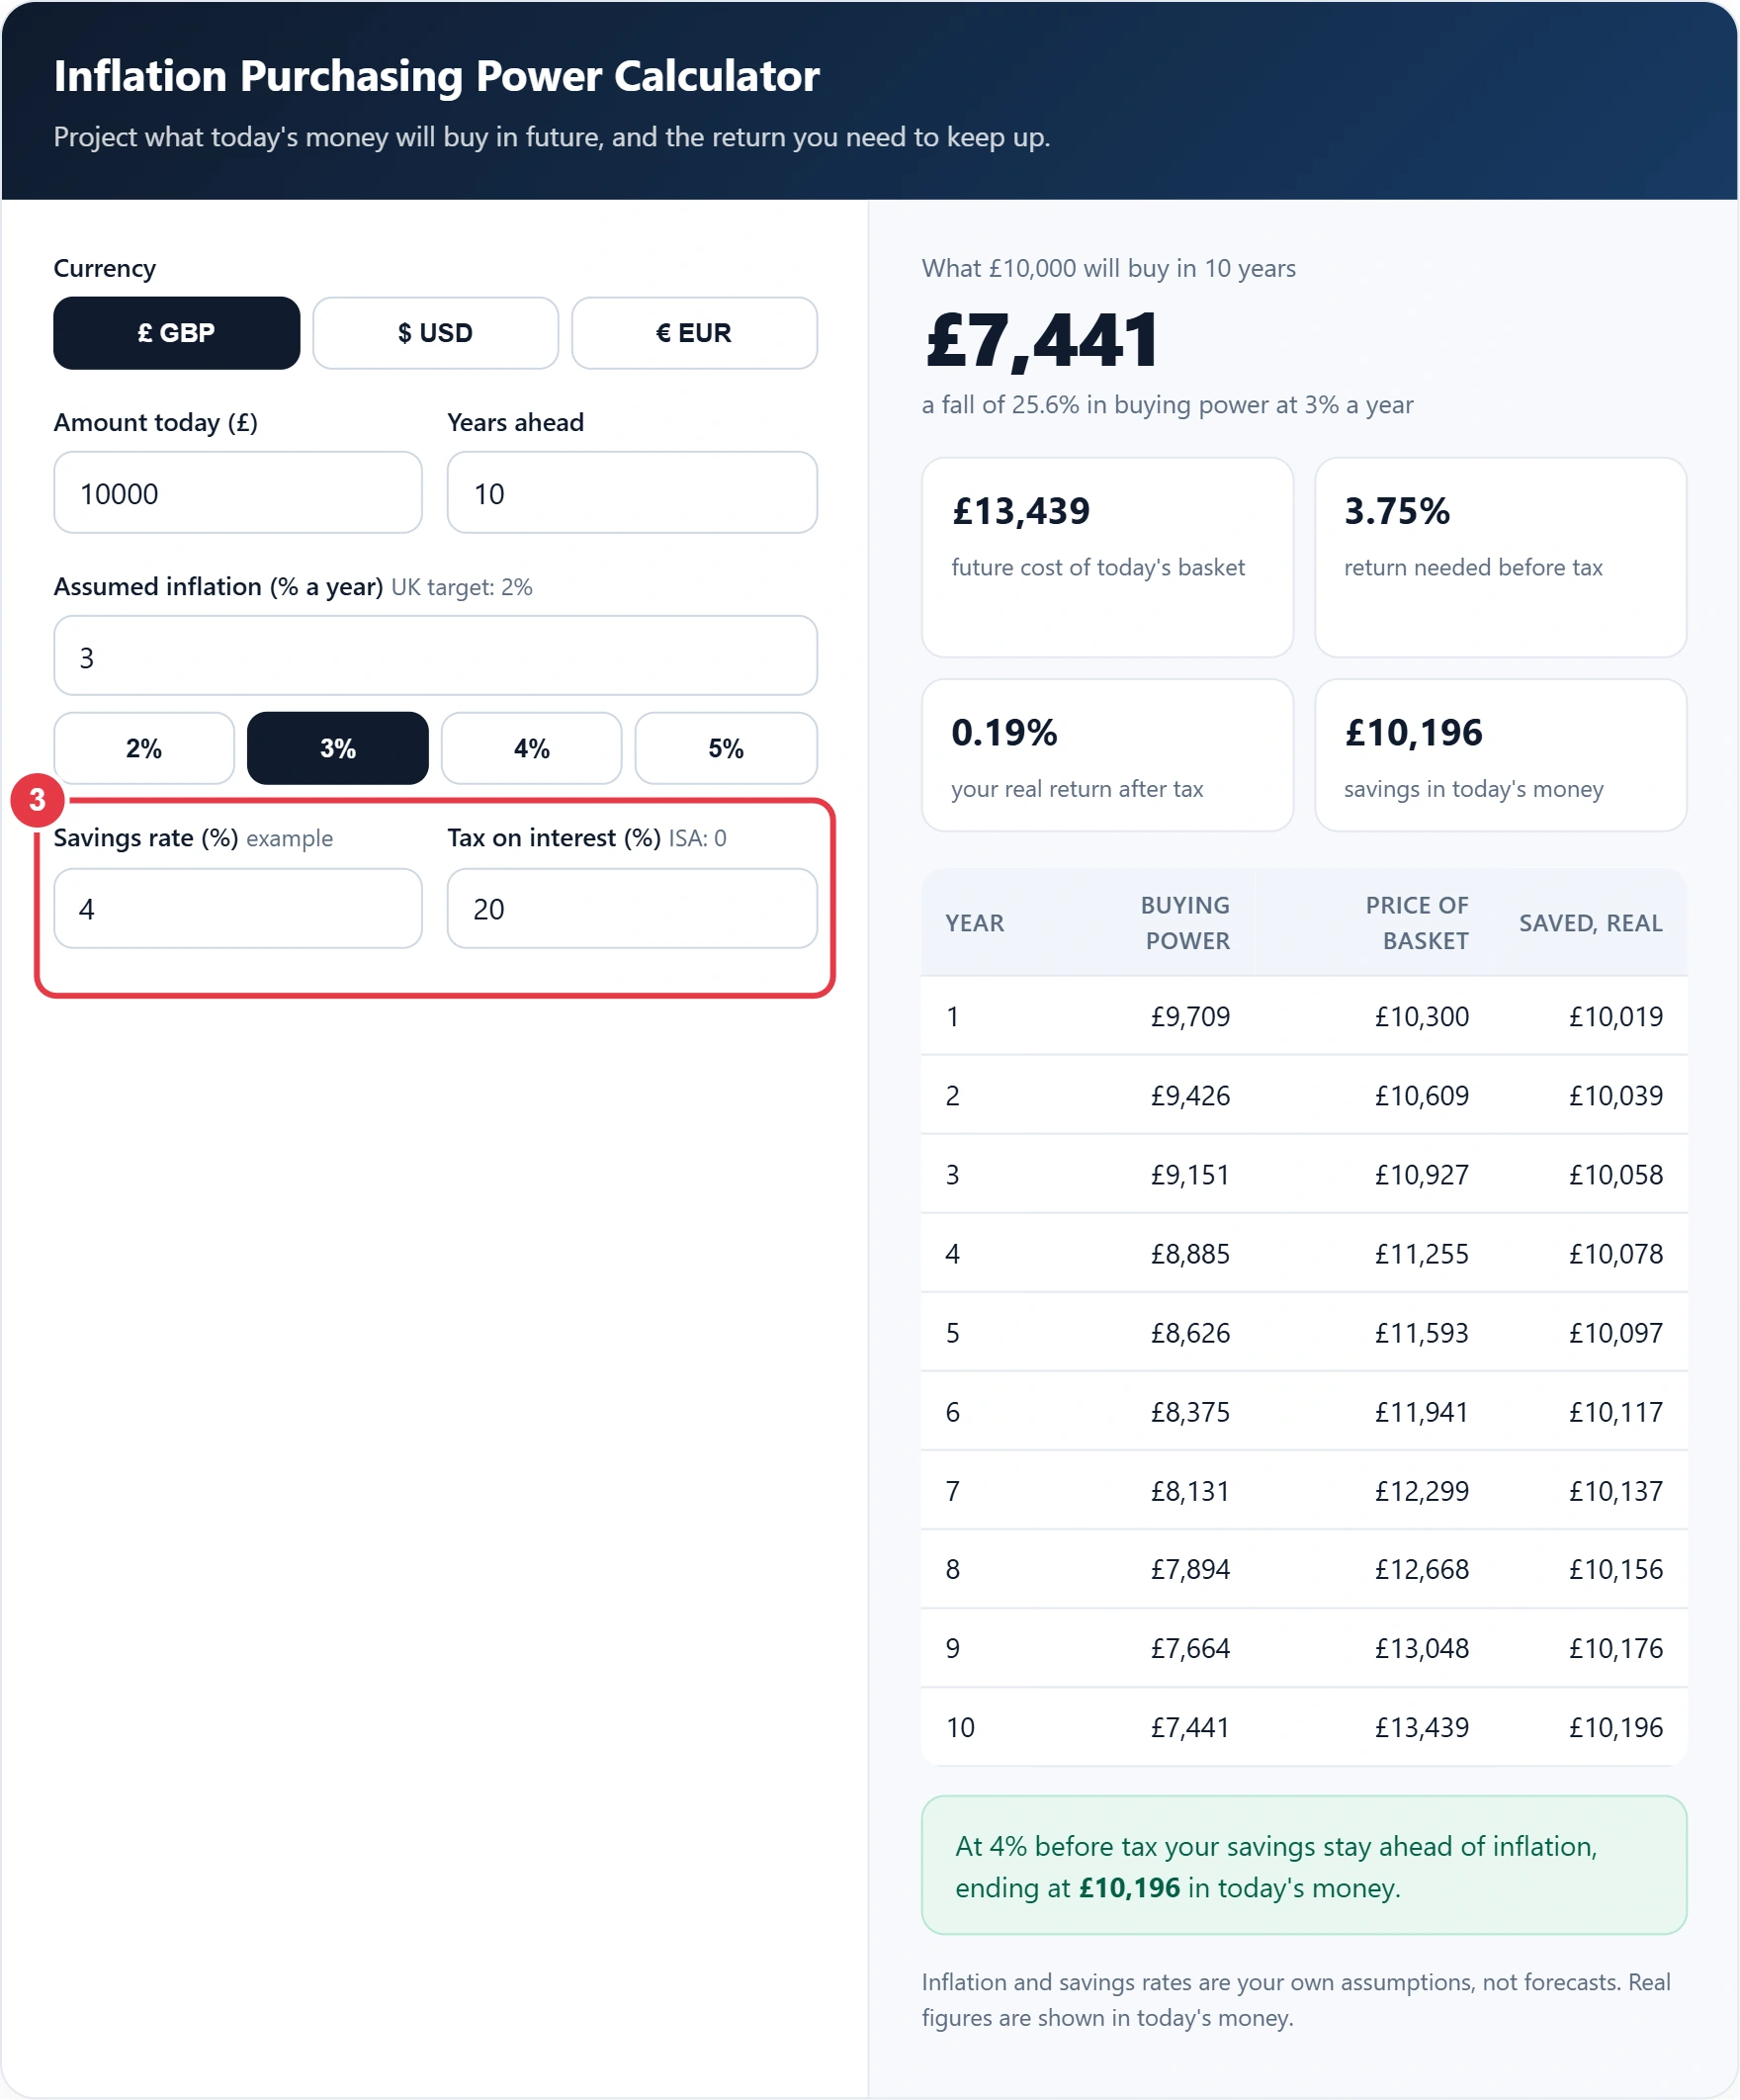
Step 3: Add Your Savings Rate and Tax
Enter the rate your money earns and the tax you pay on that return. Set tax to 0 for an ISA or for interest within your personal savings allowance. If you add to the pot every month, the savings interest calculator handles regular deposits before you bring the result back here.
Step 4: Read Your Results
You see future buying power, the future price of what your money buys today, the gross return needed to keep pace and your real return after tax. The table tracks all three over the years so you can see how fast the gap opens.

How Inflation Erodes £10,000
| Inflation rate | Buying power after 10 years | Buying power after 20 years |
|---|---|---|
| 2% | £8,203 | £6,730 |
| 3% | £7,441 | £5,537 |
| 4% | £6,756 | £4,564 |
| 5% | £6,139 | £3,769 |
Small differences compound into big ones over two decades. To see how UK prices have actually moved month by month, the ONS inflation and price indices publish the official CPI series, which is a sensible anchor when you choose your own assumption.
Purchasing Power Terms You Should Know
These terms explain the forward looking sums behind the inflation purchasing power calculator, so you can judge what today's money and savings will buy later.
- Purchasing power
- The quantity of goods and services a sum of money can buy at a given time. It falls as prices rise, so a fixed amount held for many years pays for less even though its face value never changes.
- Real value
- A future sum restated in today's money by dividing it by one plus the inflation rate, raised to the number of years. It shows what money set aside now will really be able to buy later.
- Future price
- The projected cost of something after years of inflation, found by compounding today's price at the assumed rate. At 3% a year, a £10,000 purchase is projected to cost about £13,439 after ten years.
- Break even savings rate
- The gross interest rate needed for savings to keep pace with inflation after tax is paid. With interest taxed at 20% and inflation at 3%, the account must pay at least 3.75% before tax.
- Personal Savings Allowance
- The amount of savings interest a UK taxpayer can receive each year before any tax is due, with the limit depending on their income tax band. Interest within it, or inside an ISA, has a tax rate of zero.
- Individual Savings Account (ISA)
- A UK savings or investment wrapper in which interest and gains are free of tax. Using one removes the tax drag from returns, which lowers the rate needed to stay ahead of rising prices.
</>Embed this calculator on your website
Add the free Inflation Purchasing Power Calculator to your own site or blog. Copy the code below and paste it into an HTML block. It resizes itself and works on phones.
How we checked this tool: the Tools Veria Editorial Team built this tool by hand, checked it against the official rules or published standards where they apply, and tested it against worked examples. Results are estimates for planning, not personal financial or tax advice. Read our editorial policy and disclaimer, or report an error.
Frequently Asked Questions
How is this different from the UK inflation calculator?
The UK inflation calculator converts amounts between past years using real ONS CPI data. This tool looks forward, using an inflation rate you choose to estimate future buying power.
What inflation rate should I use for planning?
Try a range. The Bank of England target of 2% is a floor for many planners, and 3% or 4% shows what happens if prices run hotter.
Why does tax raise the return I need?
Tax takes a slice of the interest but not of inflation. At 3% inflation and 20% tax, you need 3.75% before tax to stay level after tax.
What is a real return?
It is your return after inflation. The tool uses (1 + after tax return) ÷ (1 + inflation) − 1, which is more accurate than simply subtracting one rate from the other.
Does inflation affect a fixed pension income?
Yes. A fixed £1,000 a month buys less every year, so enter it here to see its value in today's money at any future date.
Is cash in an ISA protected from inflation?
No. An ISA protects you from tax on interest, not from rising prices. You still need a rate at or above inflation to keep your buying power.