Compare both corporate methods, pay the lower one, or check the flat LLC, LP and GP tax.
Estimate based on the Delaware Division of Corporations rules: $175 minimum and $85 per extra 10,000 shares, $400 per million of assumed par value capital, $200,000 maximum, $50 annual report fee, $200 late penalty and 1.5% interest a month (simple interest assumed here). Your official bill is on the Division's filing system.
This Delaware franchise tax calculator is for founders, finance teams and accountants who need the real annual franchise tax for a Delaware corporation, or the flat tax for a Delaware LLC, LP or GP, in 2026. It works out both corporate methods set by the Delaware General Corporation Law, picks the lower one and adds the annual report fee and any late penalty, so a scary first bill can be checked in seconds. Figures checked October 2026 against the Delaware Division of Corporations.
Quick answer: Delaware corporations pay the lower of two methods. The Authorized Shares Method charges $175 up to 5,000 shares, $250 up to 10,000 and $85 for each extra 10,000. The Assumed Par Value Capital Method charges $400 per million, minimum $400. A Delaware franchise tax calculator cuts an $85,165 bill to $400 for a typical startup.
In This Guide
What Is the Delaware Franchise Tax?
The Delaware franchise tax is an annual tax every corporation incorporated in Delaware pays for the right to exist there, whether or not it trades in the state or makes a profit. It is not an income tax: it is based on your share structure and, if you choose, your gross assets.
The two formulas in plain words. Authorized Shares Method: $175 for 5,000 shares or fewer, $250 for 5,001 to 10,000, then $85 for every further 10,000 shares or part of 10,000. Assumed Par Value Capital Method: divide total gross assets by issued shares to six decimal places to get the assumed par; multiply it by the authorized shares whose par is lower; add the par value of any shares whose par is higher; then charge $400 for each million, rounding up to the next million. Either way the tax is never below $175 or above $200,000, or $250,000 for a large corporate filer.
How to Use the Delaware Franchise Tax Calculator
Step 1: Choose the Entity and Enter Authorized Shares
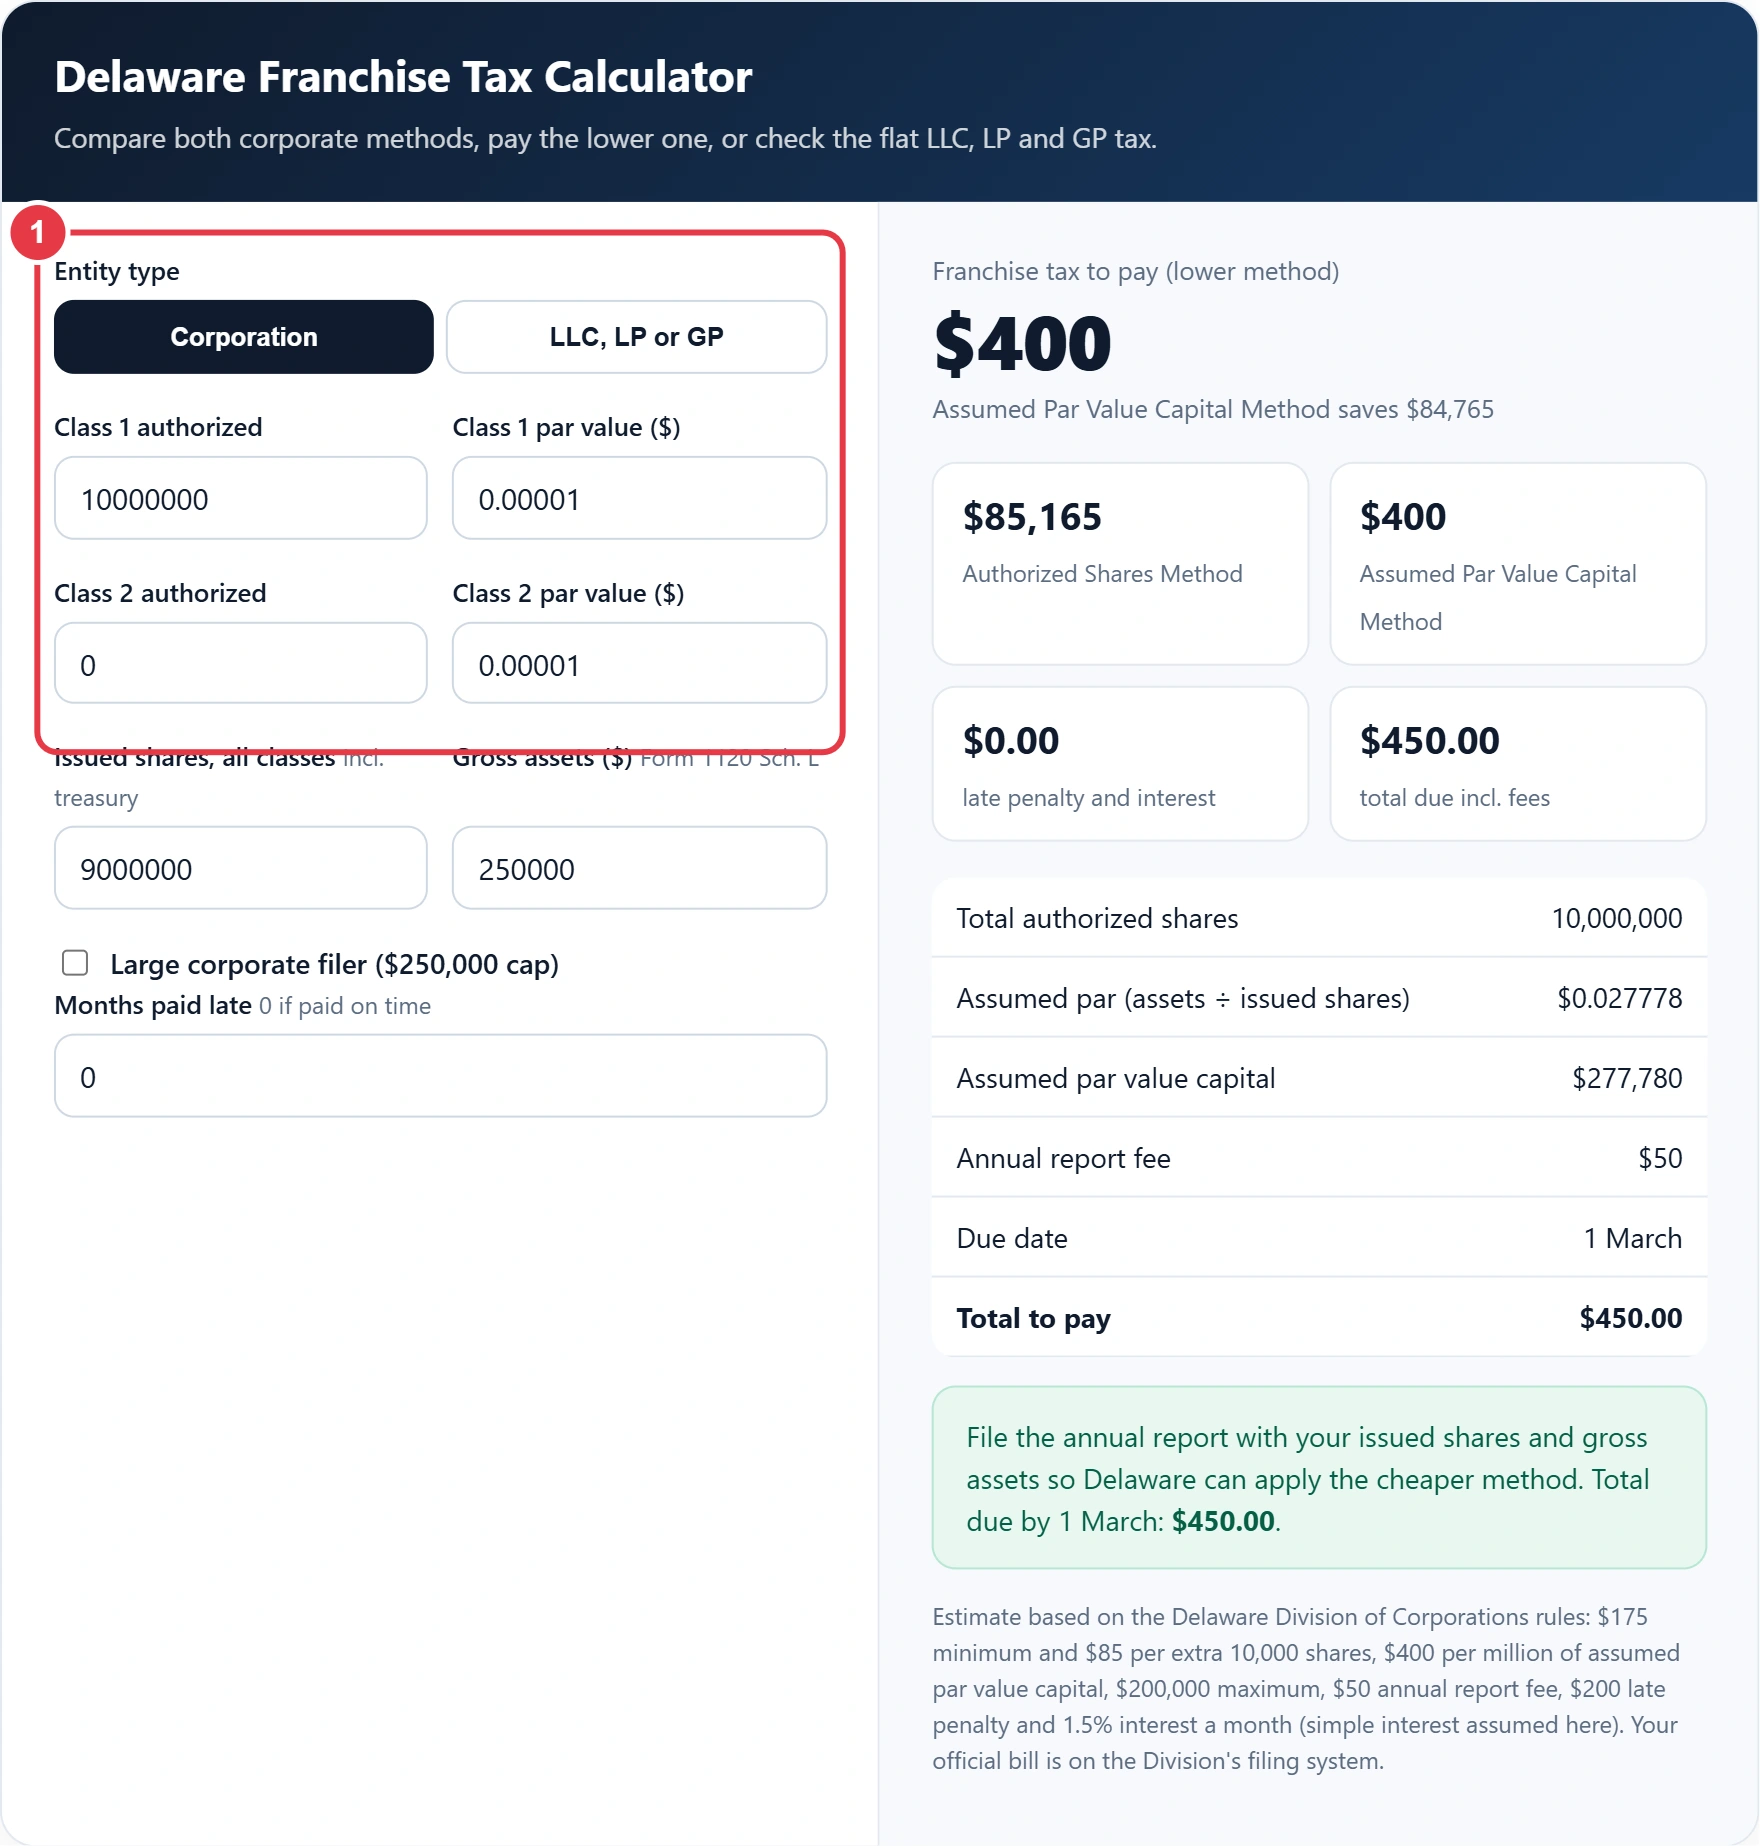
Pick Corporation or LLC, LP or GP. For a corporation, copy the authorized shares and par value from your certificate of incorporation. If you have preferred stock with a different par value, enter it as class 2, or leave class 2 at 0 so the asset based method values it correctly.
Step 2: Enter Issued Shares and Gross Assets
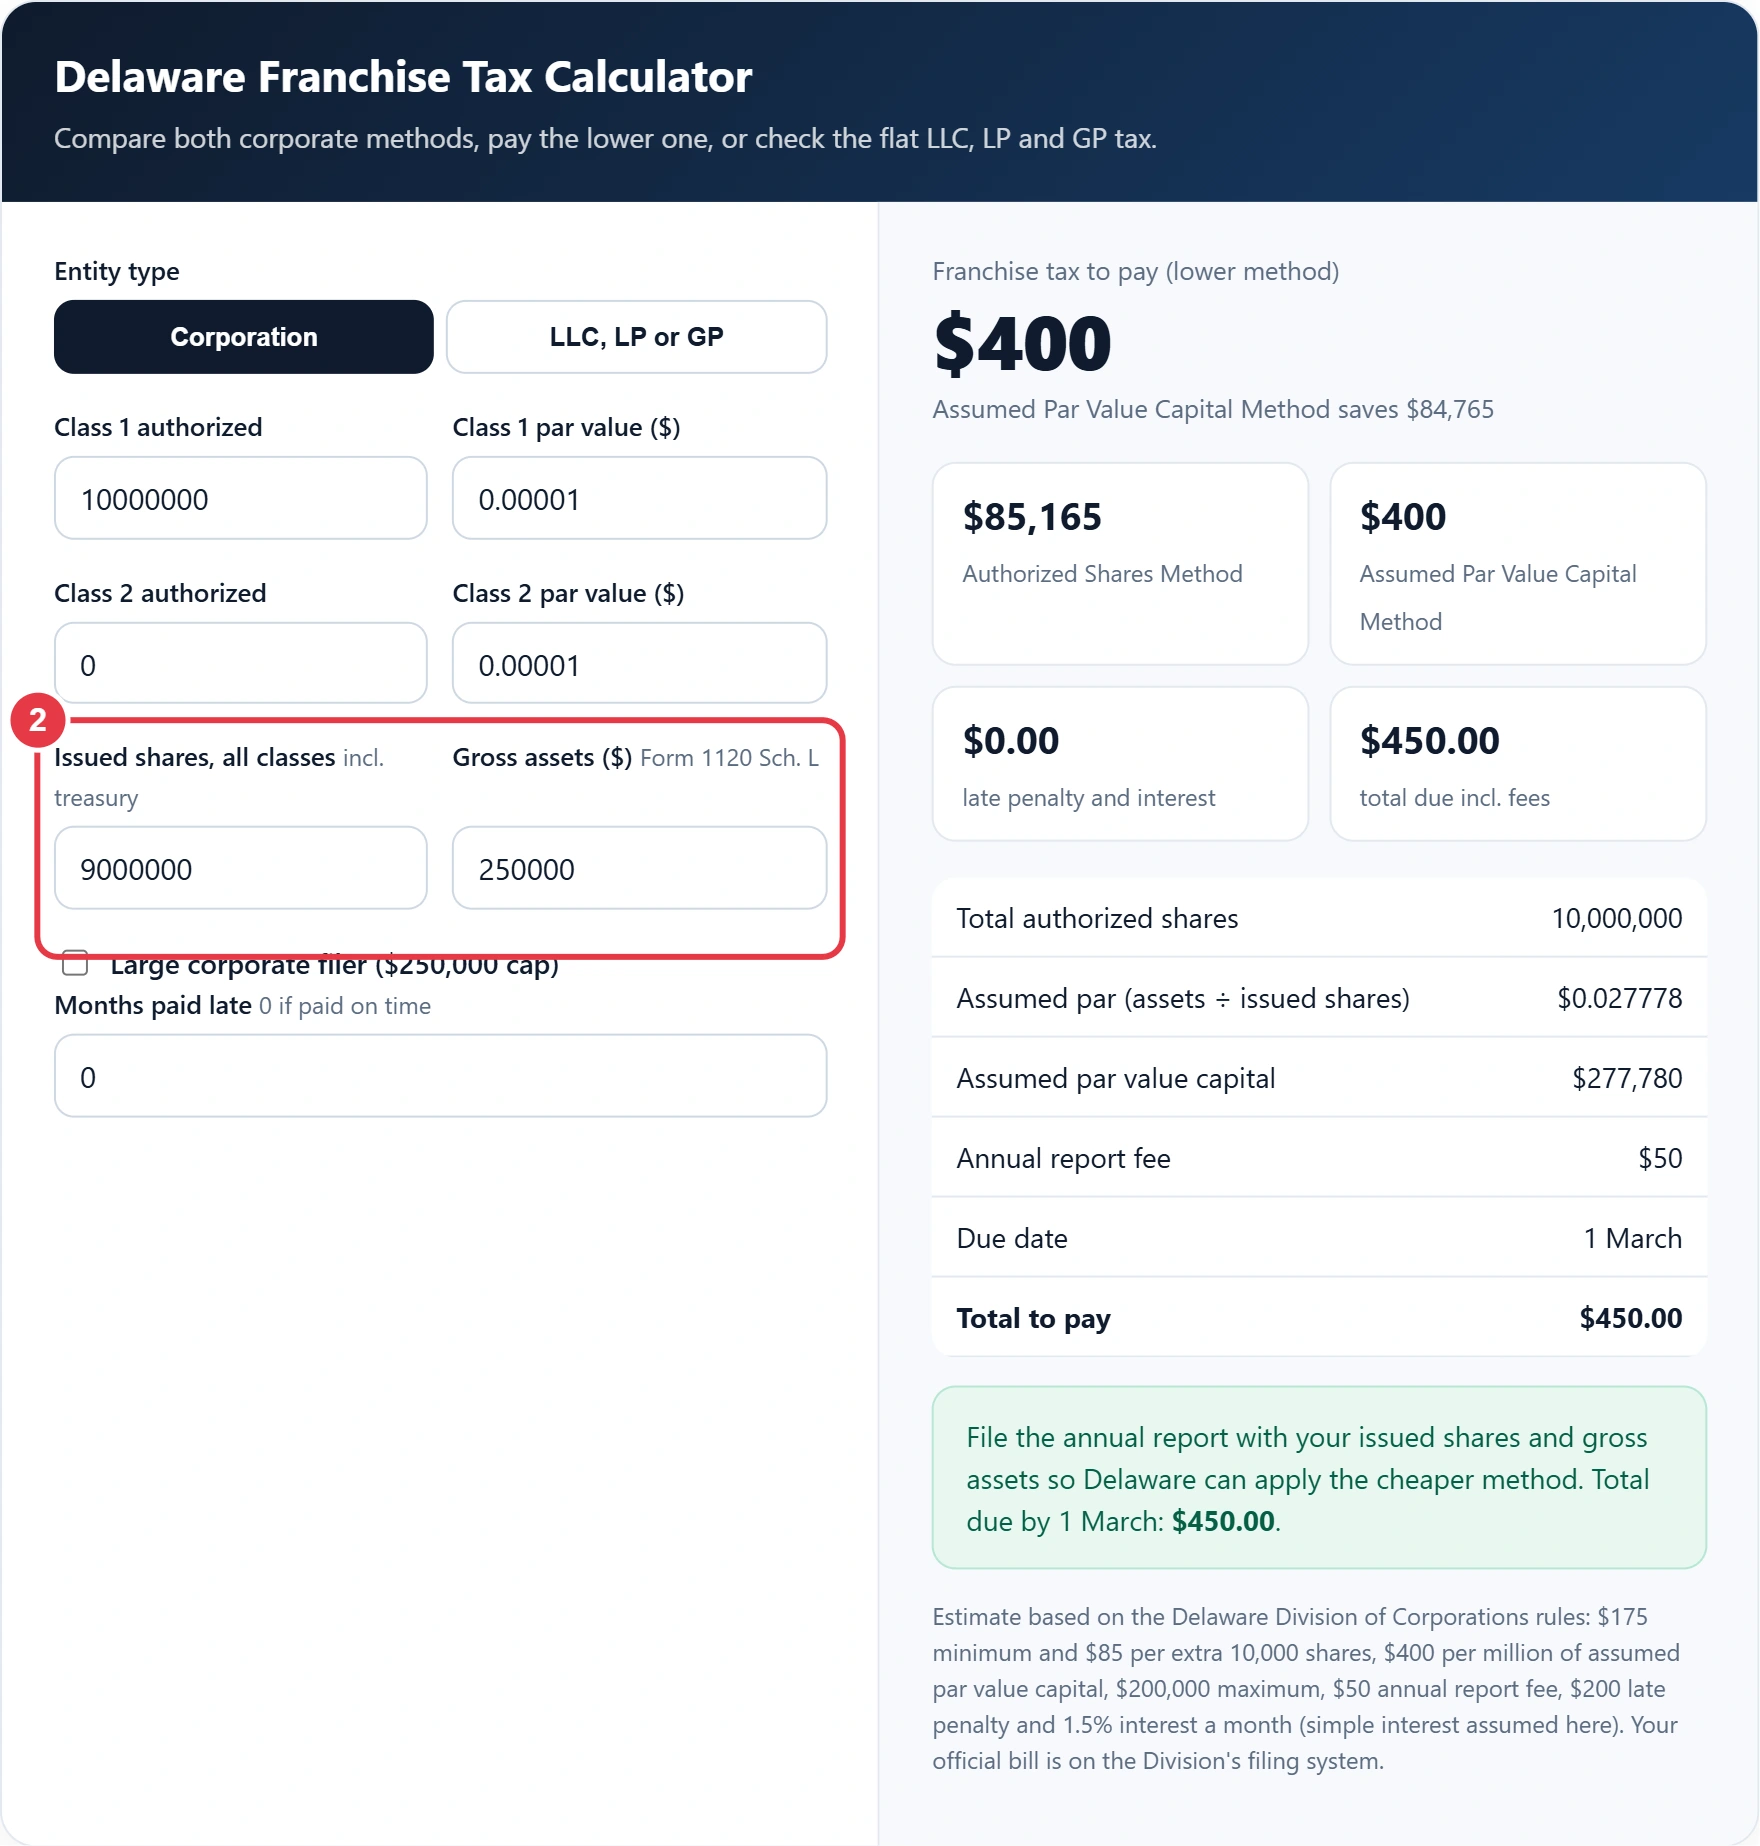
Issued shares are all shares actually issued, including treasury shares, from your cap table. Total gross assets are the total assets on the balance sheet in Schedule L of your federal Form 1120 corporate return for the year ending in the tax year, so draft that first if you can. Without these two numbers Delaware can only use the Authorized Shares Method.
Step 3: Add Large Filer Status and Lateness
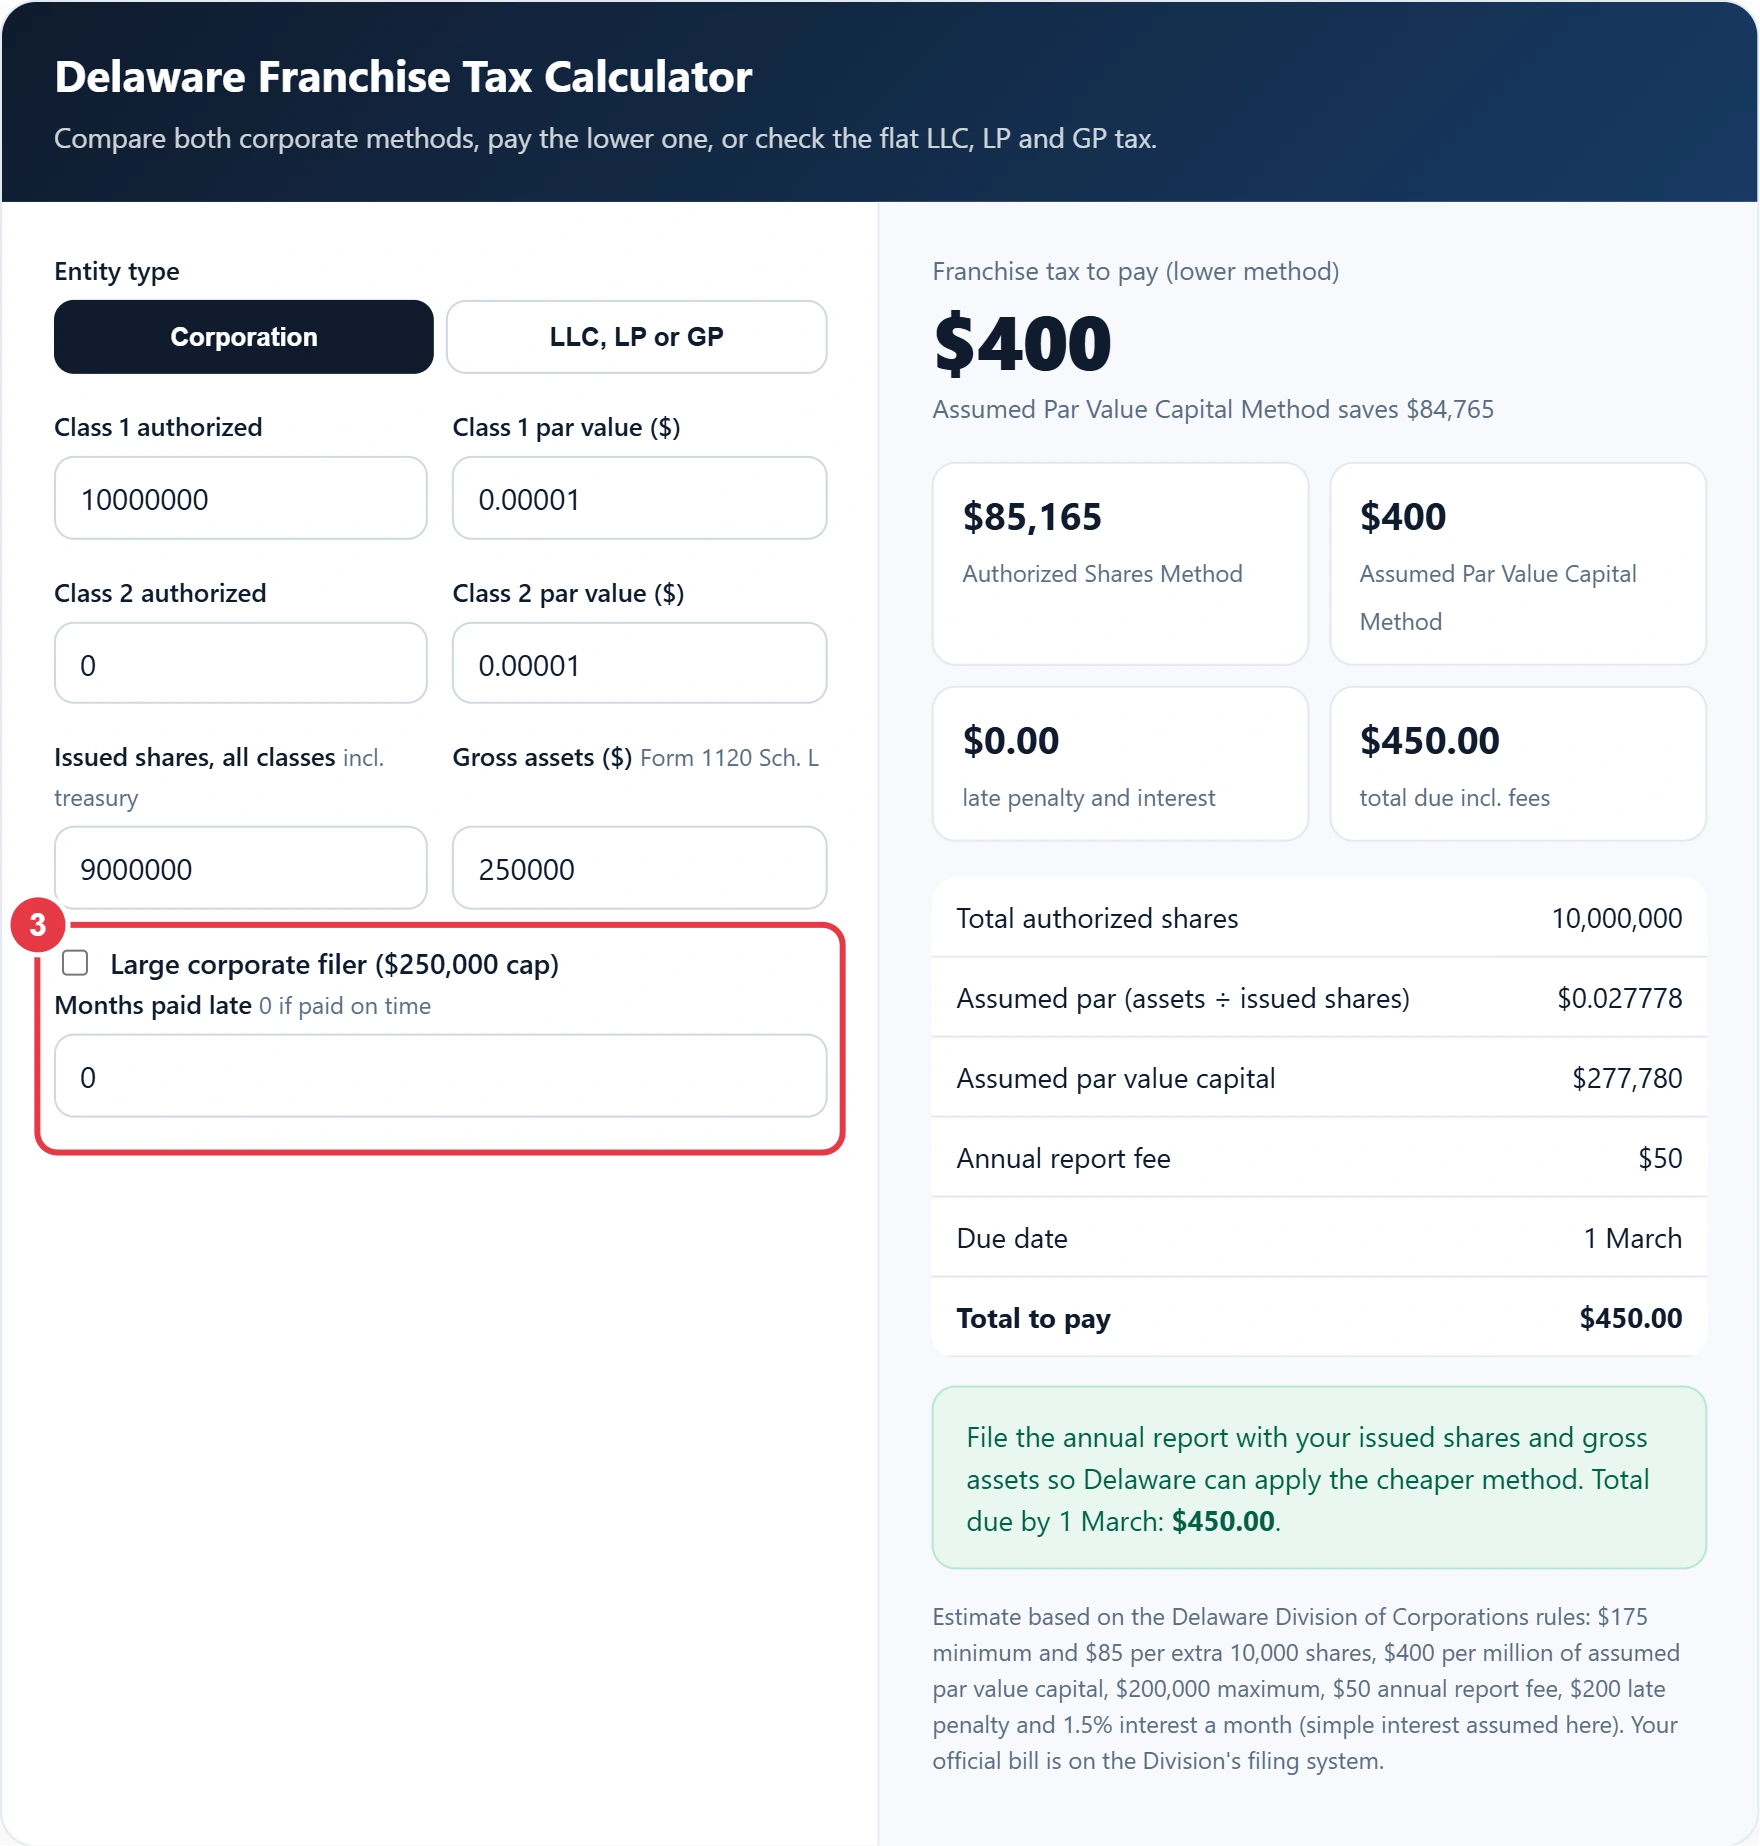
Tick large corporate filer only if Delaware has identified you as one, which raises the cap to $250,000. If you are paying after the due date, enter the number of months late to see the $200 penalty and 1.5% monthly interest on tax and penalty.
Step 4: Read the Lower Tax
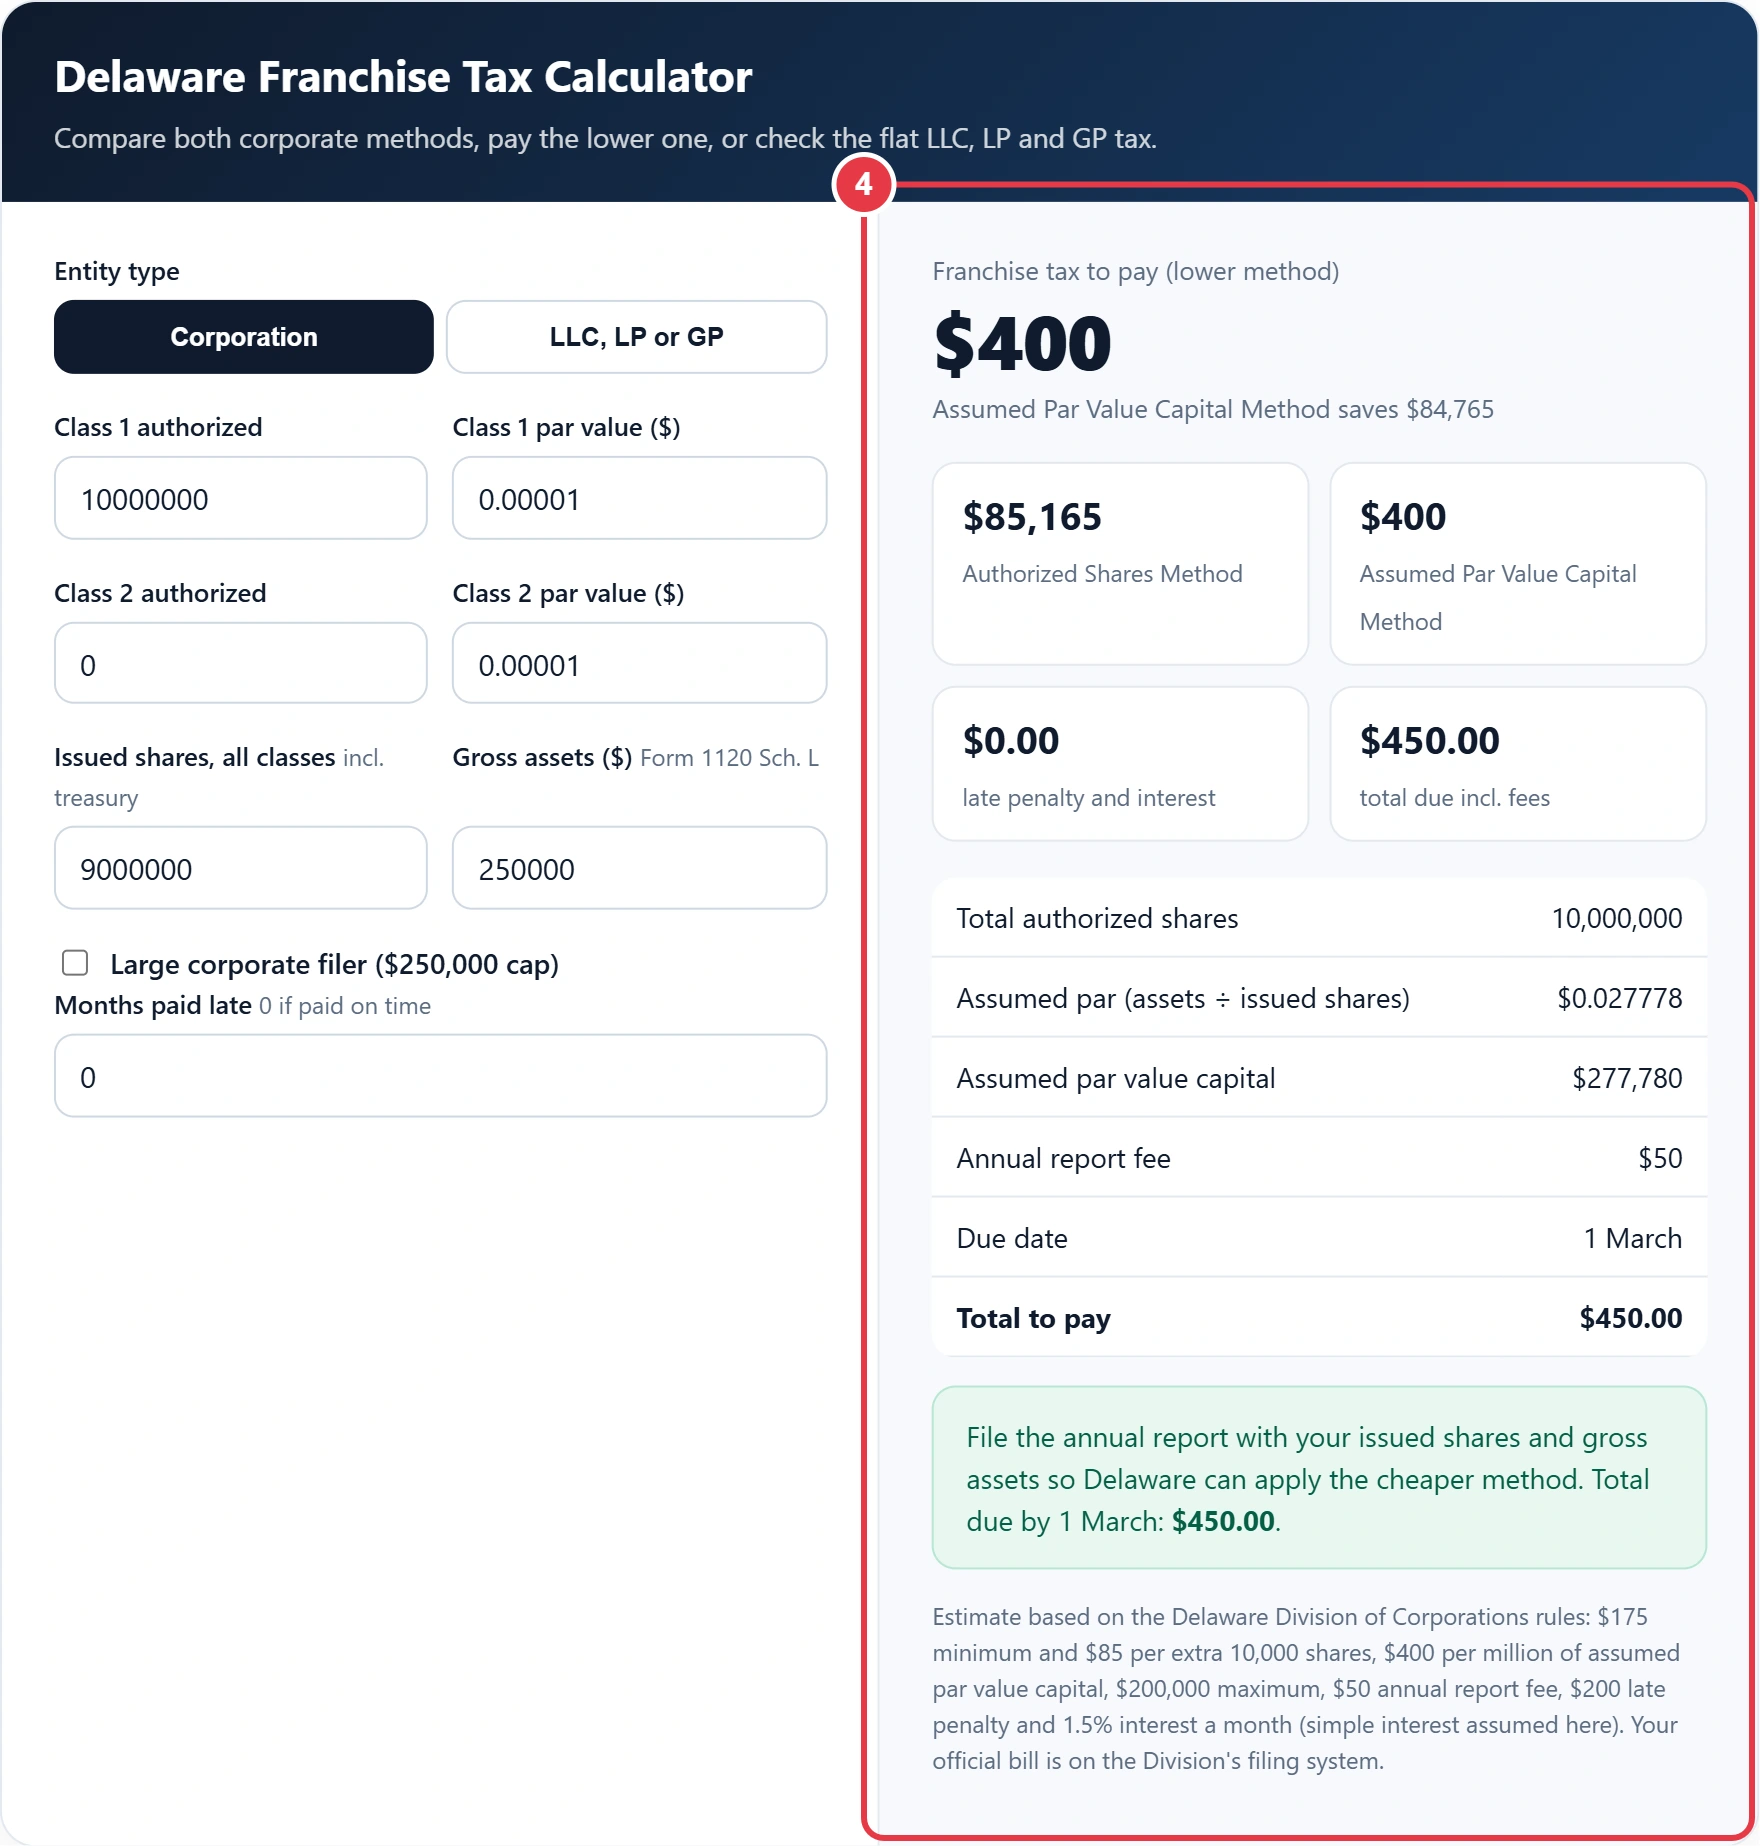
The headline is the tax you should pay. The stats show both methods side by side, the late cost and the total including the $50 annual report fee. If tax is $5,000 or more, the box gives your quarterly instalments.
Why Is My Delaware Franchise Tax Bill So High?
Your bill is high because Delaware's notice uses the Authorized Shares Method by default, and startups often authorise 10 million shares or more. That method charges $85,165 for 10 million shares. Filing the annual report with your issued shares and gross assets lets Delaware use the Assumed Par Value Capital Method, which is usually far cheaper for early stage companies with low assets.
| Authorized shares | Authorized Shares Method tax |
|---|---|
| 5,000 or fewer | $175 |
| 10,000 | $250 |
| 100,000 | $1,015 |
| 1,000,000 | $8,665 |
| 5,000,000 | $42,665 |
| 10,000,000 | $85,165 |
Worked example: Northpine Analytics Inc. has 10,000,000 authorized shares at $0.00001 par, 9,000,000 issued and $250,000 of total gross assets. The assumed par is $250,000 ÷ 9,000,000 = $0.027778. That is higher than the $0.00001 par, so the assumed par value capital is $0.027778 × 10,000,000 = $277,780. That is under $1,000,000, so the tax is the $400 minimum. With the $50 report fee the founders pay $450, not the $85,215 on the notice.
When Is Delaware Franchise Tax Due?
Corporation franchise tax and the annual report for the previous year are due on or before 1 March. Corporations owing $5,000 or more pay estimates of 40% by 1 June, 20% by 1 September, 20% by 1 December and the remainder by 1 March. Missing the deadline costs a $200 penalty plus 1.5% interest a month on the tax and penalty. To count the exact days between the due date and your payment, the days between dates calculator gives the figure instantly, which also helps if a stock amendment means the tax is prorated by days out of 365.
How Much Is Delaware Franchise Tax for an LLC?
Delaware LLCs, limited partnerships and general partnerships pay a flat annual tax, which the Division of Corporations now lists as $400, due on or before 1 June. Because the tax is flat, it matters most for small companies, and the profit margin calculator shows what share of your profit fixed costs like this take up each year. Late payment adds a $200 penalty and 1.5% monthly interest. These entities file no annual report and share numbers do not matter. Some older guides still say $300, so check the amount on your notice.
This Delaware franchise tax calculator gives an estimate. Exempt and non stock corporations, foreign corporations, which file a separate $250 report by 30 June, and mid year amendments are not modelled, so confirm the final figure on the Division's filing system or with your registered agent.
</>Embed this calculator on your website
Add the free Delaware Franchise Tax Calculator to your own site or blog. Copy the code below and paste it into an HTML block. It resizes itself and works on phones.
How we checked this tool: the Tools Veria Editorial Team built this tool by hand, checked it against the official rules or published standards where they apply, and tested it against worked examples. Results are estimates for planning, not personal financial or tax advice. Read our editorial policy and disclaimer, or report an error.
Frequently Asked Questions
How is Delaware franchise tax calculated for a startup?
Delaware charges the lower of two methods. Most startups should file using the Assumed Par Value Capital Method: gross assets divided by issued shares gives the assumed par, which is multiplied by authorized shares and taxed at $400 per million, with a $400 minimum.
What is the minimum Delaware franchise tax?
The minimum is $175 using the Authorized Shares Method, for 5,000 shares or fewer, and $400 using the Assumed Par Value Capital Method. A corporation also pays a $50 annual report fee, so the smallest total bill is $225.
What is the maximum Delaware franchise tax?
The maximum is $200,000 a year under either method. Corporations Delaware identifies as large corporate filers pay up to $250,000 instead. Both caps are set by the Delaware Division of Corporations.
When is Delaware franchise tax due in 2027?
The annual report and franchise tax for 2026 are due on or before 1 March 2027. Companies owing $5,000 or more should already have paid estimates of 40%, 20% and 20% by 1 June, 1 September and 1 December 2026.
What happens if I pay Delaware franchise tax late?
Delaware adds a $200 penalty plus interest of 1.5% a month on the unpaid tax and penalty. A $400 tax paid three months late costs about $27 in interest on top of the $200 penalty, so roughly $627 before the report fee.
Do Delaware LLCs pay franchise tax?
Delaware LLCs pay a flat annual tax rather than the share based franchise tax. The Division of Corporations lists it as $400, due by 1 June each year, with a $200 penalty and 1.5% monthly interest for late payment.