See whether owning or renting leaves you wealthier after the years you choose.
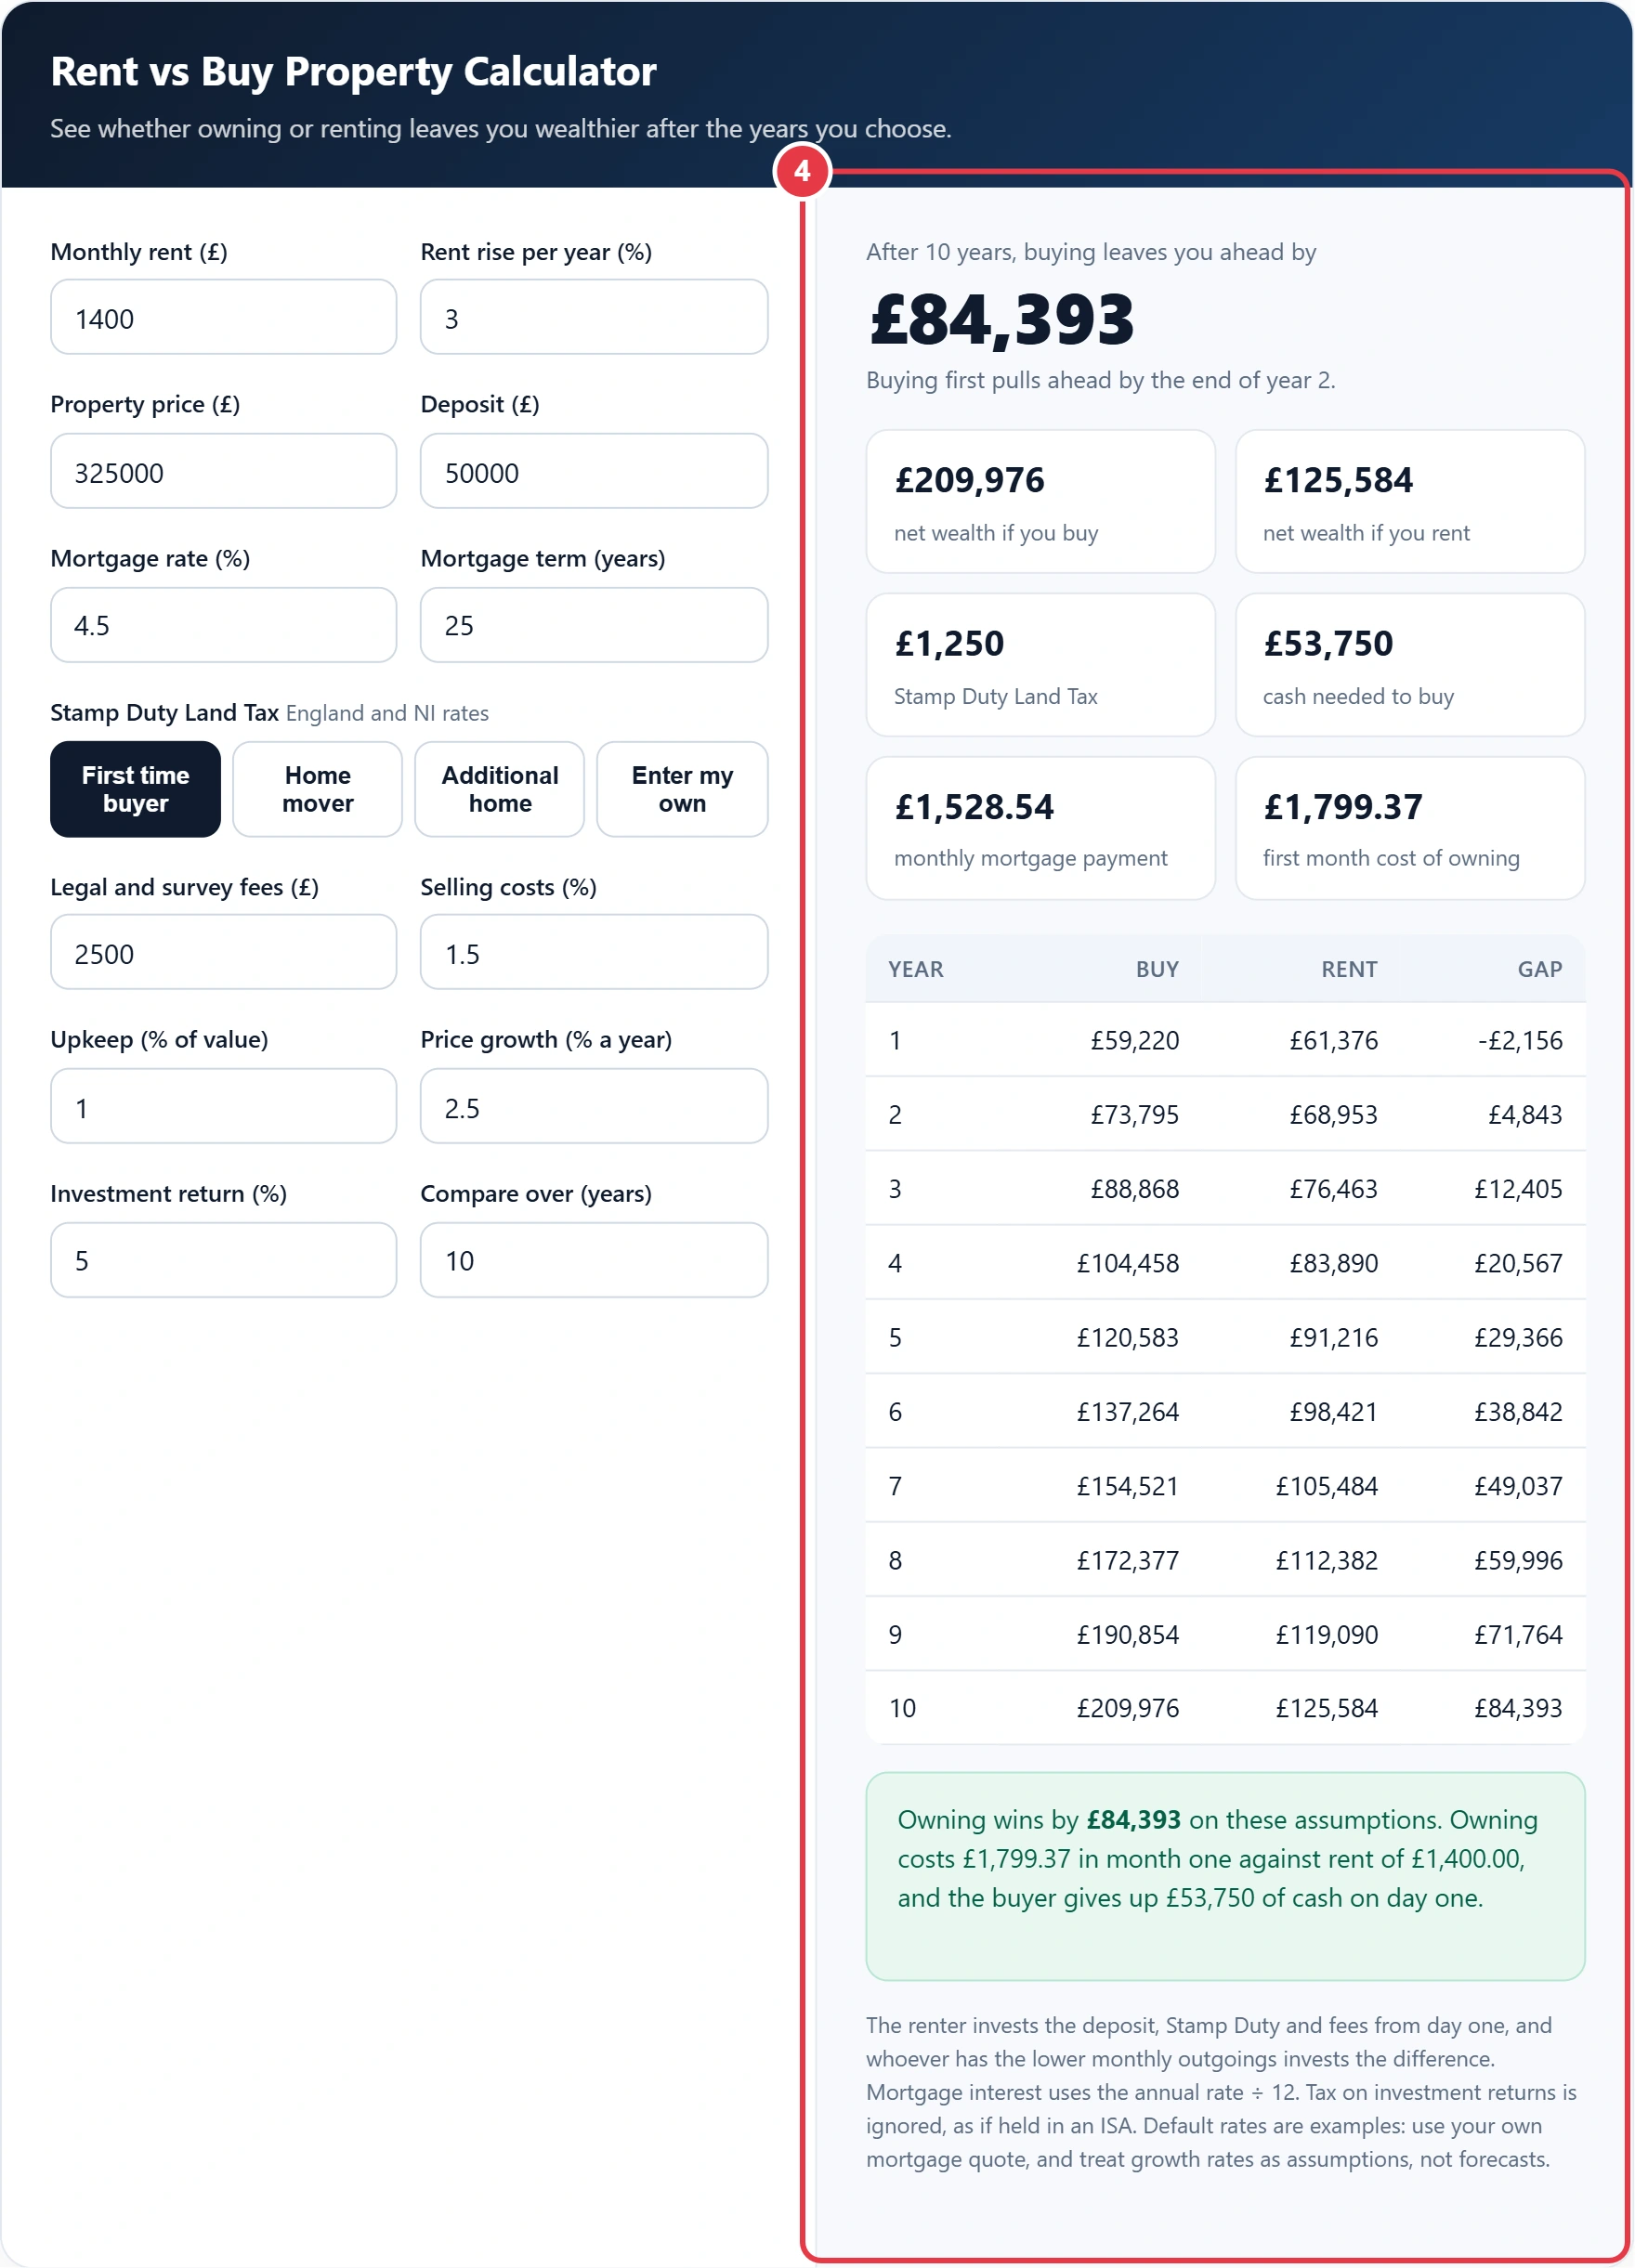
| Year | Buy | Rent | Gap |
|---|
The renter invests the deposit, Stamp Duty and fees from day one, and whoever has the lower monthly outgoings invests the difference. Mortgage interest uses the annual rate ÷ 12. Tax on investment returns is ignored, as if held in an ISA. Default rates are examples: use your own mortgage quote, and treat growth rates as assumptions, not forecasts.
This rent vs buy property calculator shows UK renters whether buying a home or carrying on renting leaves them wealthier after a set number of years. It adds Stamp Duty Land Tax using the current GOV.UK residential rates for England and Northern Ireland, then counts the returns your deposit could have earned if you kept renting instead of buying.
Quick answer: A rent vs buy property calculator compares your net wealth as a homeowner after a set number of years with your wealth as a renter who invests the deposit, Stamp Duty and fees instead. Only costs that never come back count against you: rent, mortgage interest, upkeep, Stamp Duty and fees, while repaid capital becomes equity.
In This Guide
What Is a Rent vs Buy Calculation?
A rent vs buy calculation compares your net wealth after a chosen number of years as a homeowner with your net wealth as a renter who invests the same money instead. For the buyer, wealth is the home's value minus selling costs and the remaining mortgage, plus any cash left over each month. For the renter, it is the deposit, Stamp Duty and fees invested on day one, plus the monthly difference whenever renting is cheaper than owning.
Only costs that never come back count against you: rent, mortgage interest, upkeep, Stamp Duty and fees. Repaid mortgage capital becomes equity.
How to Use the Rent vs Buy Property Calculator
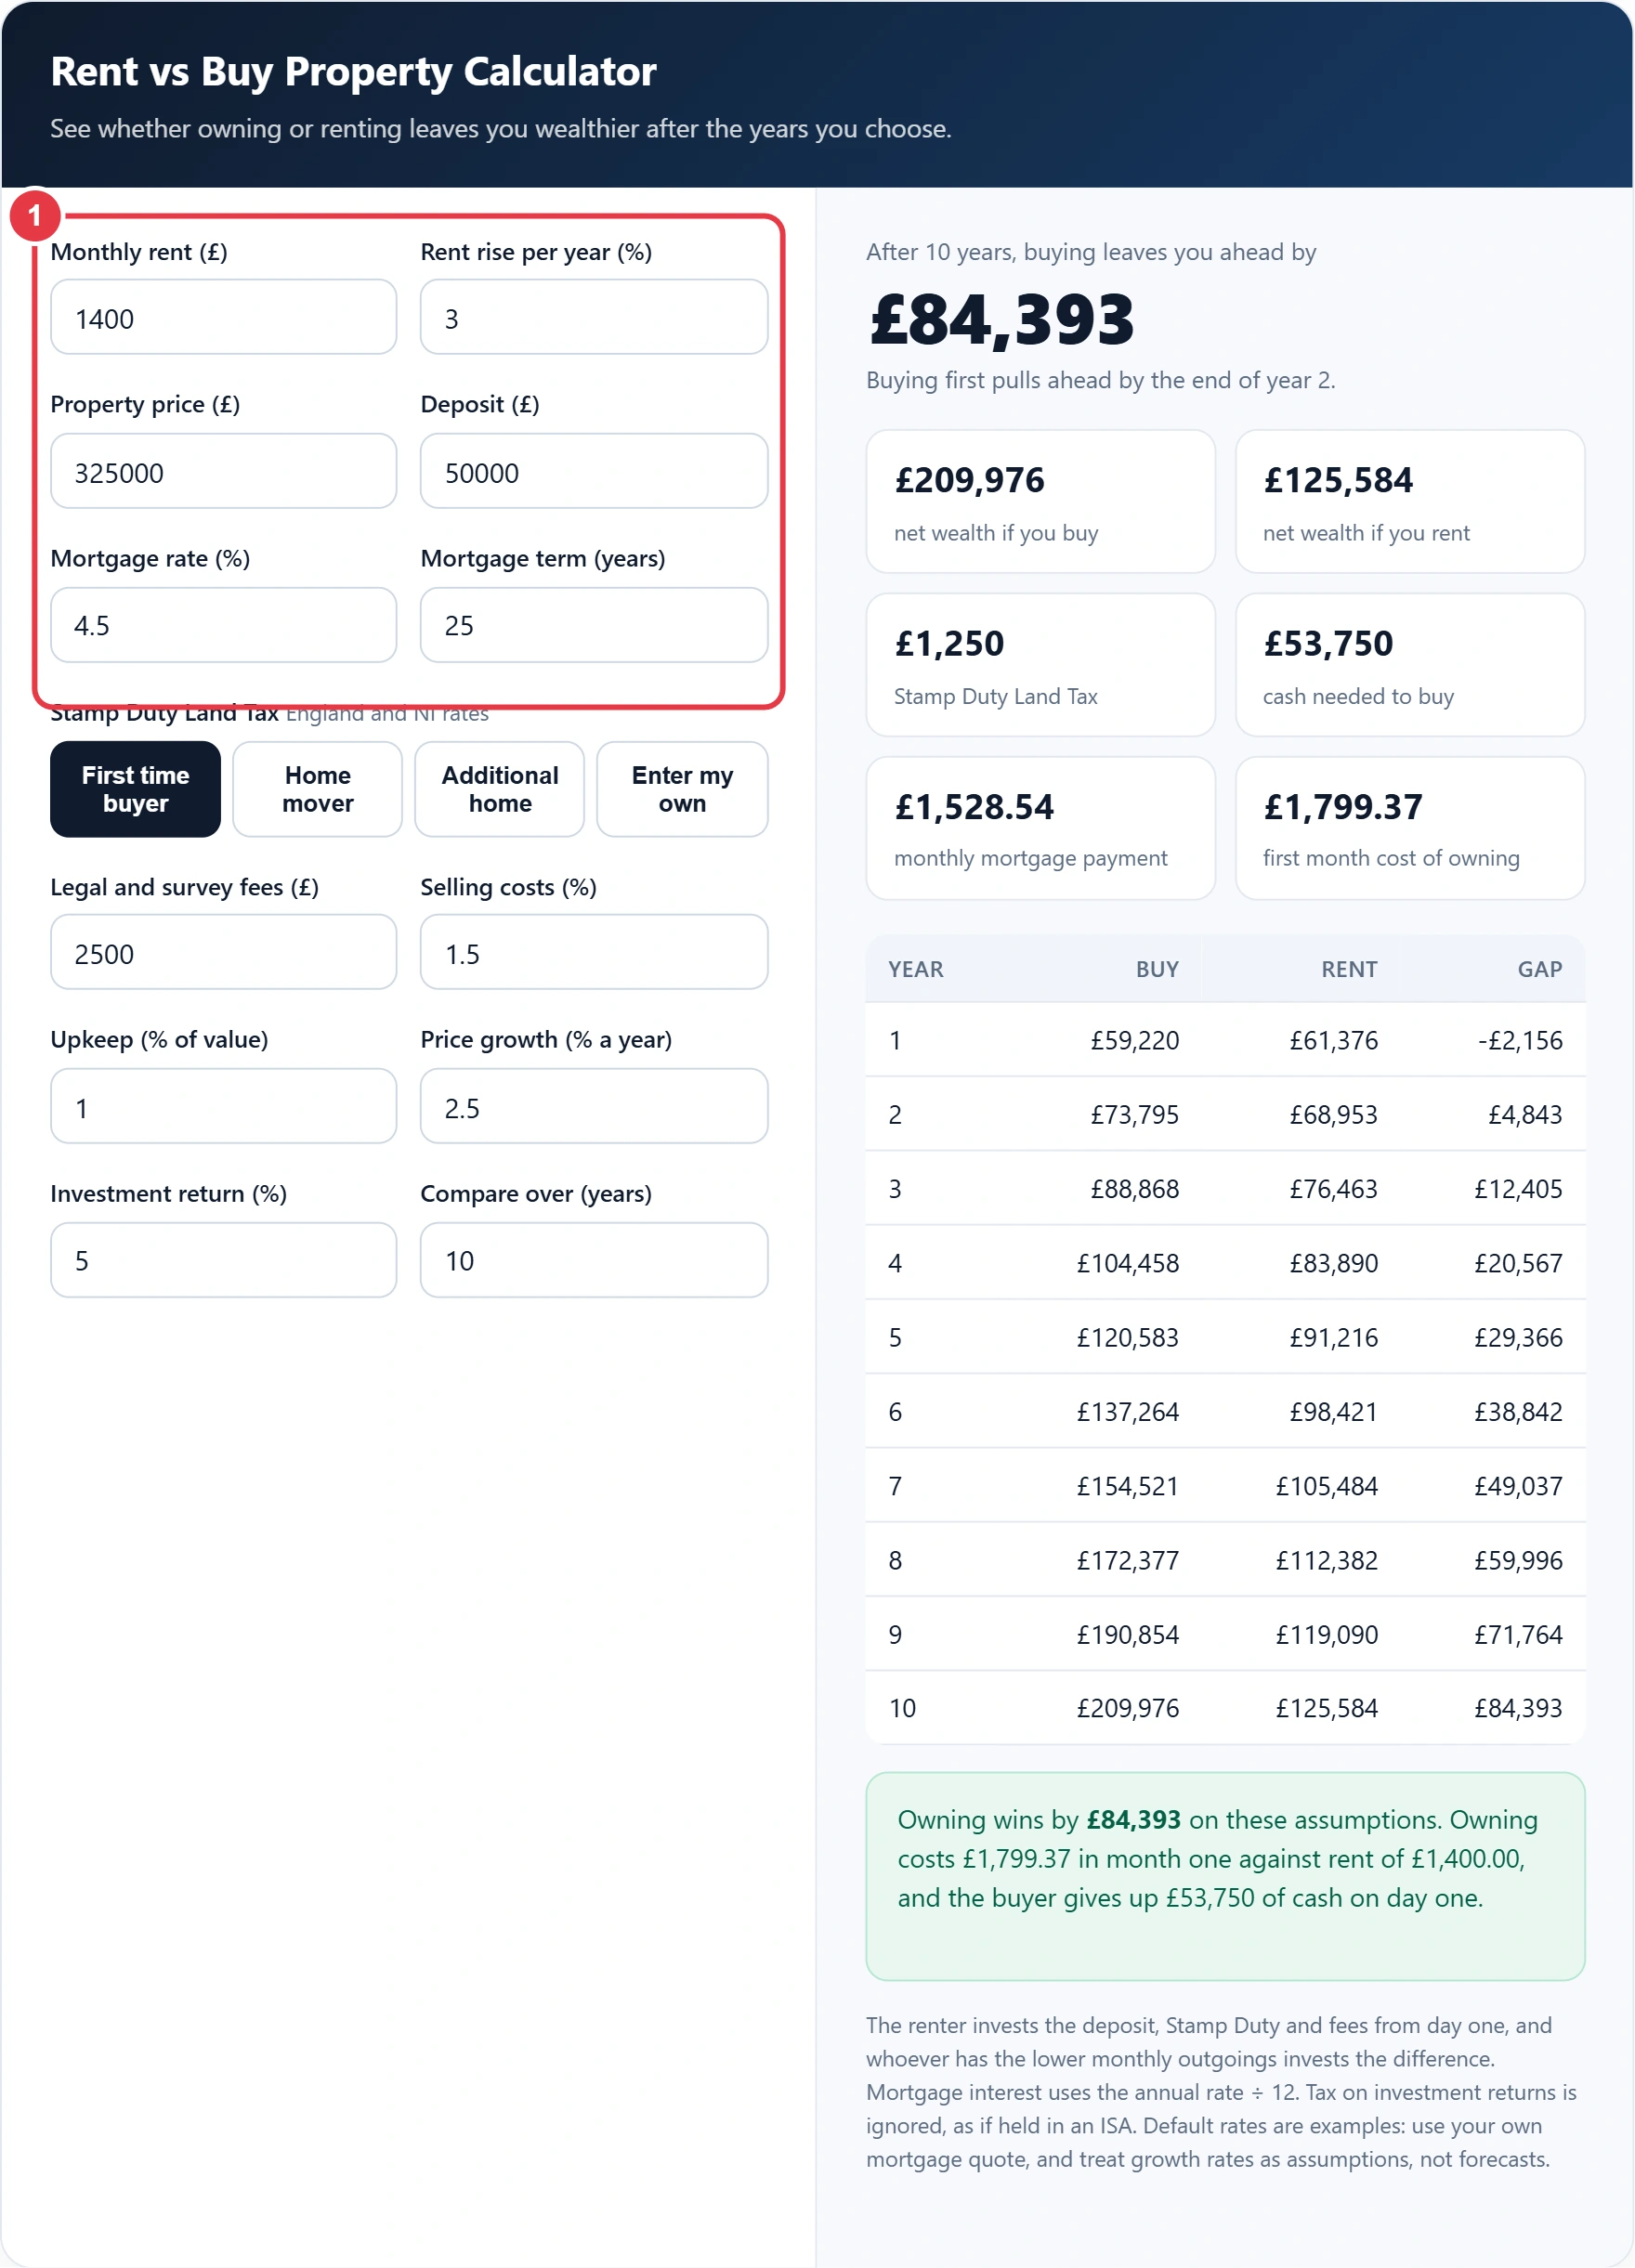
Step 1: Enter Rent, Price and Mortgage
Add your rent and expected yearly rise, then the asking price, your deposit and a mortgage rate from a real quote. The default rate is only an example.
Step 2: Choose Your Stamp Duty Position
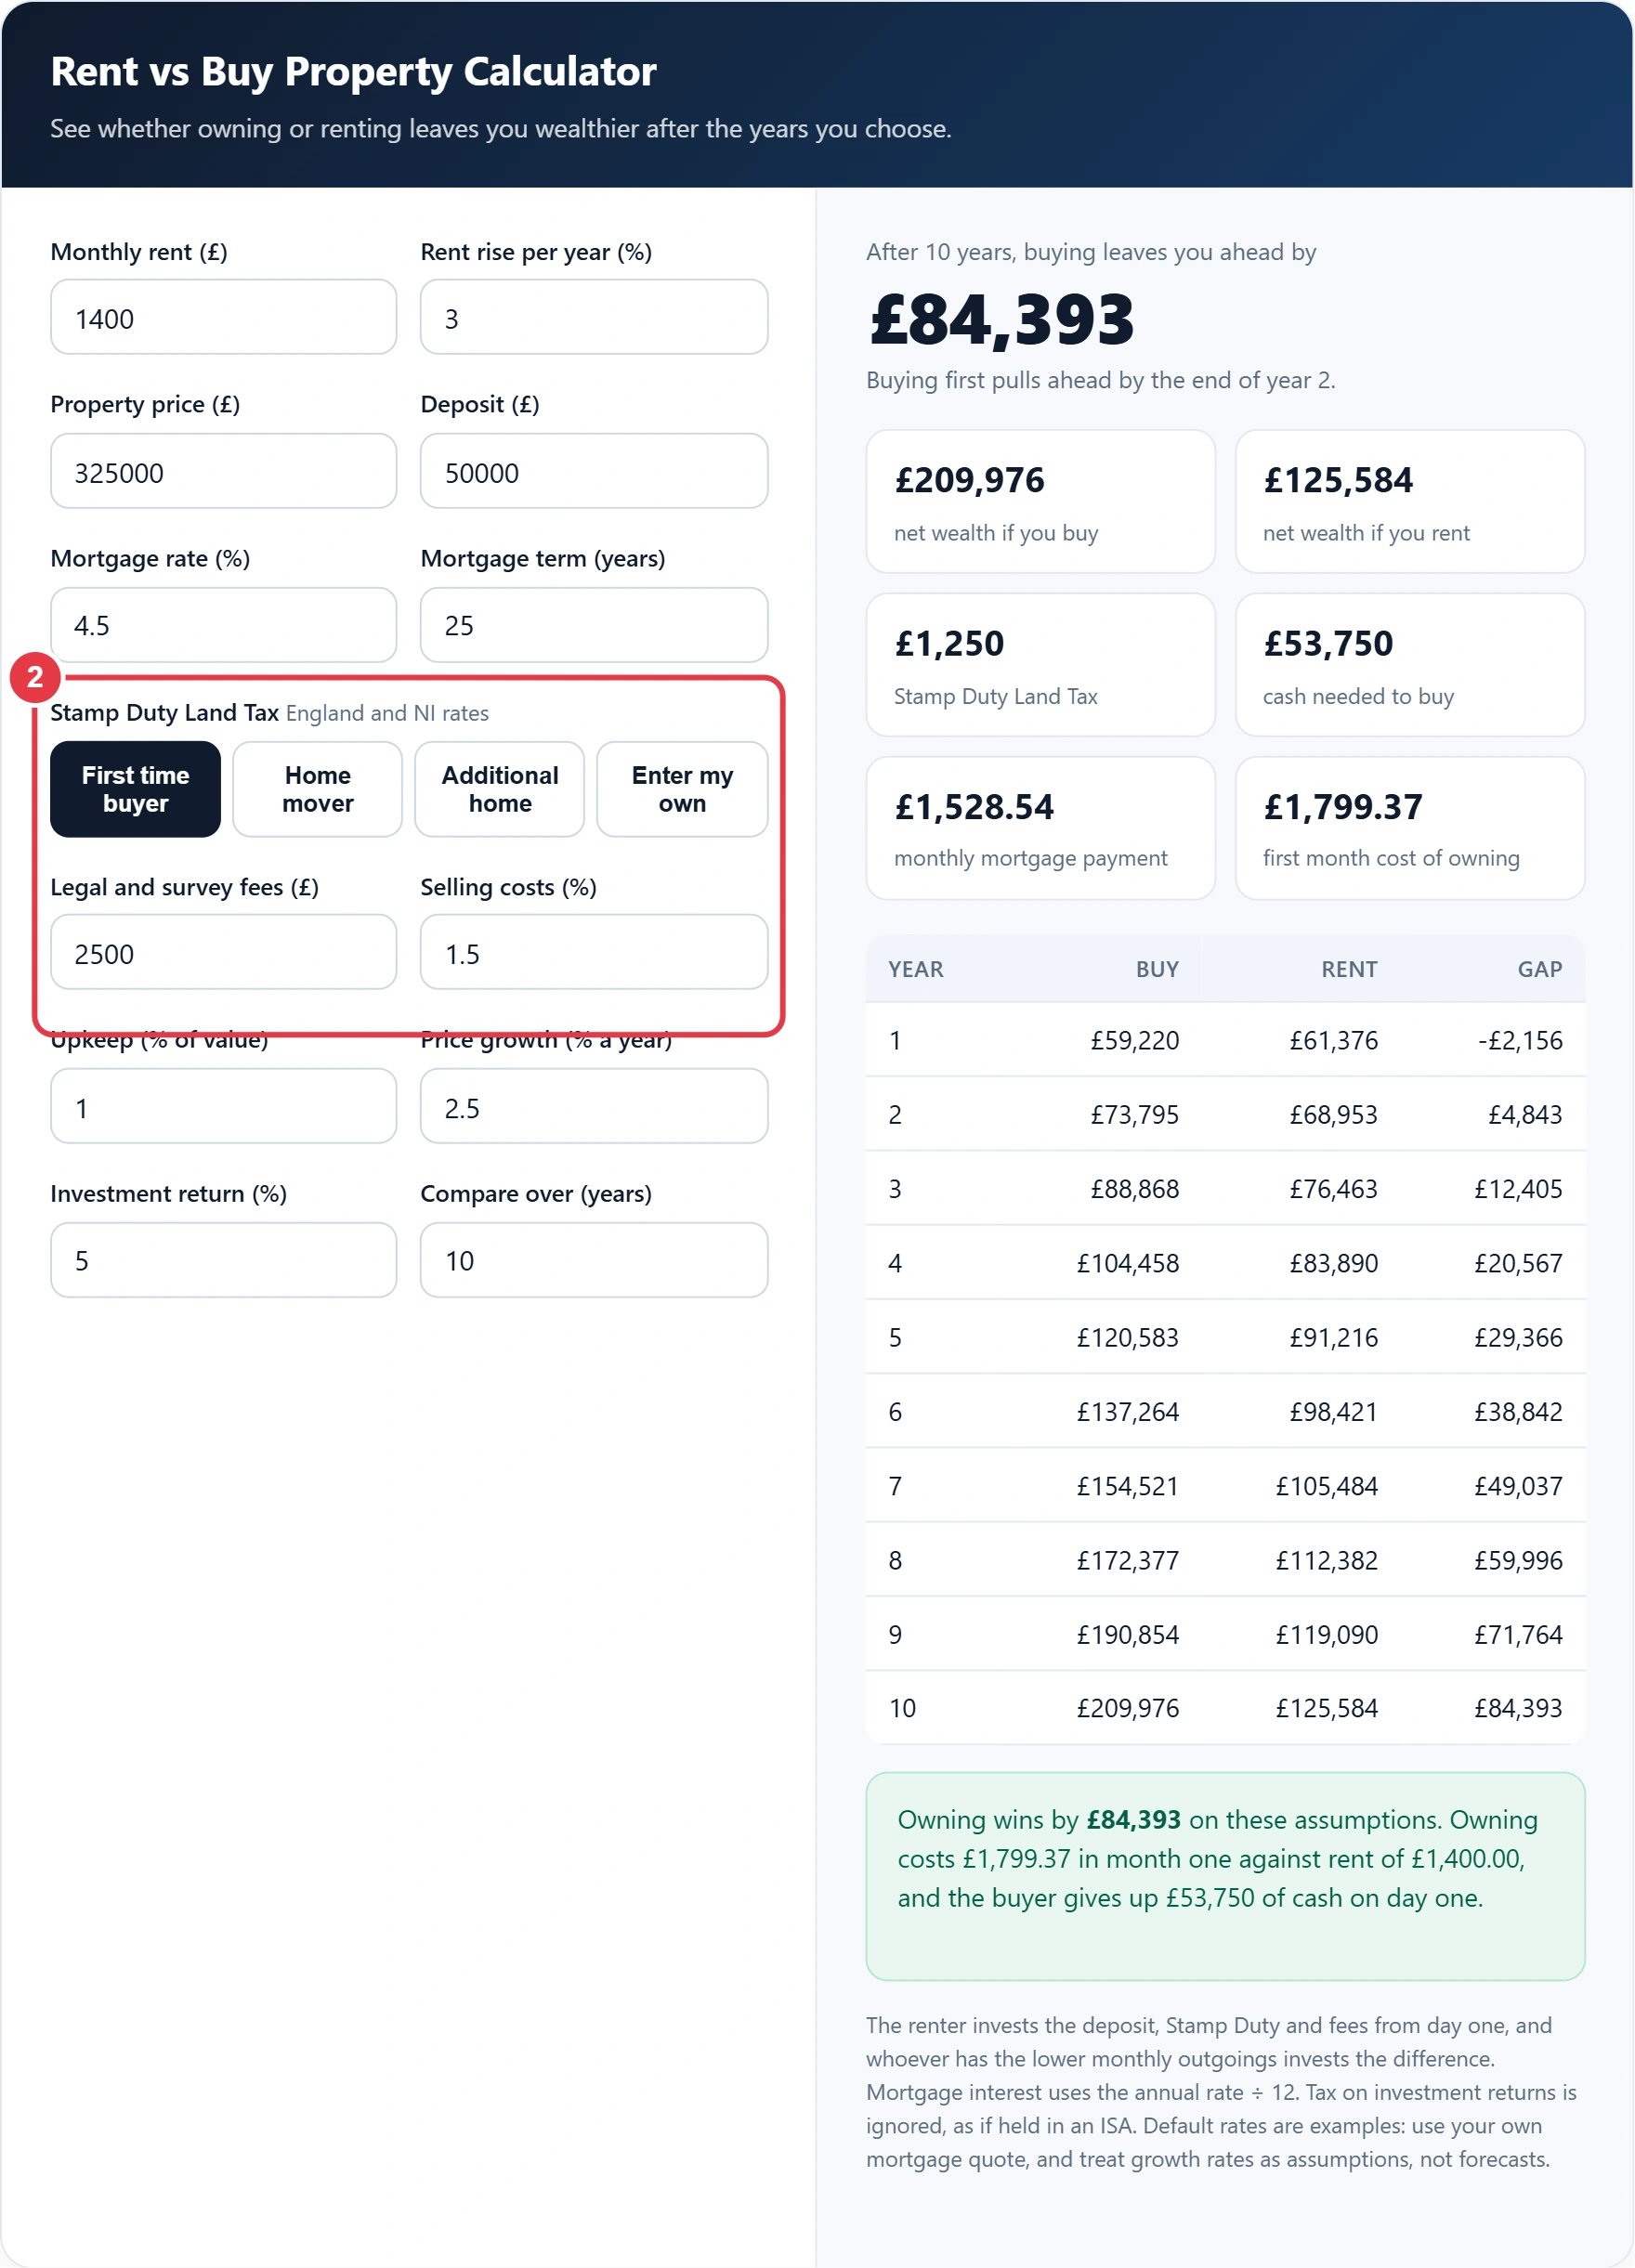
First time buyers pay nothing up to £300,000 and 5% from £300,001 to £500,000, with no relief above £500,000. Home movers pay 0%, 2%, 5%, 10% and 12% across the standard bands, and an additional home adds 5%. Buying in Scotland or Wales? Pick Enter my own and type your LBTT or LTT bill.
Step 3: Set Growth Rates and Years
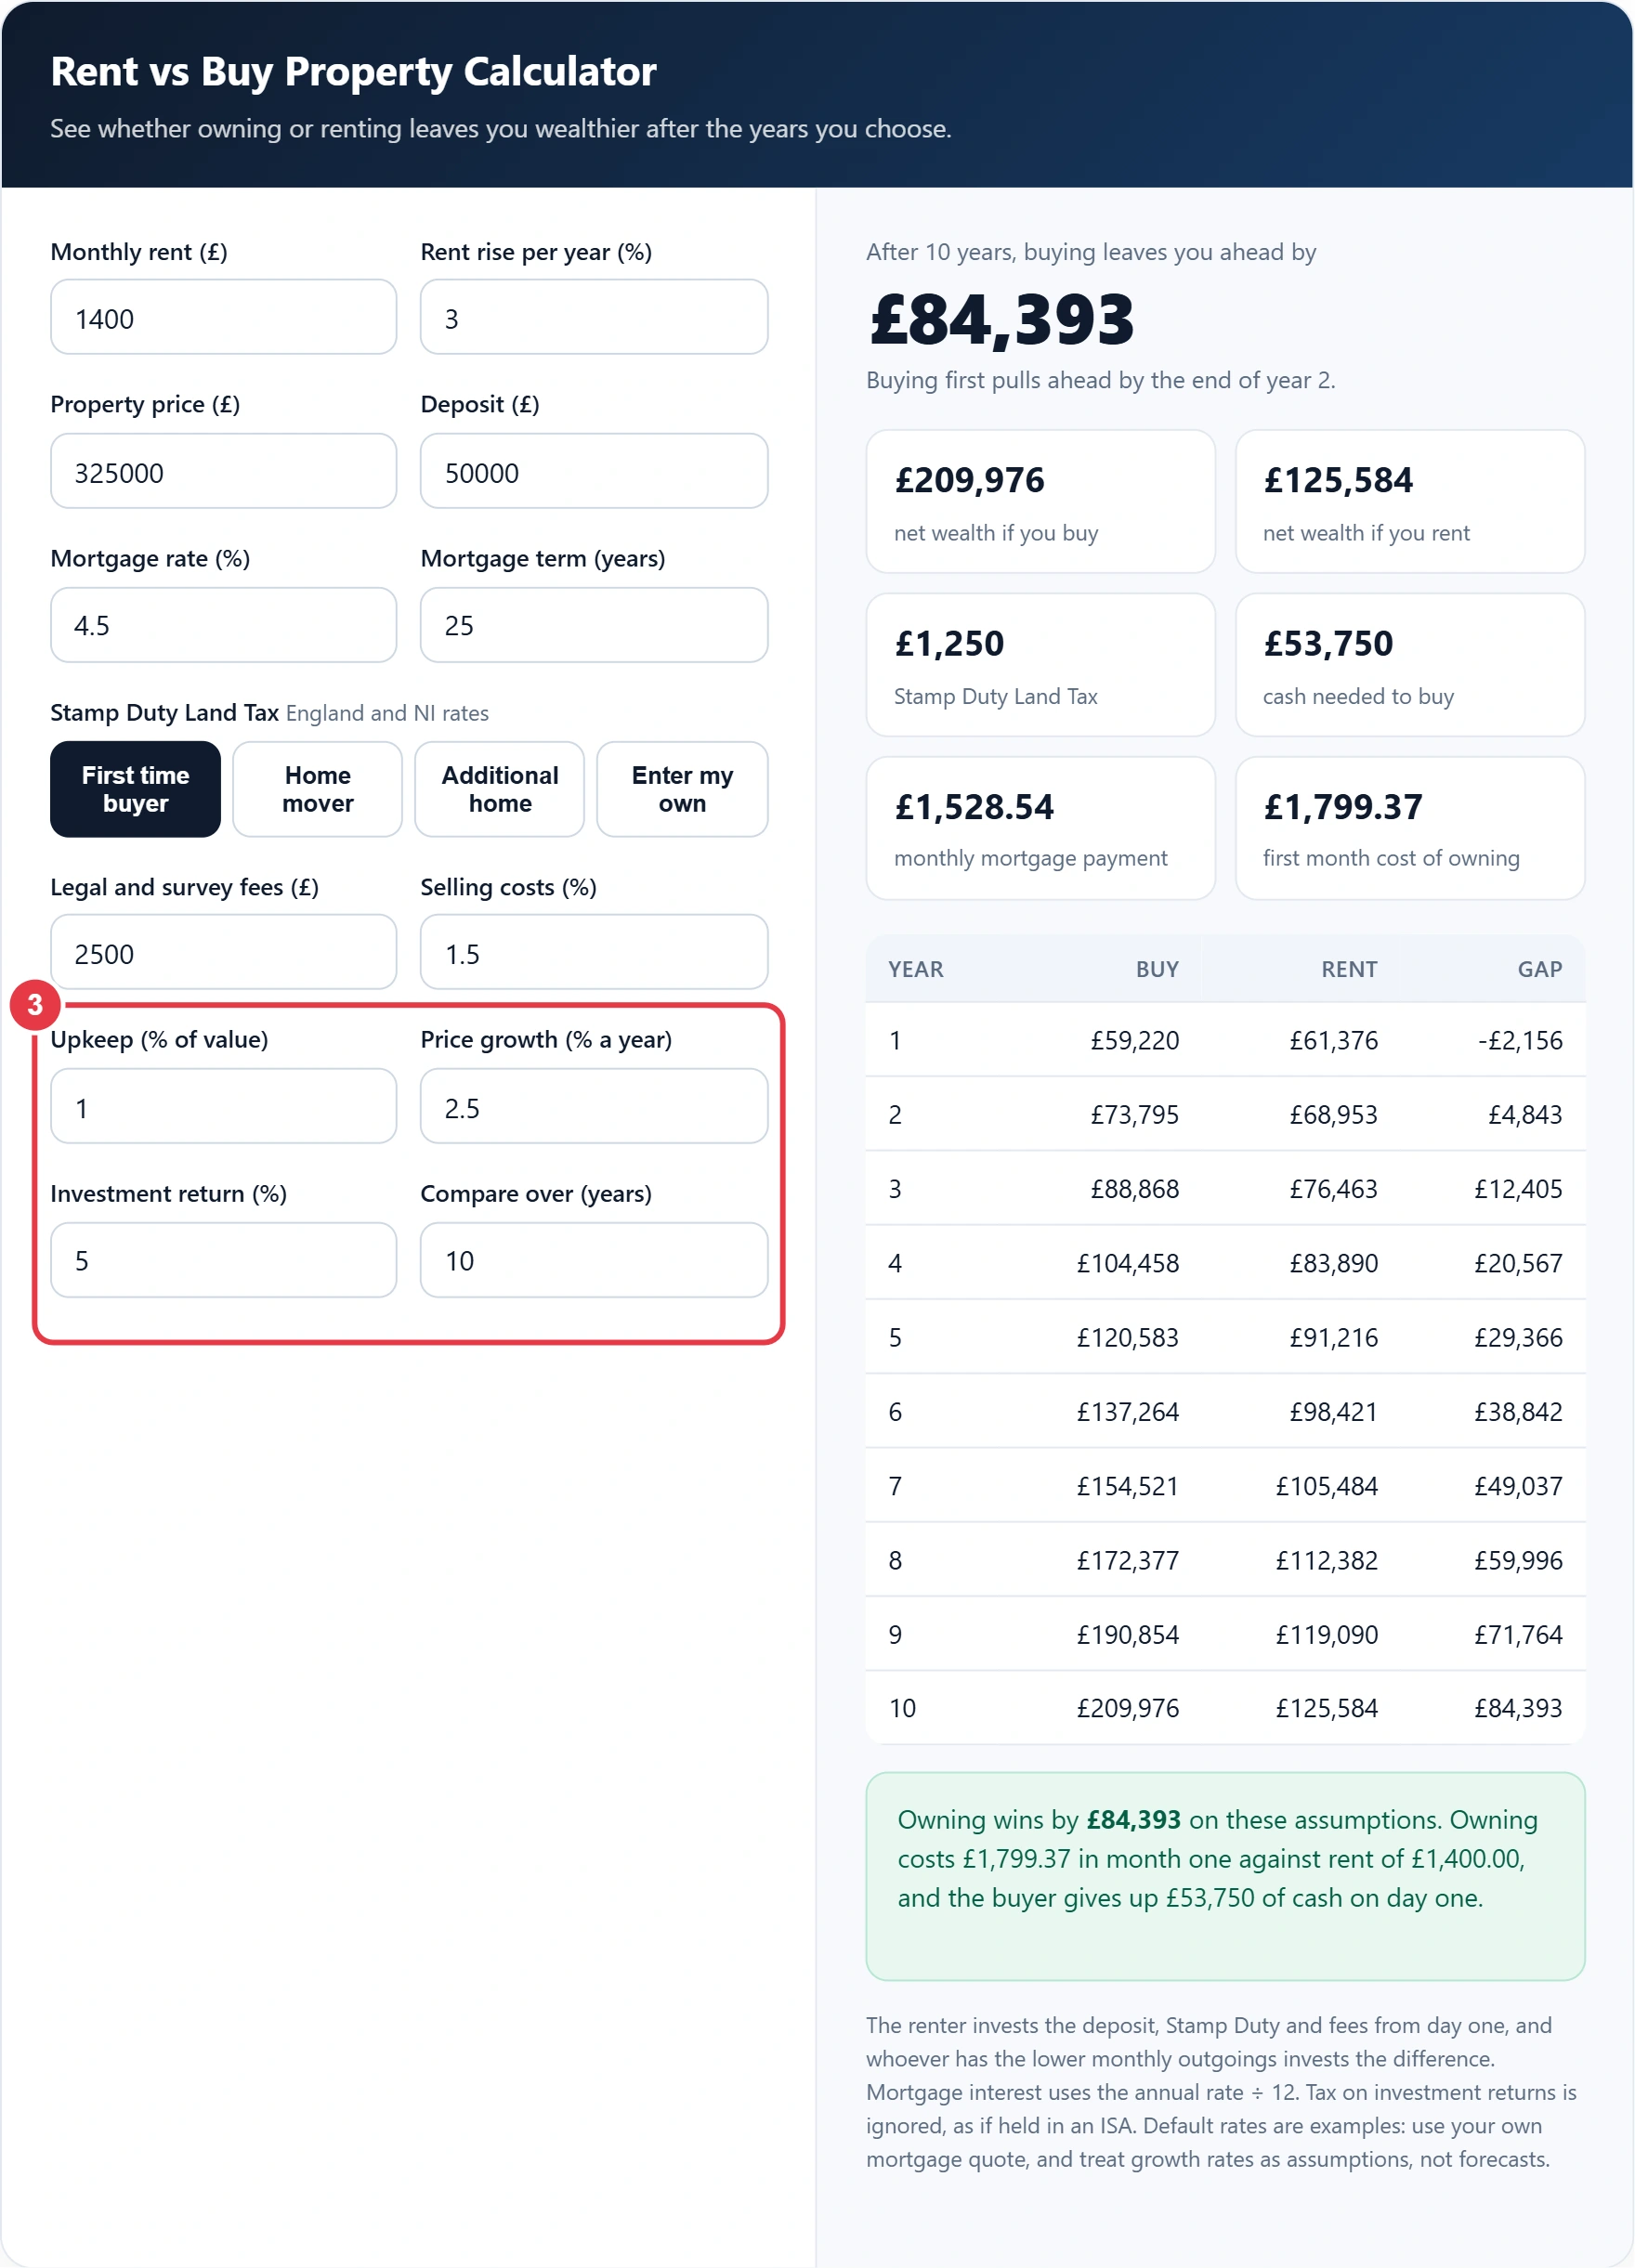
Upkeep of 1% of the home's value a year covers repairs, insurance and an eventual new boiler. House price growth and investment return are your own assumptions, and the compound interest calculator is handy for testing what a given return does to a lump sum over the same period.
Step 4: Read the Net Wealth Gap
The headline shows which option leaves you ahead and by how much, plus the year buying first pulls in front. The yearly table shows both positions, and the net worth calculator folds the result into your wider finances.
Is It Cheaper to Rent or Buy in the UK?
Buying usually wins if you stay put for five years or more and prices rise at least modestly, while renting often wins if you move within about three years or prices stay flat. Take Hannah, a first time buyer renting in Bristol for £1,400 a month. She eyes a £325,000 flat with a £50,000 deposit at 4.5% over 25 years, pays £1,250 Stamp Duty and £2,500 in fees, and assumes 2.5% house price growth against a 5% investment return.
| Hannah's scenario | Result |
|---|---|
| Default assumptions, 10 years | Buying ahead by £84,393 |
| Mortgage at 5.5%, 10 years | Buying ahead by £52,795 |
| Flat house prices, 10 years | Roughly equal (renting ahead by £177) |
| Flat house prices, 7% returns, 10 years | Renting ahead by £23,152 |
| Flat house prices, moves after 3 years | Renting ahead by £11,832 |
House price growth drives the answer more than any other input, so check what is happening locally. The ONS private rent and house prices bulletin recorded average UK rents rising 3.8% in the year to August 2026 and house prices 1.4% in the year to July 2026, so test a low growth case too. After you buy, the mortgage overpayment calculator shows how extra monthly payments build equity faster and cut total interest.
Rent vs Buy Property Calculator Terms Explained
These housing finance terms explain the assumptions inside the rent vs buy property calculator, helping you compare owning and renting on a fair like-for-like basis.
- Stamp Duty Land Tax
- A tax paid by buyers of property or land in England and Northern Ireland, charged in bands on successive portions of the price. First time buyers, home movers and buyers of additional homes each face different rates and thresholds.
- Opportunity cost
- The return given up by choosing one use of money over another. In this comparison it is the growth that a deposit, Stamp Duty and fees could have earned if they had been invested instead of spent on buying a home.
- Home equity
- The share of a property's value the owner holds outright, equal to its market value minus the outstanding mortgage. It grows as capital is repaid and as prices rise, and forms the buyer's main source of wealth in the comparison.
- Repayment mortgage
- A home loan where each monthly payment covers interest and also repays part of the capital, so the balance reaches zero by the end of the term. Early payments are mostly interest, with the capital share rising steadily over time.
- Land and Buildings Transaction Tax
- The tax Scotland charges on property purchases in place of Stamp Duty Land Tax, with its own bands and rates. Wales uses a separate Land Transaction Tax, so buyers in either nation should enter their own tax figure.
</>Embed this calculator on your website
Add the free Rent vs Buy Calculator to your own site or blog. Copy the code below and paste it into an HTML block. It resizes itself and works on phones.
How we checked this tool: the Tools Veria Editorial Team built this tool by hand, checked it against the official rules or published standards where they apply, and tested it against worked examples. Results are estimates for planning, not personal financial or tax advice. Read our editorial policy and disclaimer, or report an error.
Frequently Asked Questions
How much Stamp Duty does a first time buyer pay in England?
A first time buyer in England or Northern Ireland pays no Stamp Duty Land Tax on the first £300,000 and 5% on the portion from £300,001 to £500,000. On a £325,000 home that is £1,250. Above £500,000 the relief is lost and standard rates apply.
How many years do I need to stay for buying to beat renting?
With moderate house price growth, buying often overtakes renting within two to five years, because Stamp Duty, legal fees and selling costs take time to recoup. In Hannah's example, buying pulls ahead by the end of year two.
Does the calculator include the money my deposit could earn?
Yes. The renter is assumed to invest the full deposit, Stamp Duty and buying fees on day one at your chosen return, so the comparison counts the opportunity cost of tying up that cash in bricks and mortar.
Is paying off a mortgage the same as paying rent?
No. Only the interest part of a mortgage payment is a cost like rent. The capital part reduces your loan and becomes equity, which is why the calculator counts the home's value minus the remaining mortgage as wealth.
What upkeep percentage should I use for a UK home?
Around 1% of the property value a year is a common planning figure for repairs, buildings insurance and replacing items such as a boiler. Use 1.5% to 2% for older houses and include any leasehold service charge separately.
Does the calculator work for Scotland and Wales?
Yes, but enter your tax manually. Scotland uses Land and Buildings Transaction Tax and Wales uses Land Transaction Tax, which have different bands to Stamp Duty Land Tax, so choose Enter my own and type the bill.