Find your remaining tax-free cash allowance after protections, pre-2024 benefits and lump sums already taken.
Estimate using the HMRC Pensions Tax Manual: standard lump sum allowance £268,275 and lump sum and death benefit allowance £1,073,100; pre-April 2024 use deducted at 25% of the lifetime allowance previously-used amount unless you hold a transitional tax-free amount certificate. Assumes a defined contribution pot with 25% tax-free. Your provider confirms the real figures.
This lump sum allowance calculator is for UK pension savers nearing or past minimum pension age, and their advisers, who want to know how much tax-free cash they can still take in 2026/27. It applies the standard allowance or a protected one, deducts pension benefits taken before 6 April 2024 using the HMRC transitional rules or a certificate, and shows the tax on anything over the limit. Figures checked October 2026.
Quick answer: Most people can take 25% of each pension tax free, up to a lifetime total of £268,275. If you drew benefits before April 2024, a lump sum allowance calculator first deducts 25% of the lifetime allowance you used then: someone who used 20% has £214,620 left, not £268,275.
In This Guide
What Is the Lump Sum Allowance?
The lump sum allowance (LSA) is the lifetime cap on tax-free lump sums you can take from all your registered pensions, set at £268,275 from 6 April 2024 when the lifetime allowance was abolished. It counts pension commencement lump sums, the tax-free quarter of uncrystallised funds pension lump sums and stand-alone lump sums.
The formula in plain words: start with your allowance, which is £268,275 or a protected figure. Take off 25% of the lifetime allowance you had used by 5 April 2024, or the amount on a transitional tax-free amount certificate instead. Take off every tax-free lump sum since 6 April 2024. What is left is the most you can still take tax free. A second, wider limit, the lump sum and death benefit allowance of £1,073,100, covers serious ill health lump sums and certain death benefits as well.
How to Use the Lump Sum Allowance Calculator
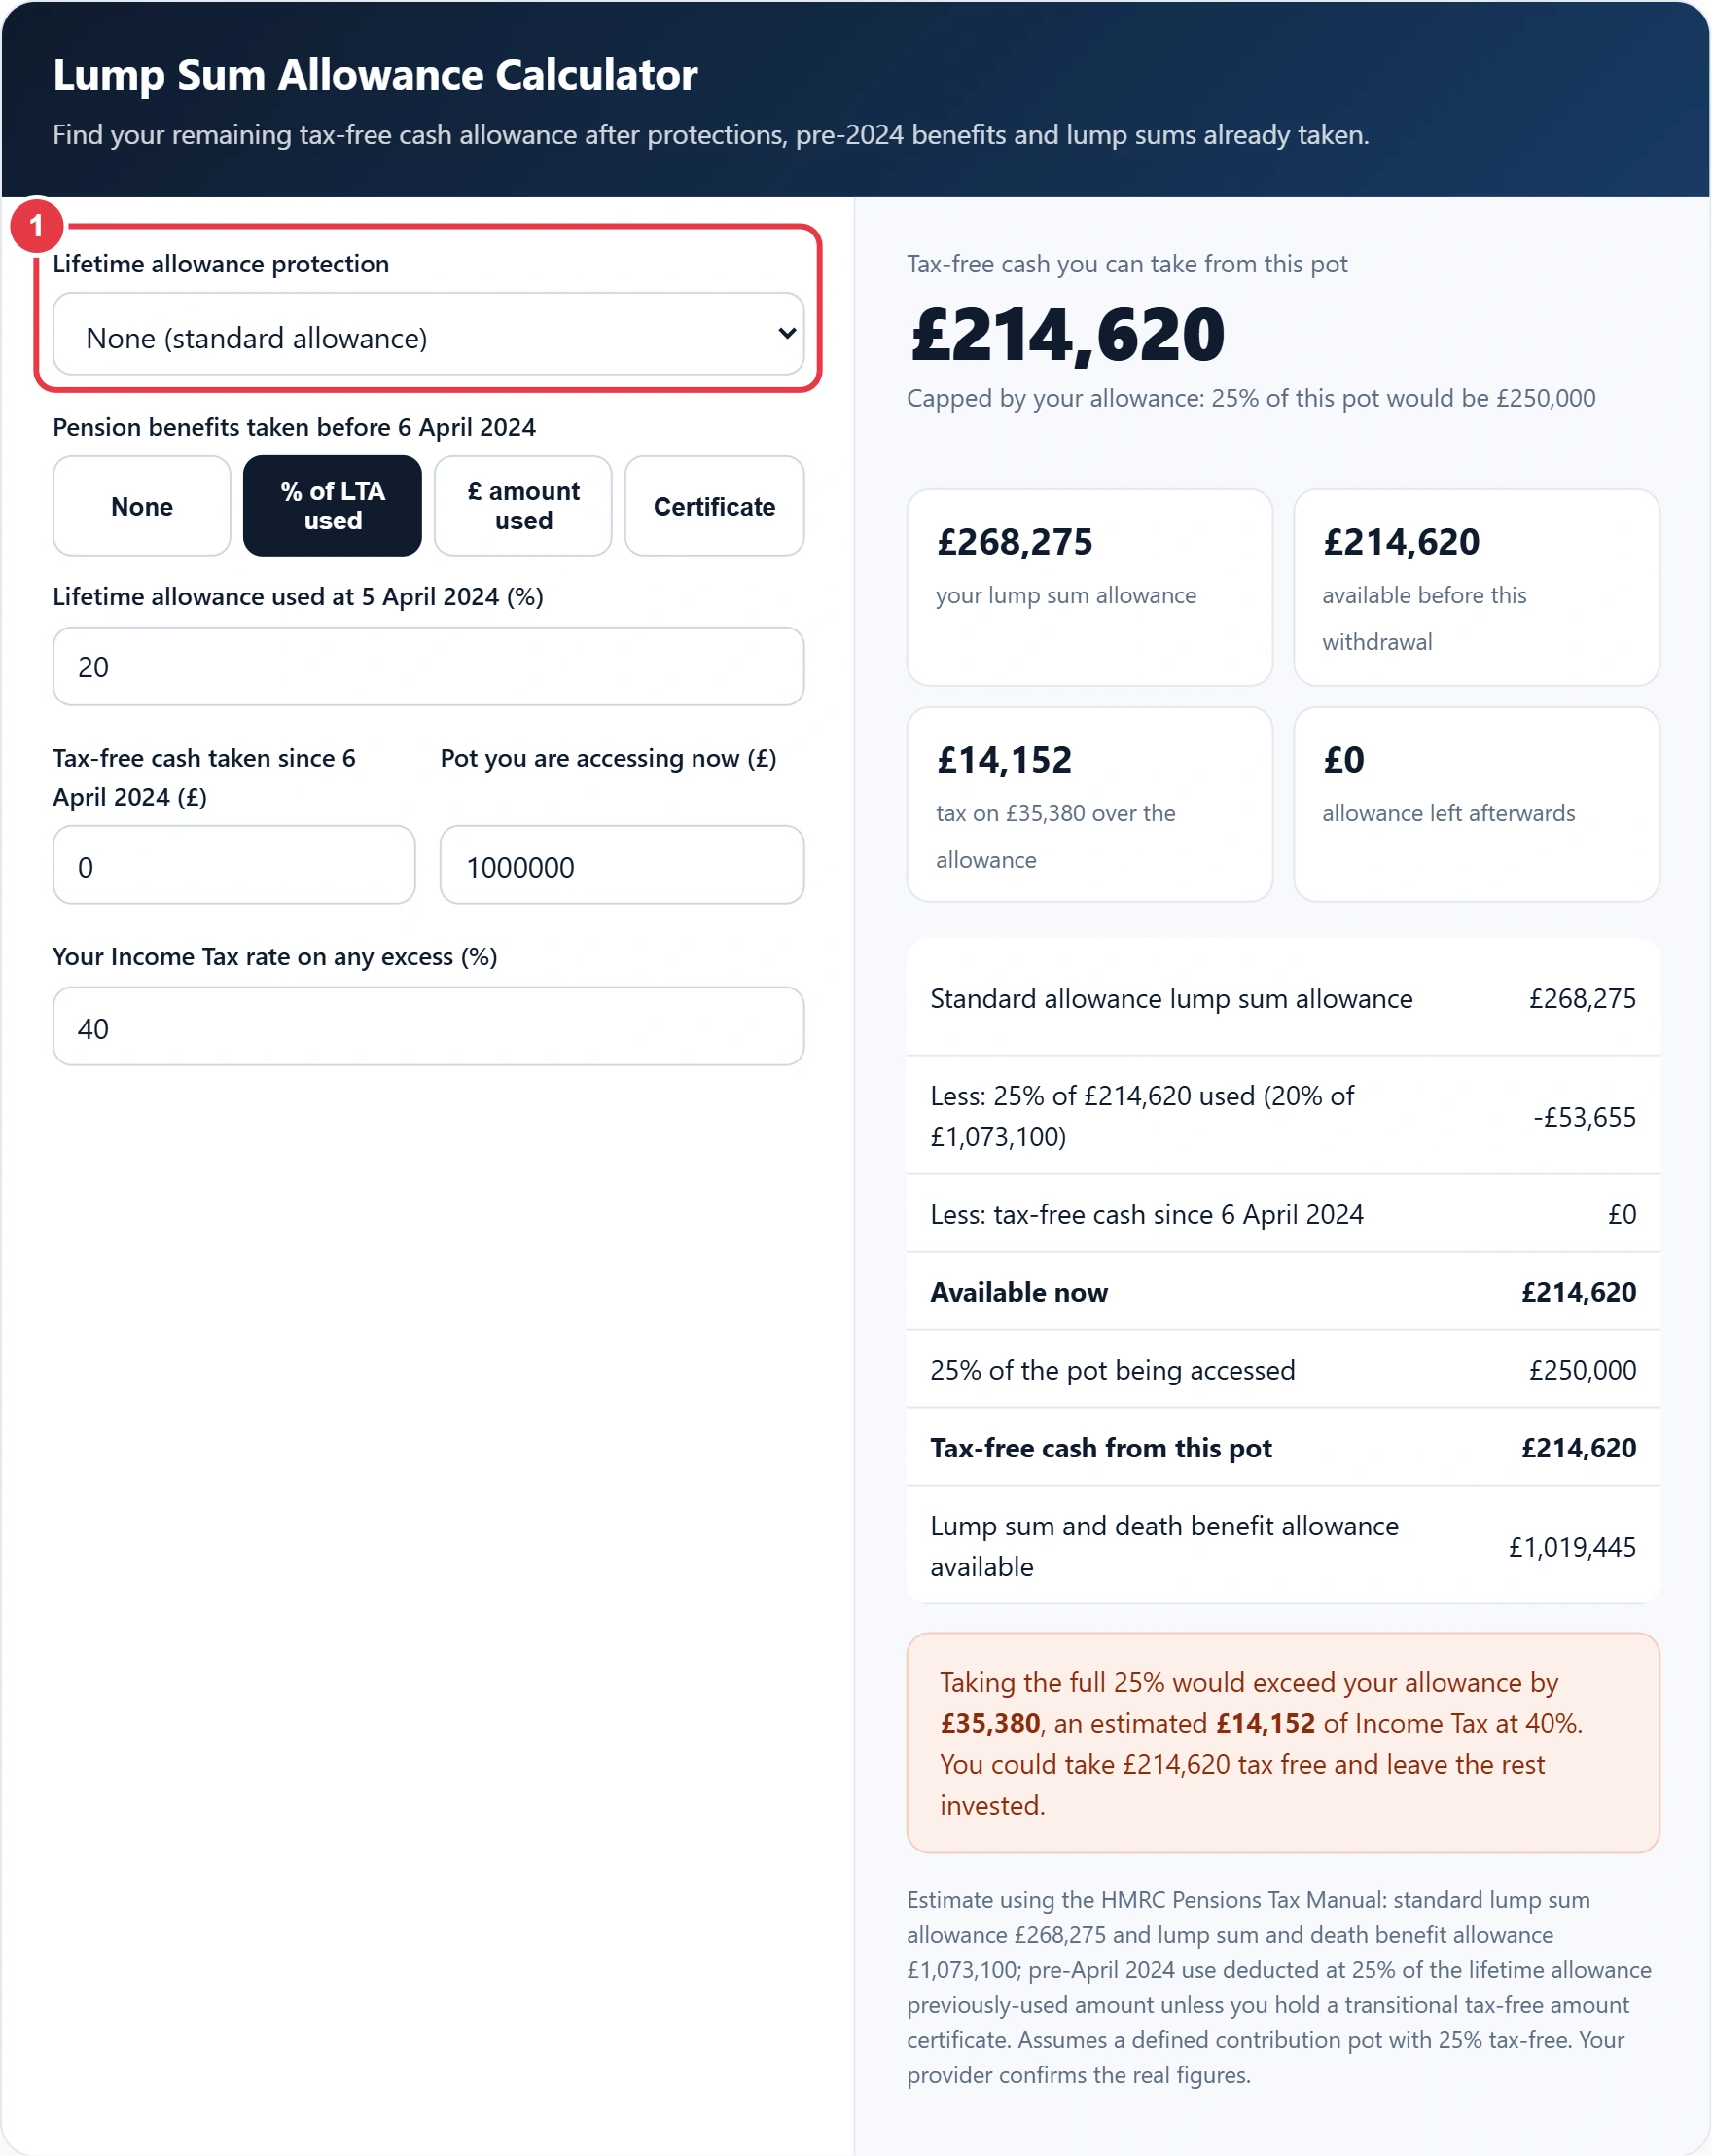
Step 1: Choose Any Protection You Hold
Leave this on "None" unless HMRC issued you a lifetime allowance protection certificate. Fixed protection gives a fixed higher allowance. For individual protection 2014 or 2016, enter the relevant amount from your certificate, because your allowance is 25% of it, capped. Holders of lump sum protection under primary or enhanced protection can type their own figure.
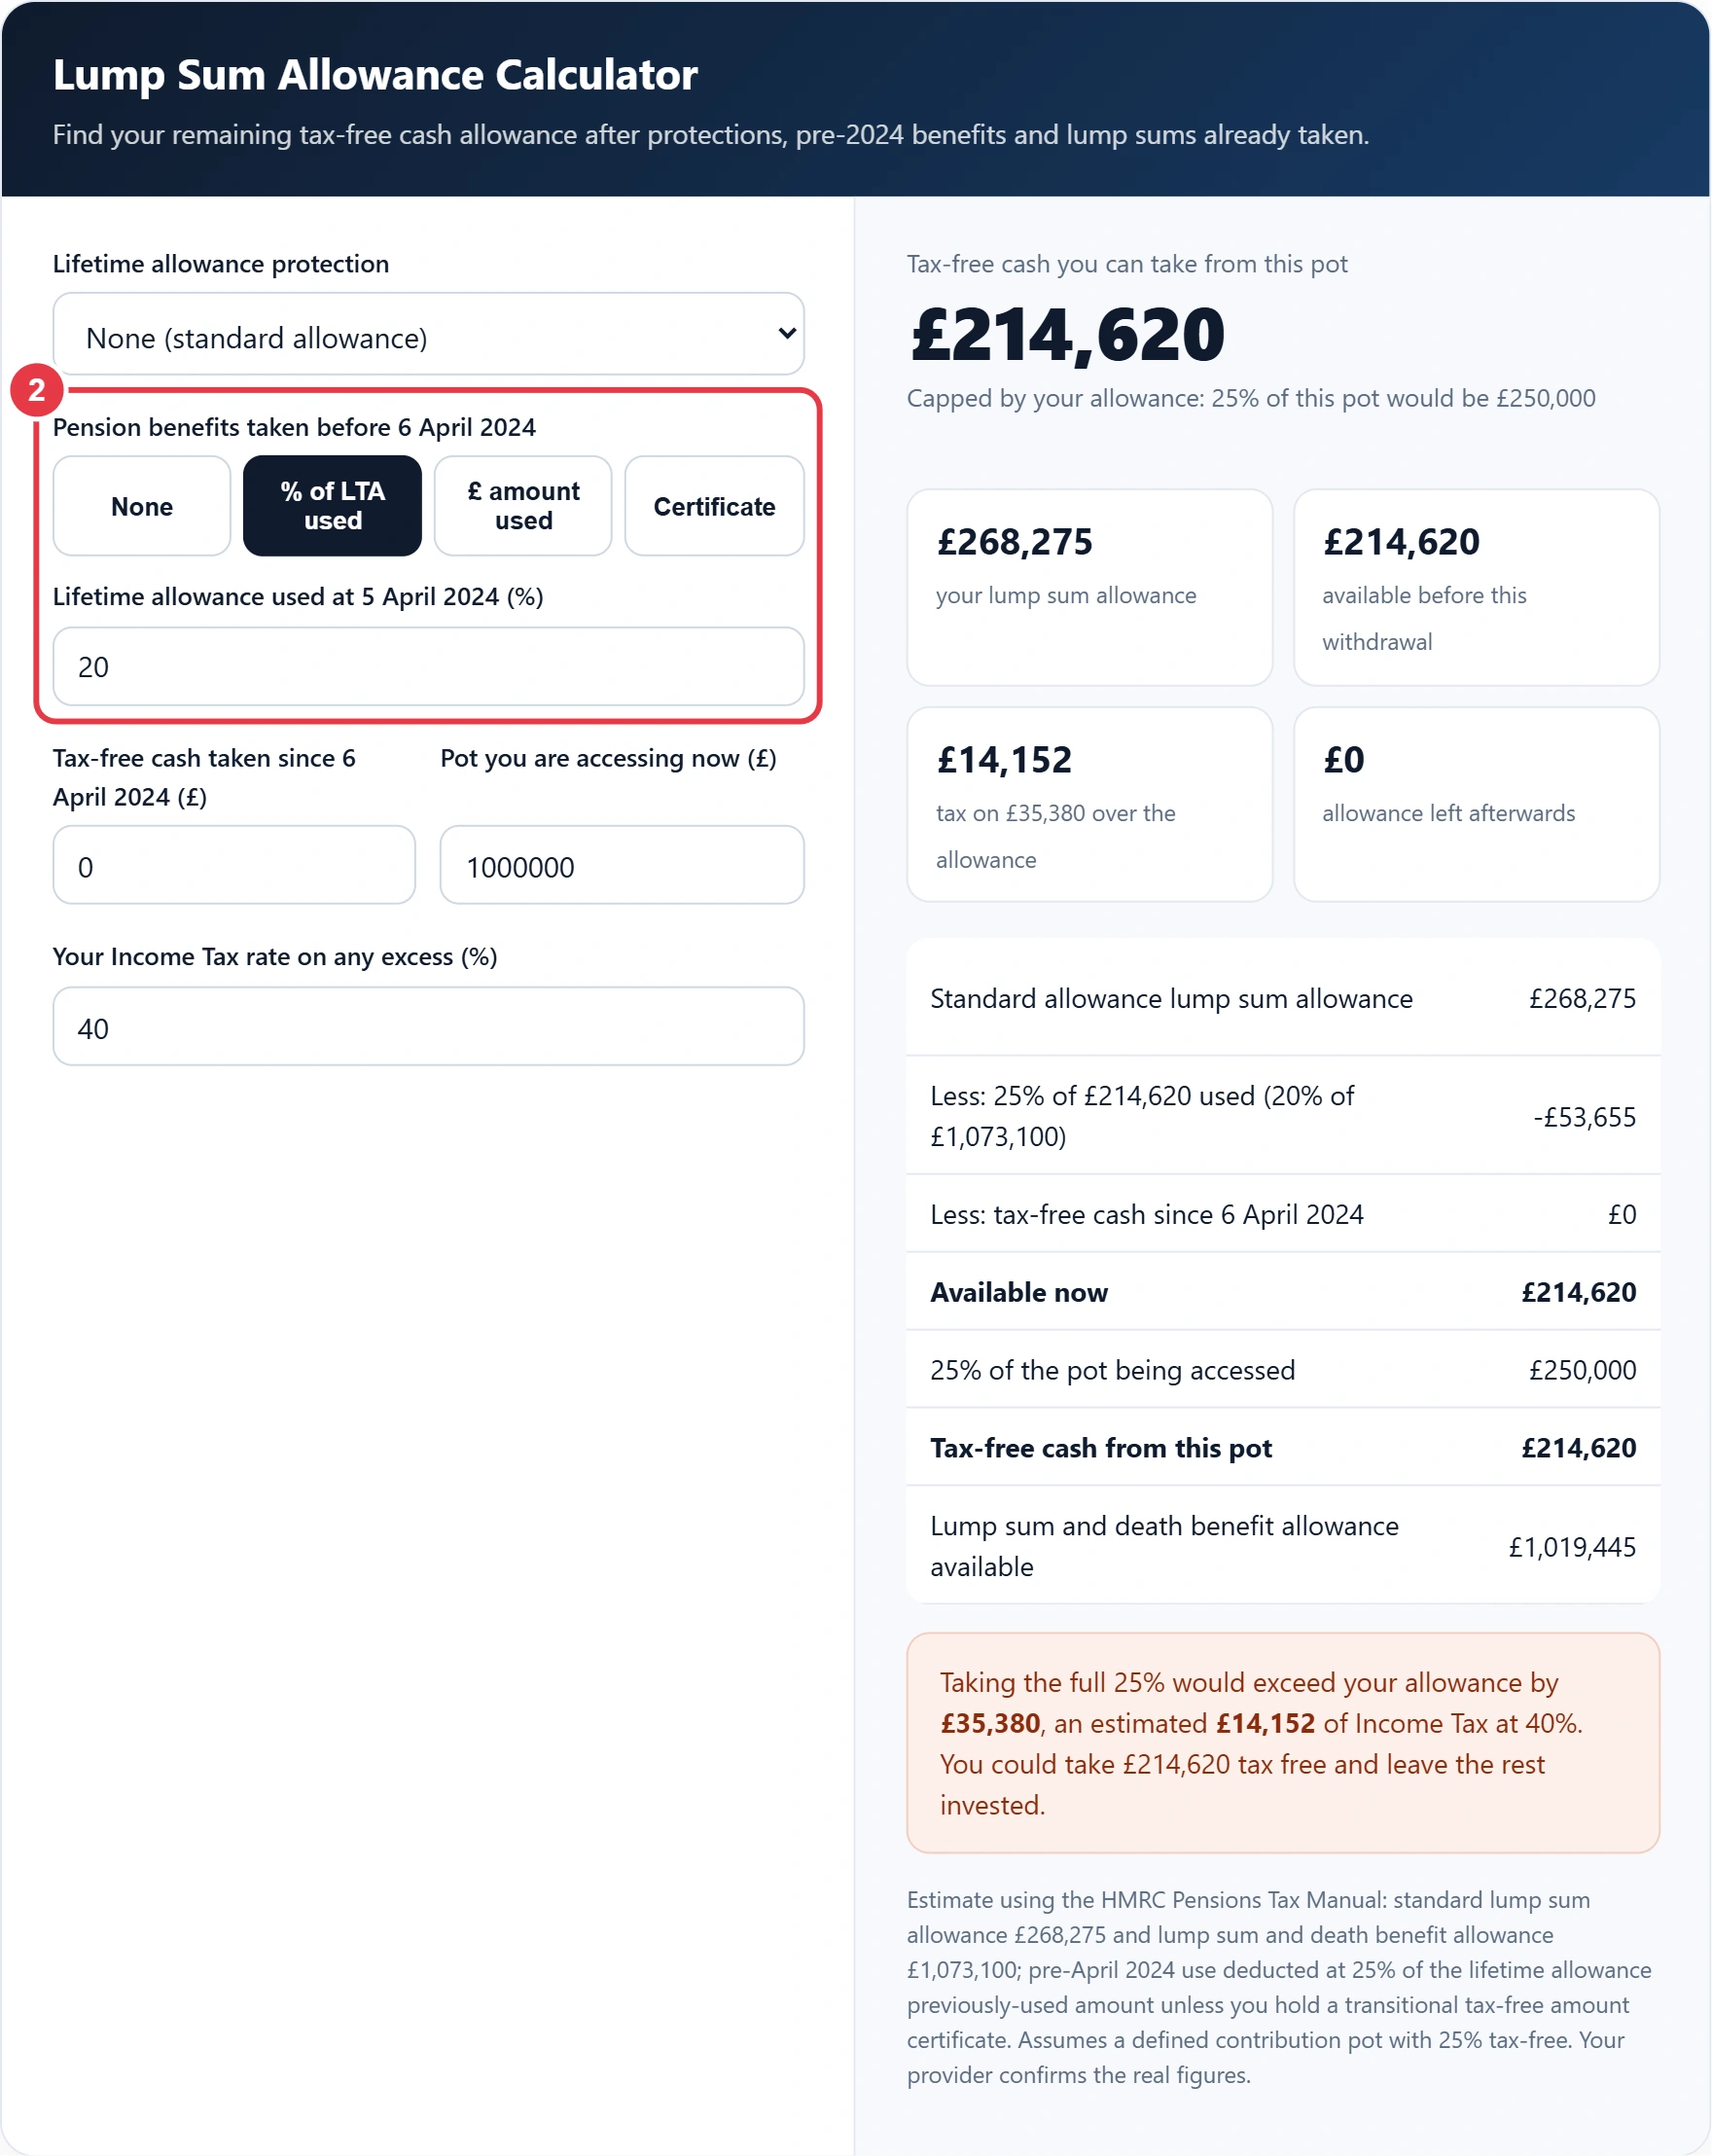
Step 2: Enter Benefits Taken Before April 2024
If you started drawing any pension before 6 April 2024, enter the lifetime allowance percentage used, which appears on retirement statements, or the pound amount your provider gives you. If you hold a transitional tax-free amount certificate, choose "Certificate" and enter its figure, which replaces the standard 25% deduction.
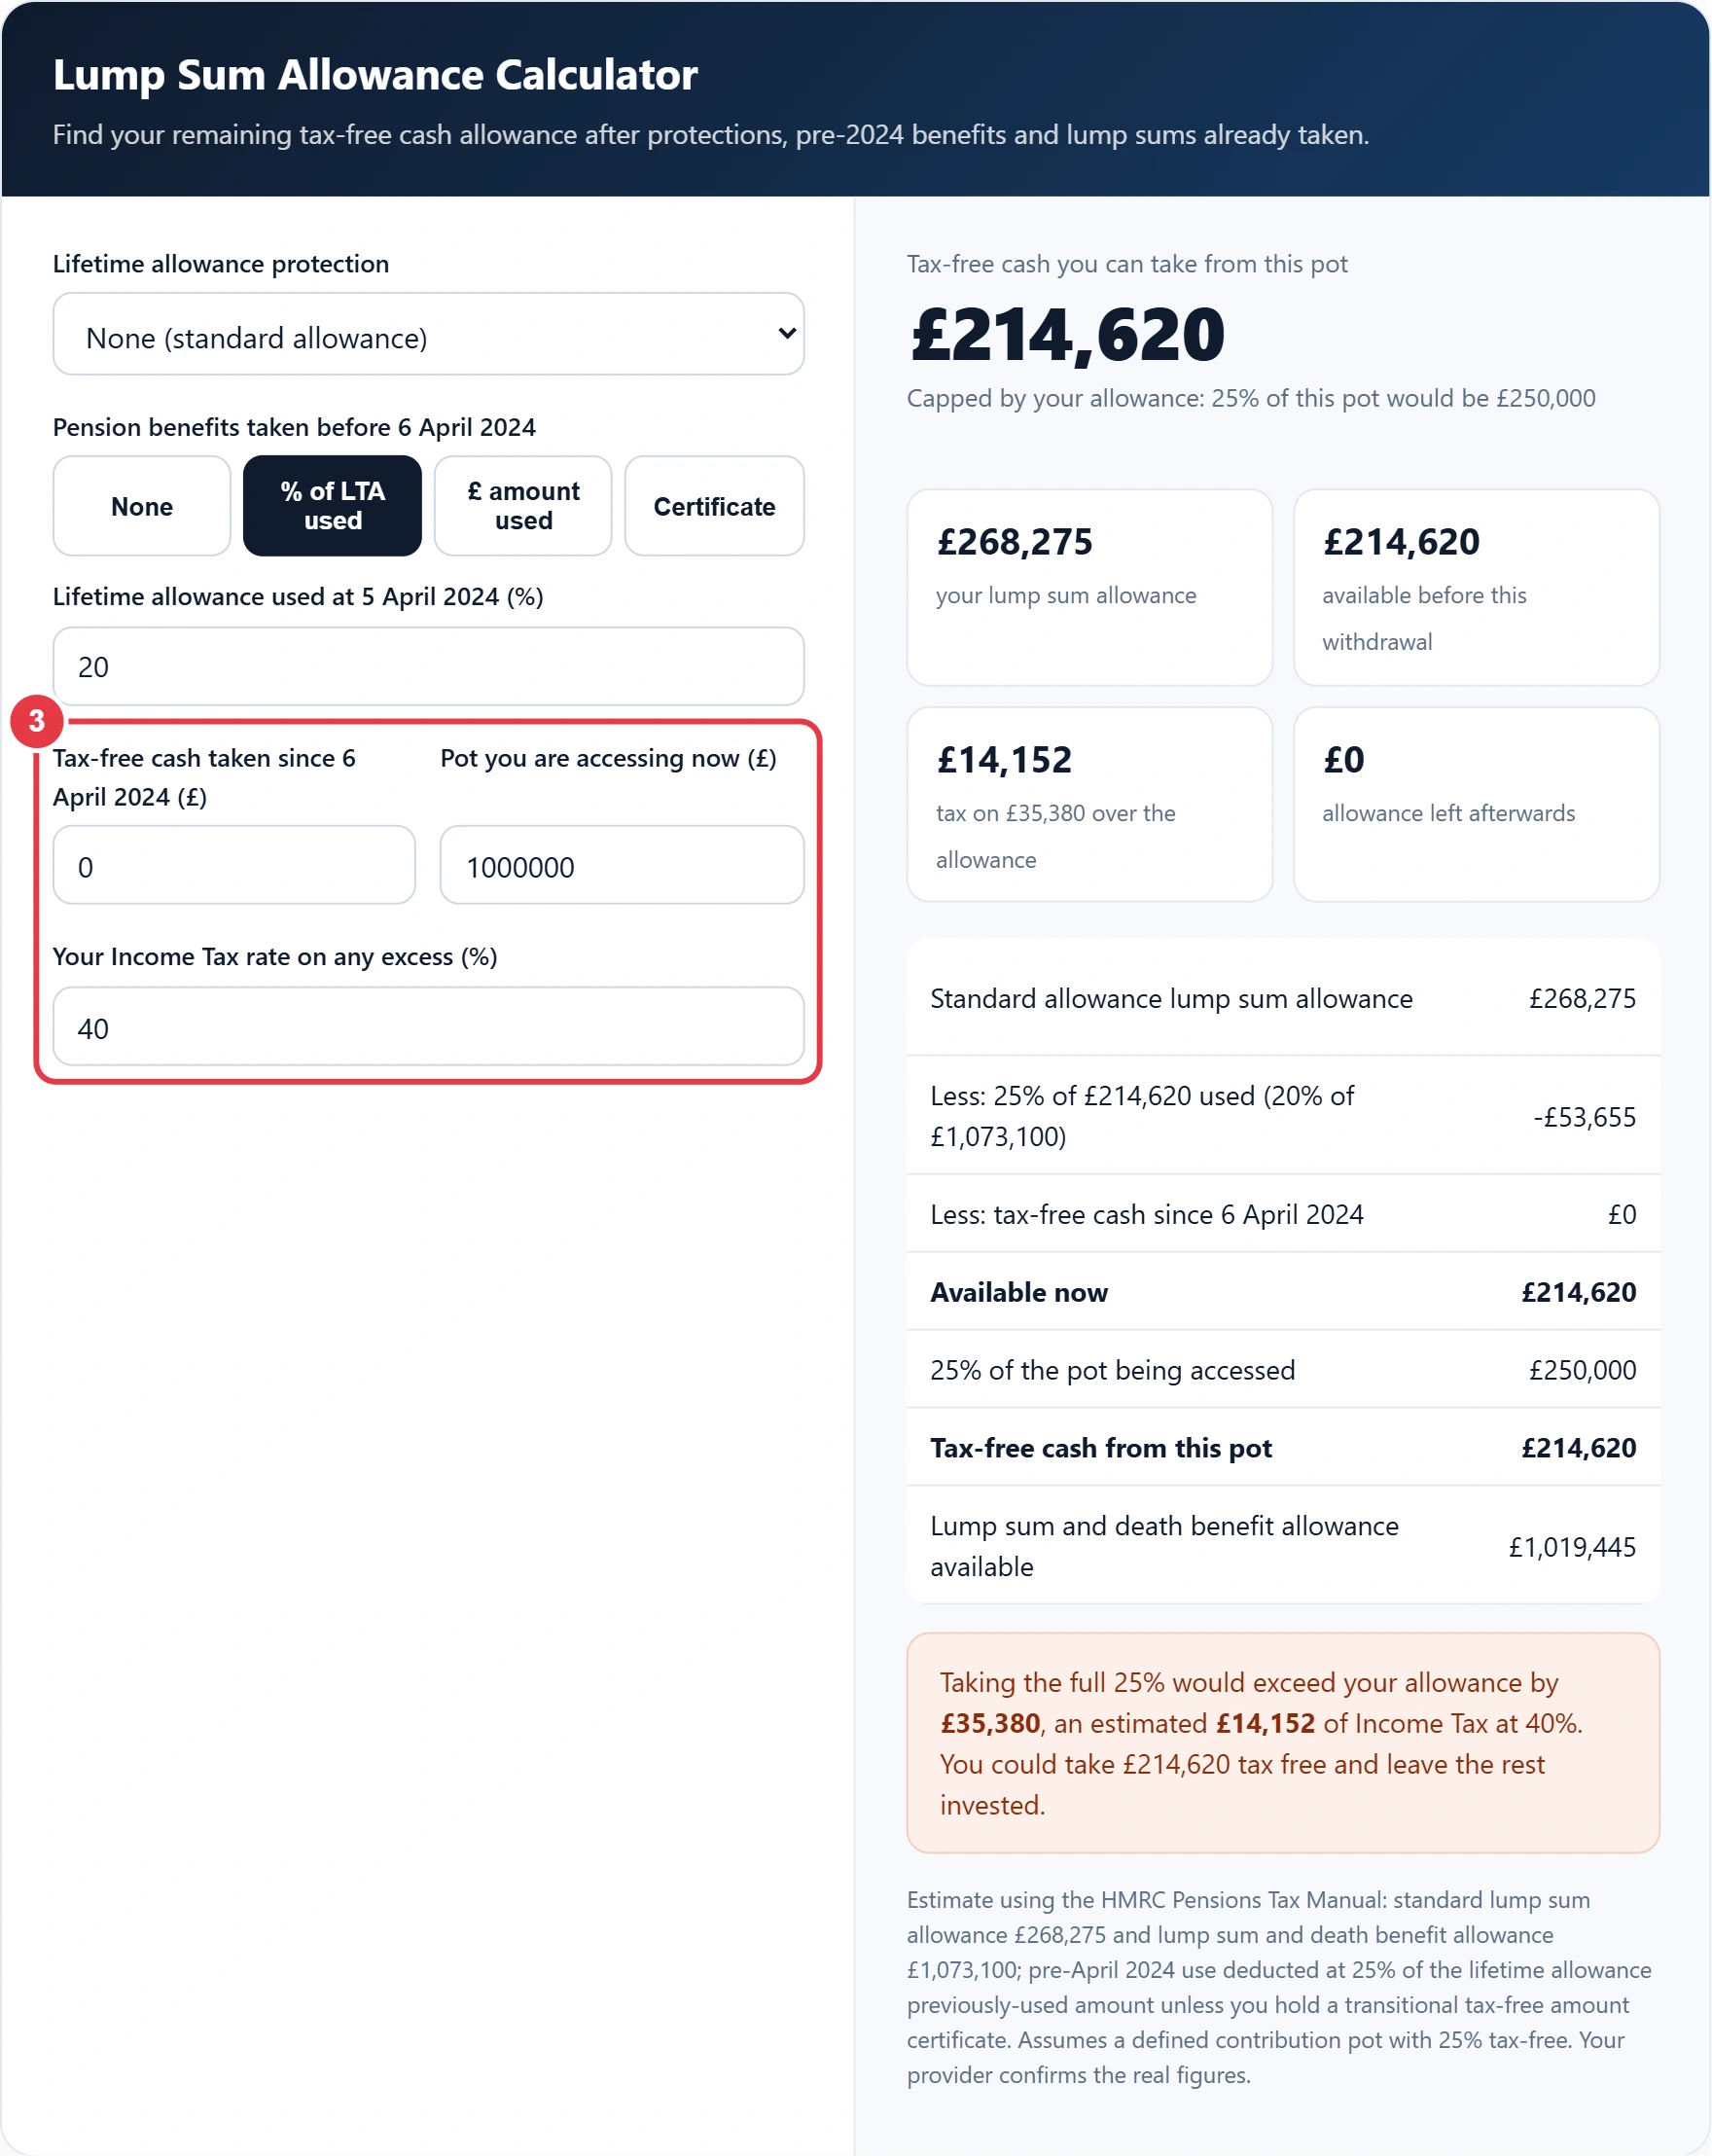
Step 3: Add Recent Lump Sums, the Pot and Your Tax Rate
Enter any tax-free cash taken since 6 April 2024 from any scheme, then the value of the pot you want to access now. Finally enter your marginal Income Tax rate, such as 20%, 40% or 45%, which the tool uses to estimate tax on any part of a 25% lump sum that goes over your allowance.
Step 4: Read Your Tax-Free Cash
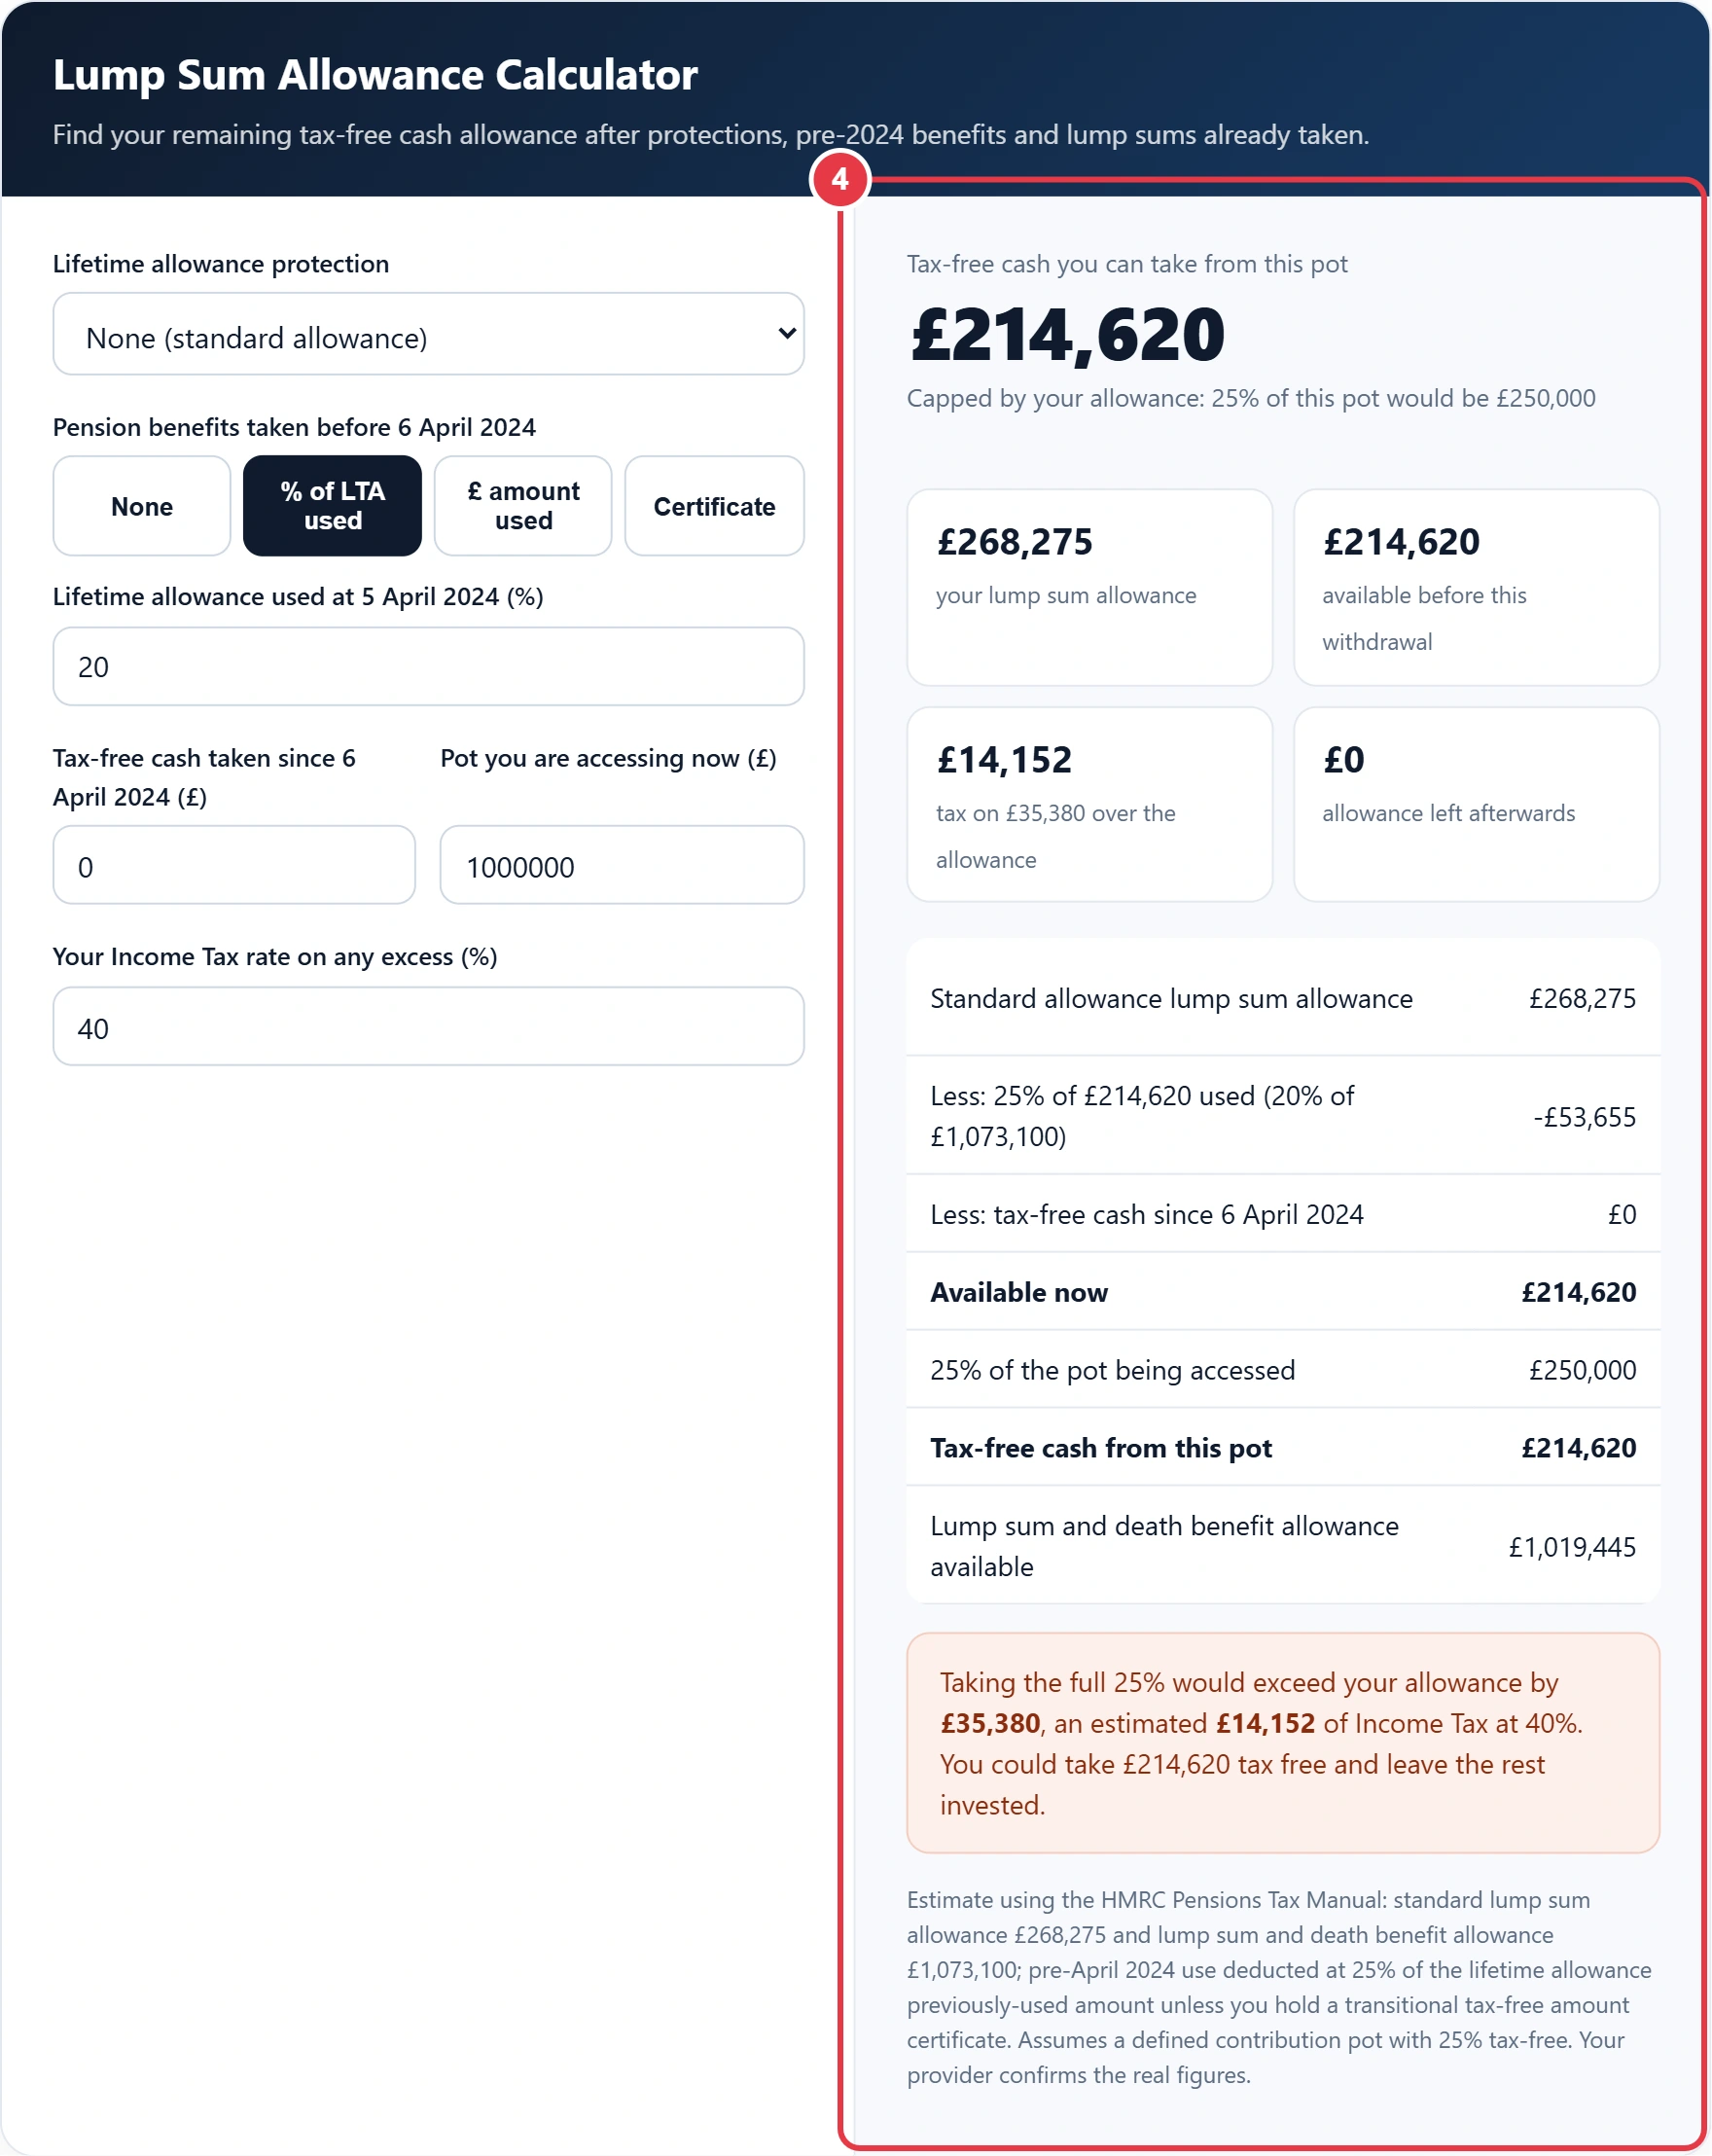
The headline shows the tax-free cash available from this pot. The stats show your allowance, what is available before this withdrawal, the estimated tax on any excess and what remains afterwards. The table sets out each deduction so you can check it against your provider's figures before you sign anything.
How Much Tax-Free Cash Can I Take From My Pension?
You can take the lower of 25% of the pot and your remaining lump sum allowance. Under the standard £268,275 allowance, the cap only bites on pots above £1,073,100, as the table shows for someone with no pre-2024 benefits.
| Pot accessed | 25% of pot | Tax-free cash | Taxable excess |
|---|---|---|---|
| £200,000 | £50,000 | £50,000 | £0 |
| £500,000 | £125,000 | £125,000 | £0 |
| £1,073,100 | £268,275 | £268,275 | £0 |
| £1,200,000 | £300,000 | £268,275 | £31,725 |
| £1,500,000 | £375,000 | £268,275 | £106,725 |
Worked example: Margaret took a final salary pension in 2019 that used 20% of her lifetime allowance. At 5 April 2024 that is 20% of £1,073,100, or £214,620, and 25% of it, £53,655, comes off her allowance, leaving £214,620. She now accesses a £1,000,000 SIPP. A quarter would be £250,000, so £214,620 is tax free and the other £35,380, if taken as a lump sum, is taxed at her 40% rate: about £14,152.
How Do Pensions Taken Before April 2024 Reduce the Allowance?
They reduce it by 25% of your lifetime allowance previously-used amount, unless you hold a certificate. That standard calculation assumes you took a full quarter tax free every time, even from a final salary scheme where you may have taken far less, or none at all.
If you took less, you can ask a scheme for a transitional tax-free amount certificate showing the tax-free cash you actually received, and that figure replaces the 25% deduction. In the HMRC example, Eva's certificate of £10,000 leaves her £258,275. You need complete evidence of those earlier payments, so ask your scheme well before you plan to draw.
What Is the Lump Sum Allowance With Protection?
A protected allowance is higher than £268,275 and follows the protection you registered under the old lifetime allowance rules. The figures below come from the HMRC Pensions Tax Manual and the GOV.UK lump sum allowance guide, which confirms protections carry over to both new allowances.
| Protection | Lump sum allowance | Lump sum and death benefit allowance |
|---|---|---|
| None | £268,275 | £1,073,100 |
| Fixed protection 2012 | £450,000 | £1,800,000 |
| Fixed protection 2014 | £375,000 | £1,500,000 |
| Fixed protection 2016 | £312,500 | £1,250,000 |
| Individual protection 2014 | Lower of £375,000 or 25% of relevant amount | Lower of £1,500,000 or relevant amount |
| Individual protection 2016 | Lower of £312,500 or 25% of relevant amount | Lower of £1,250,000 or relevant amount |
| Primary or enhanced, no lump sum protection | £375,000 | Ask your provider |
What Happens If I Go Over the Lump Sum Allowance?
Any lump sum above your remaining allowance is taxed as income at your marginal rate, and the provider deducts it before paying you. You do not have to take the excess as cash: leaving it invested for drawdown lets you spread that income over several tax years and possibly pay a lower rate.
Large withdrawals can also push your income into the band where the personal allowance tapers away. The 60% tax trap calculator shows that cost in pounds, so you can choose how much to draw in each tax year.
If you are still paying in, taking taxable income flexibly can cut what you can contribute in future. Check the pension tax relief calculator and, if your income is very high, the tapered annual allowance calculator before your first taxable withdrawal goes through.
</>Embed this calculator on your website
Add the free Lump Sum Allowance Calculator to your own site or blog. Copy the code below and paste it into an HTML block. It resizes itself and works on phones.
How we checked this tool: the Tools Veria Editorial Team built this tool by hand, checked it against the official rules or published standards where they apply, and tested it against worked examples. Results are estimates for planning, not personal financial or tax advice. Read our editorial policy and disclaimer, or report an error.
Frequently Asked Questions
What is the lump sum allowance for 2026/27?
The standard lump sum allowance is £268,275 for 2026/27, unchanged since it started on 6 April 2024. It is a lifetime limit on tax-free pension lump sums across all your schemes, higher if you hold a lifetime allowance protection.
How is the lump sum allowance worked out if I took a pension before 2024?
Your allowance is reduced by 25% of the lifetime allowance you had used by 5 April 2024. Someone who used 40%, or £429,240, loses £107,310 and has £160,965 left, unless a transitional certificate shows they took less.
What is a transitional tax-free amount certificate?
It is a certificate from your pension scheme showing the tax-free cash you actually took before 6 April 2024. Its figure replaces the standard 25% deduction, which helps people who took little or no tax-free cash from earlier pensions.
What is the lump sum allowance with fixed protection 2016?
With fixed protection 2016 your lump sum allowance is £312,500 and your lump sum and death benefit allowance is £1,250,000. Fixed protection 2014 gives £375,000 and £1,500,000, and fixed protection 2012 gives £450,000 and £1,800,000.
Is tax-free cash still 25% of my pension?
Yes. You can usually take up to 25% of each pension tax free, but the total across all schemes cannot exceed your lump sum allowance. On a pot above £1,073,100 the standard £268,275 limit, not 25%, sets the tax-free amount.
What is the lump sum and death benefit allowance?
It is a wider limit of £1,073,100 that covers tax-free retirement lump sums plus serious ill health lump sums and certain lump sum death benefits. Any lump sum that counts towards the lump sum allowance also counts towards this one.