Build threshold income and adjusted income the HMRC way and see your 2026/27 pension allowance.
Estimate only, using the 2026/27 limits on GOV.UK: £60,000 allowance, £200,000 threshold income, £260,000 adjusted income and a £10,000 floor. Lump sum death benefits, overseas schemes and the money purchase annual allowance are not modelled. Check your figures with HMRC or a regulated adviser.
This tapered annual allowance calculator is for UK high earners and their advisers who need to know their pension annual allowance for the 2026/27 tax year. It builds threshold income and adjusted income using the GOV.UK tapered allowance method, applies the taper and shows any excess, so you can check before you or your employer pay more in. Figures checked October 2026.
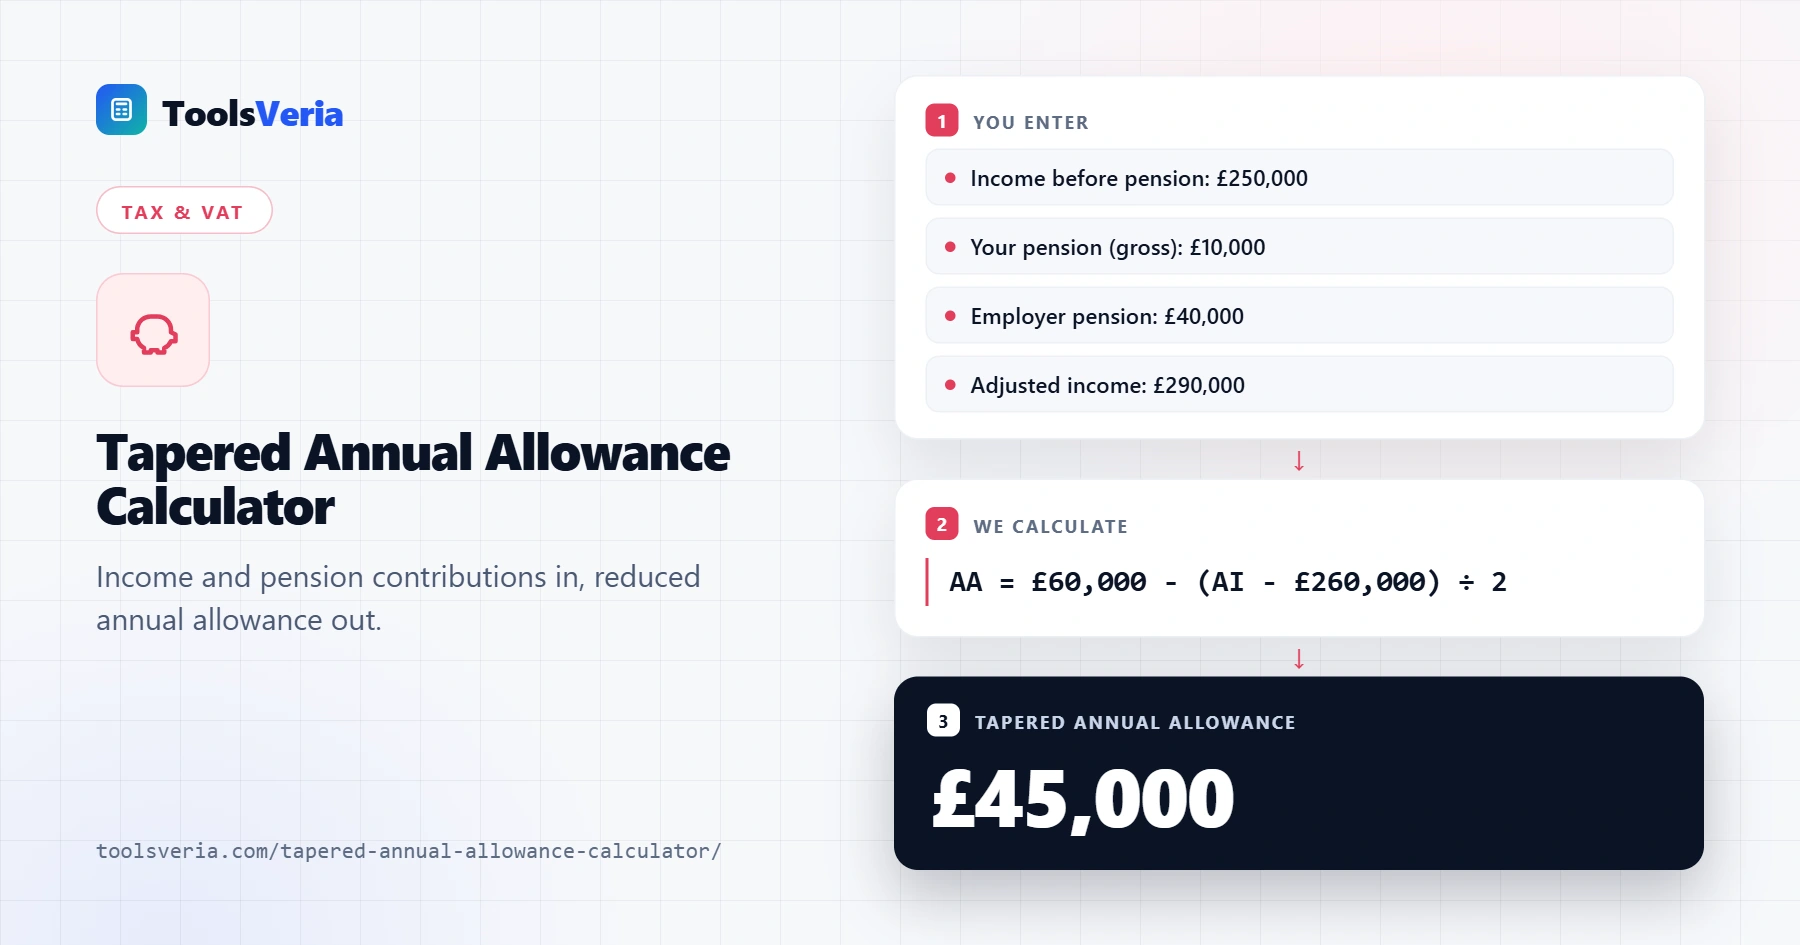
Quick answer: Your £60,000 allowance is tapered only if threshold income is over £200,000 and adjusted income is over £260,000. It then falls by £1 for every £2 of adjusted income above £260,000, to a £10,000 floor. A tapered annual allowance calculator turns adjusted income of £290,000 into a £45,000 allowance.
In This Guide
What Is the Tapered Annual Allowance?
The tapered annual allowance is a reduced limit on tax relieved pension saving for people with very high incomes. Everyone else can pay in up to the standard annual allowance of £60,000 a year across all their pensions, counting both their own and their employer's contributions, before a tax charge applies.
The formula in plain words: take adjusted income, subtract £260,000, halve the result and round it down to the nearest pound. Take that reduction off £60,000. If the answer is below £10,000, your allowance is £10,000. The taper switches on only when both income tests are failed, so someone with adjusted income of £300,000 but threshold income of £195,000 keeps the full £60,000.
How to Use the Tapered Annual Allowance Calculator
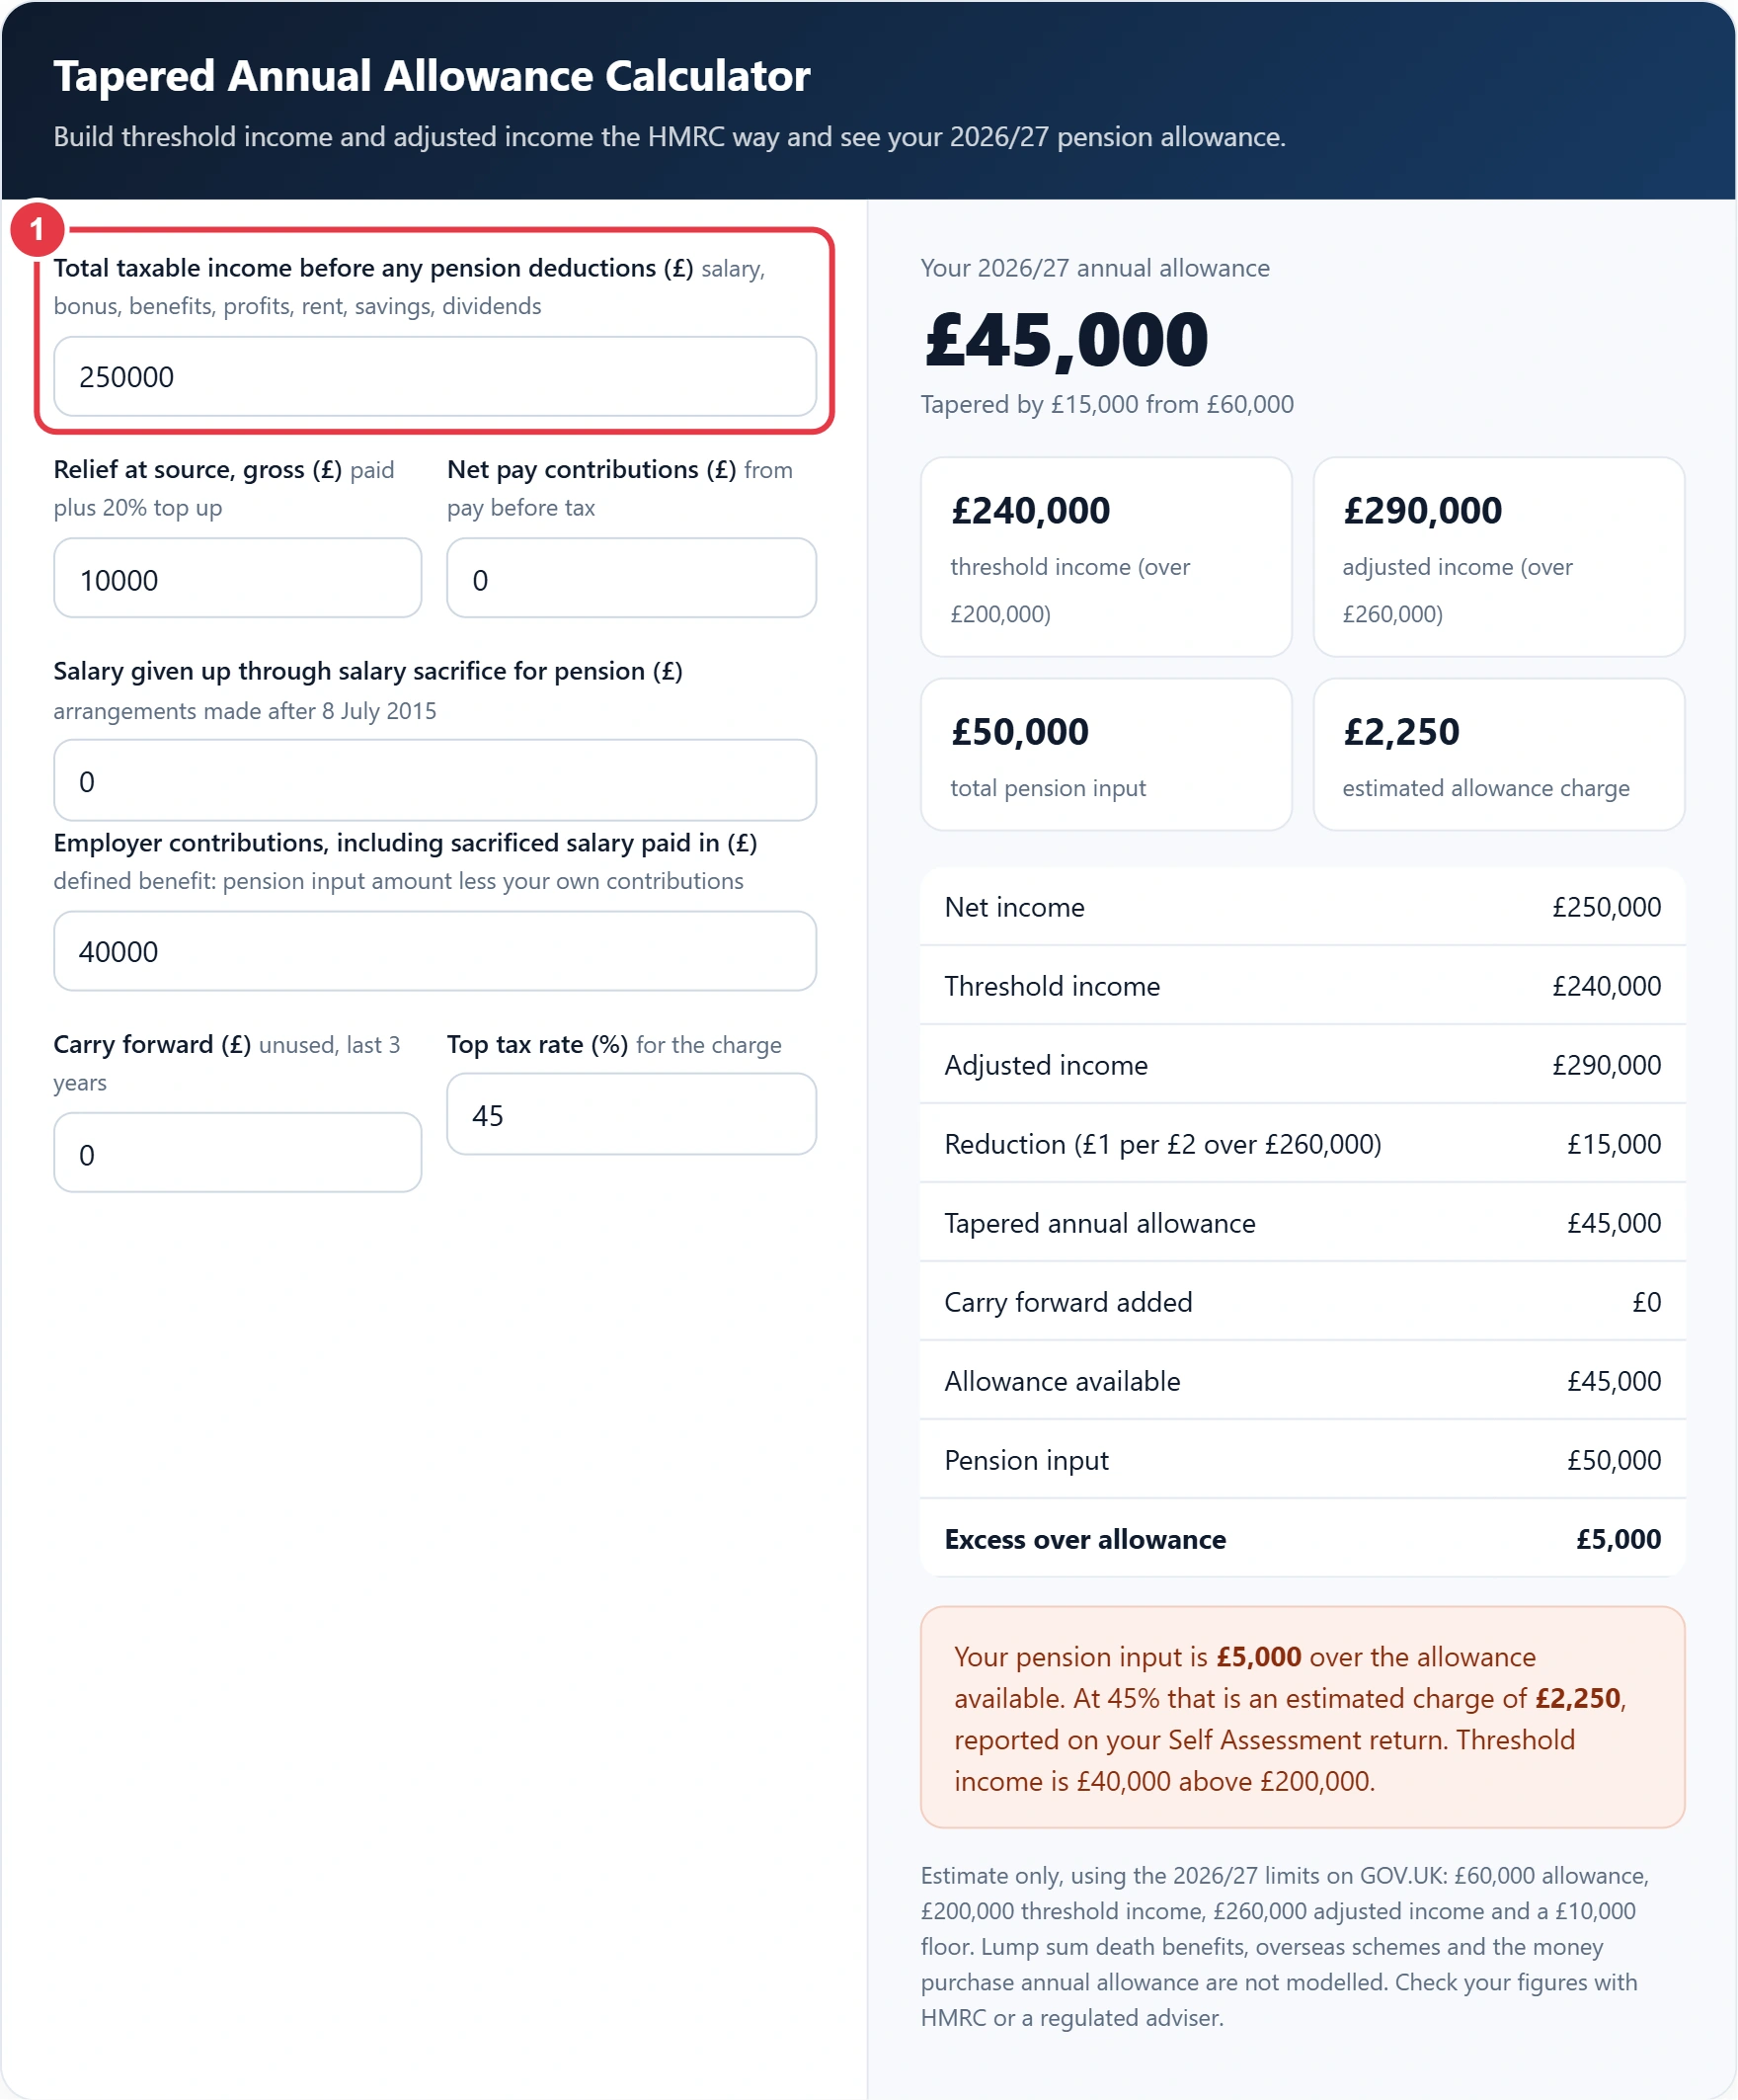
Step 1: Enter Your Total Income
Enter all taxable income for 6 April 2026 to 5 April 2027 before any pension deduction or salary sacrifice: salary, bonus, taxable benefits, self employed profit, rental profit, interest and dividends. Use expected figures if the year has not ended, and include bonuses that are likely rather than certain if you want a cautious result.
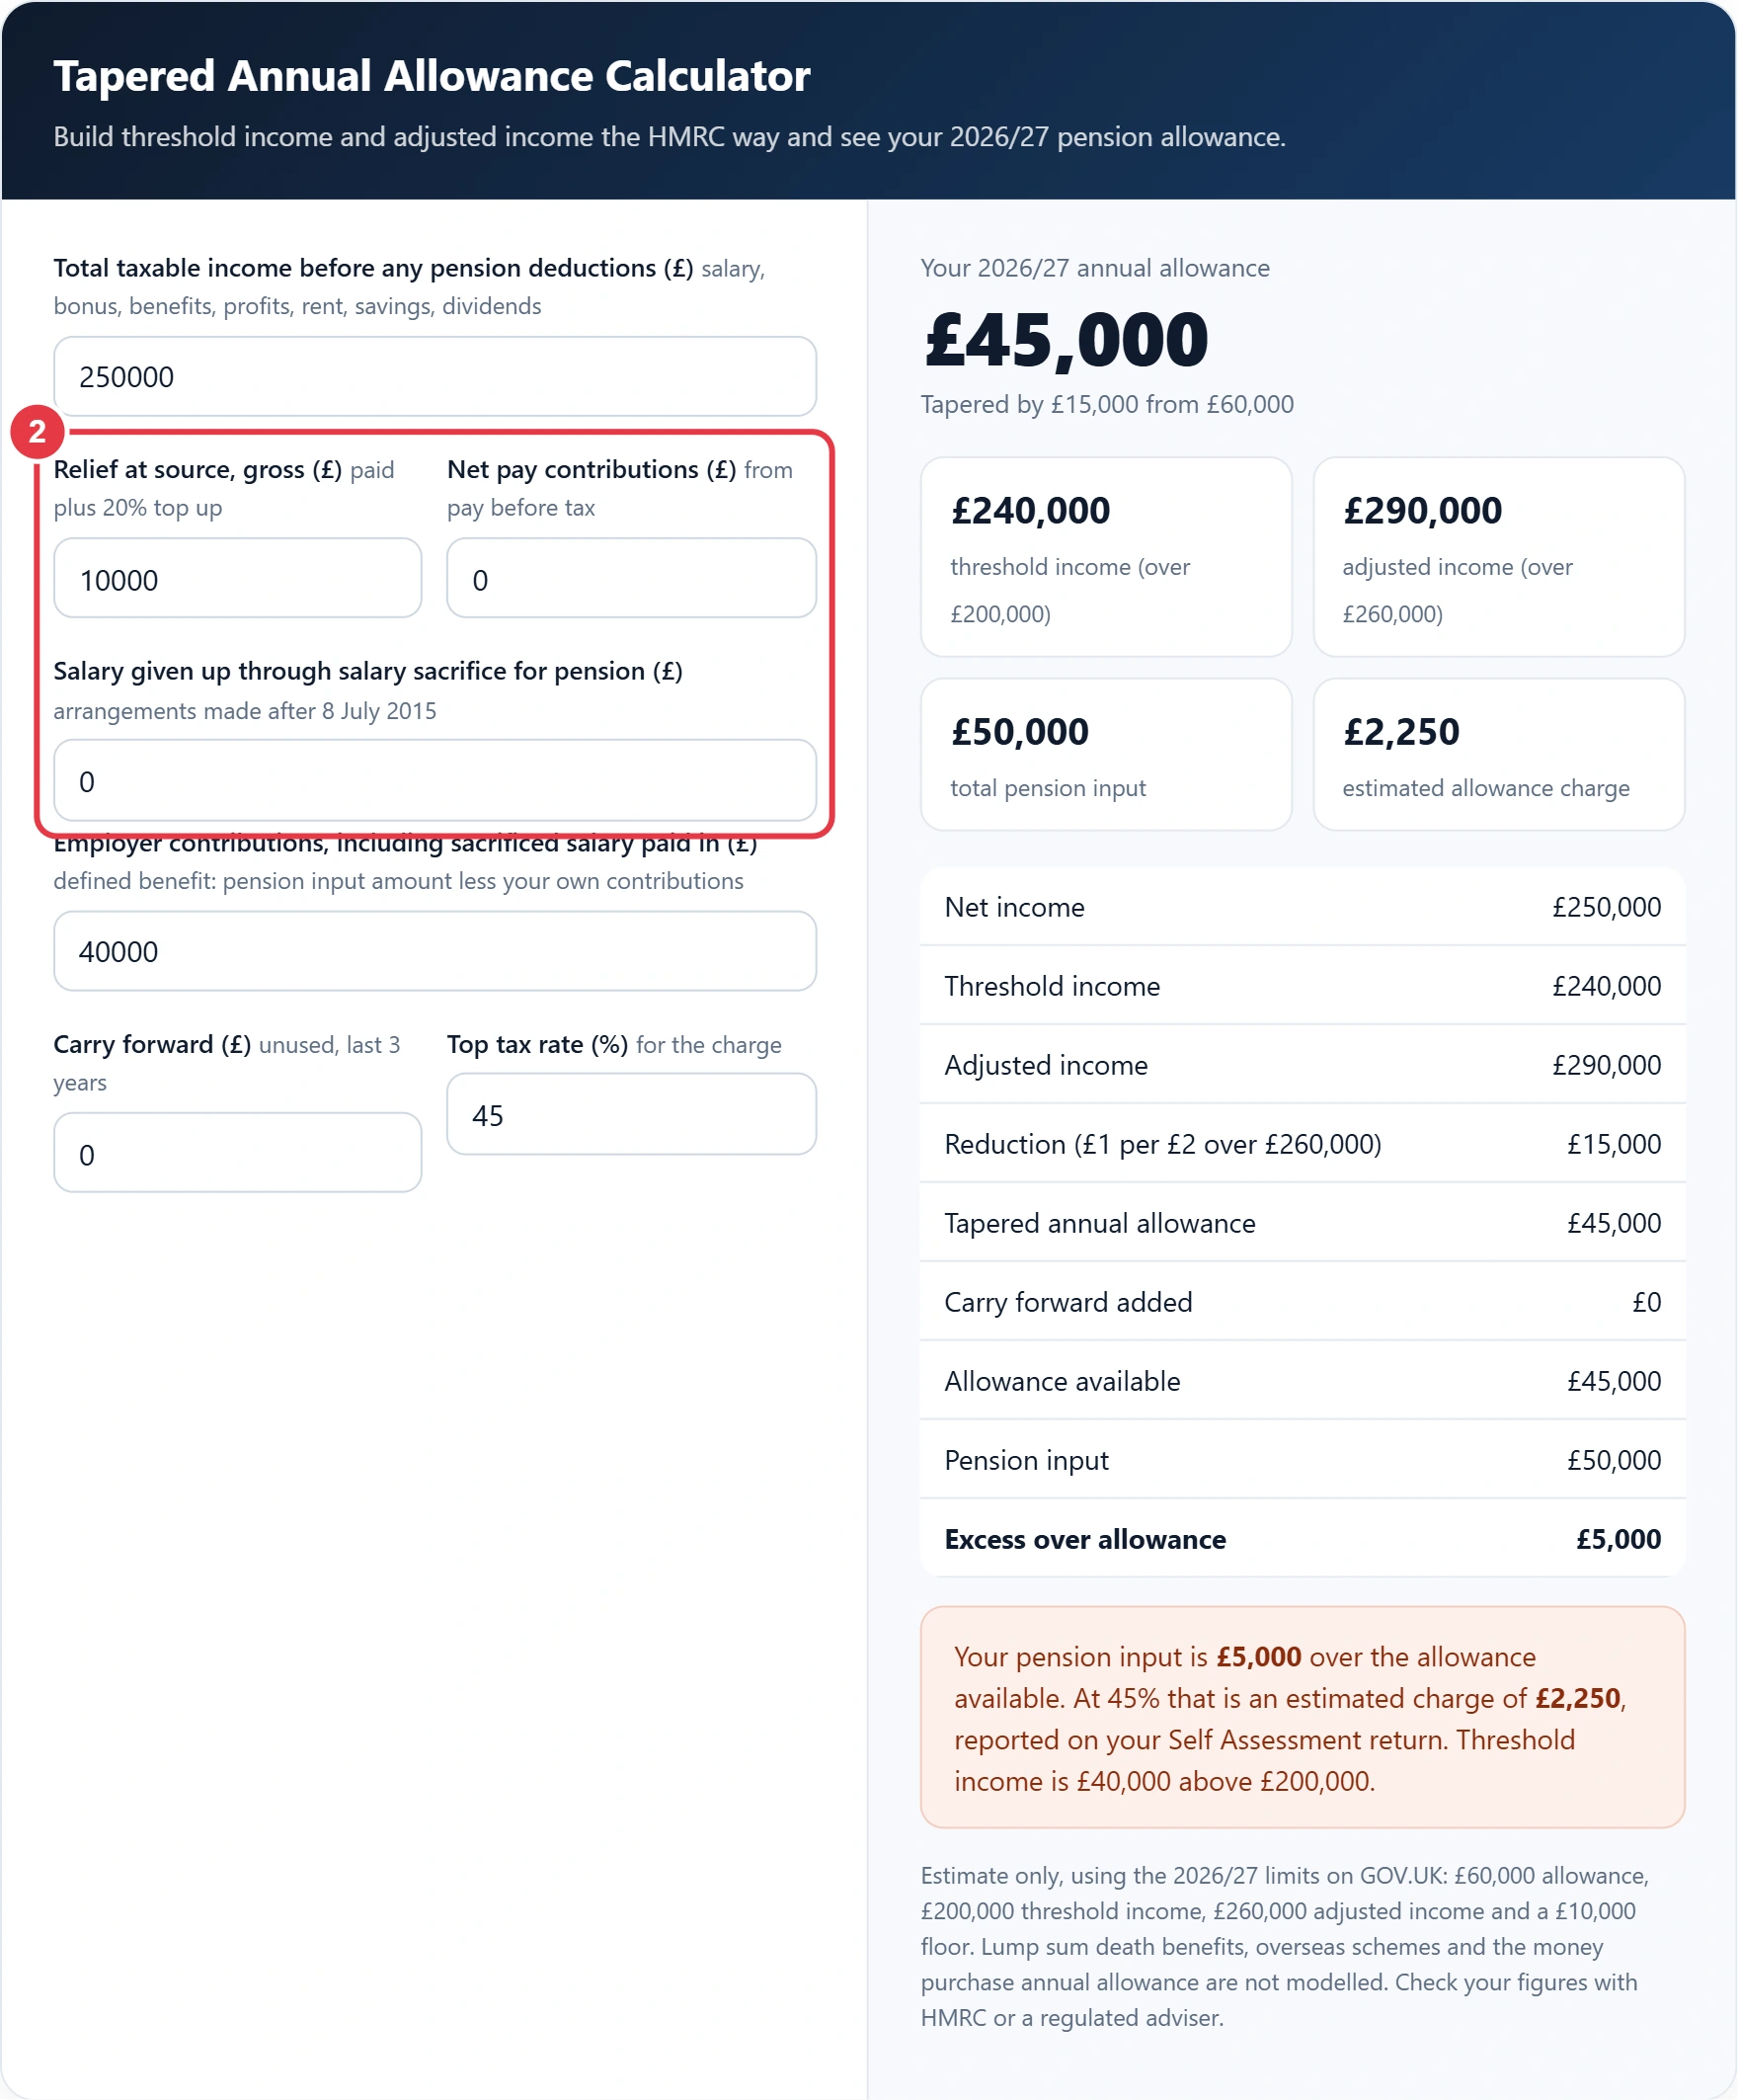
Step 2: Add Your Own Contributions
Split your contributions by how relief is given. Relief at source payments, such as a SIPP, go in gross: £8,000 paid becomes £10,000. Net pay contributions come from salary before tax. Salary sacrifice is the pay you gave up, because sacrifice set up after 8 July 2015 is added back to threshold income. The dividend tax calculator helps if part of your income is company dividends and you need a firm total.
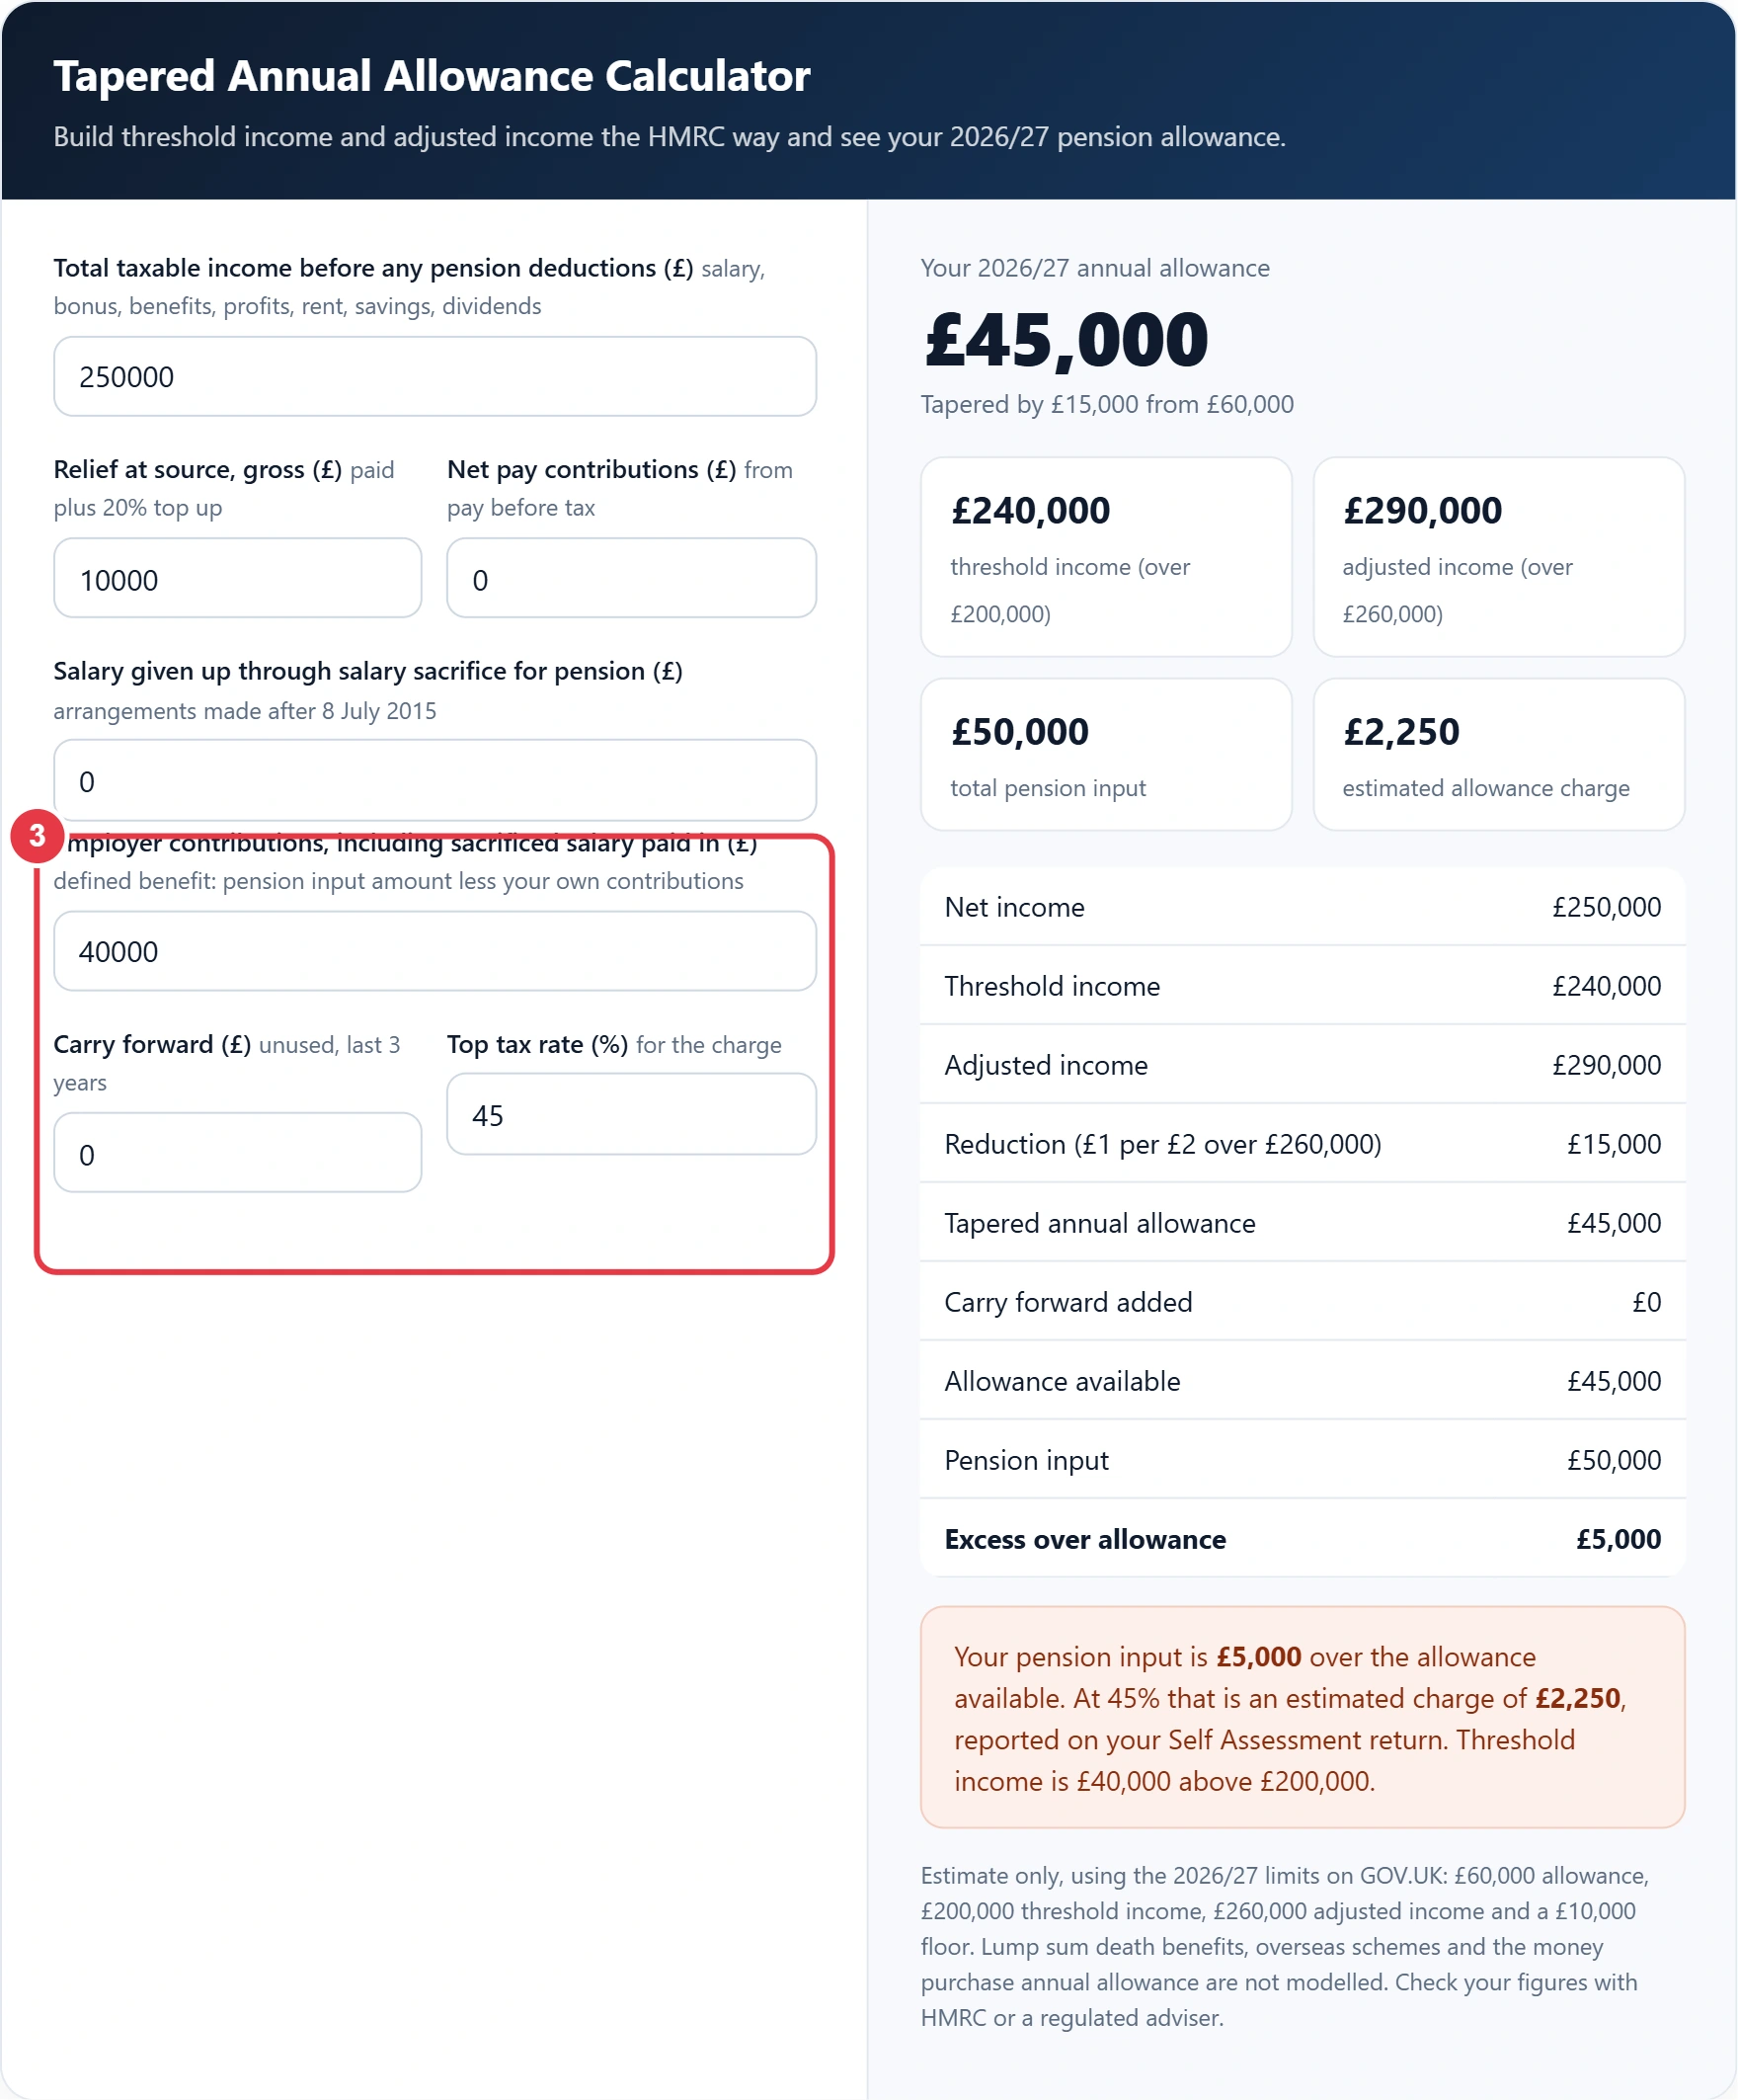
Step 3: Add Employer Contributions and Carry Forward
Enter everything your employer pays in, including salary you sacrificed. In a defined benefit scheme, use the pension input amount from your pension savings statement minus your own contributions. Add any unused allowance from the previous three tax years and your top rate of tax, which the tool uses to estimate the charge.
Step 4: Read Your Allowance
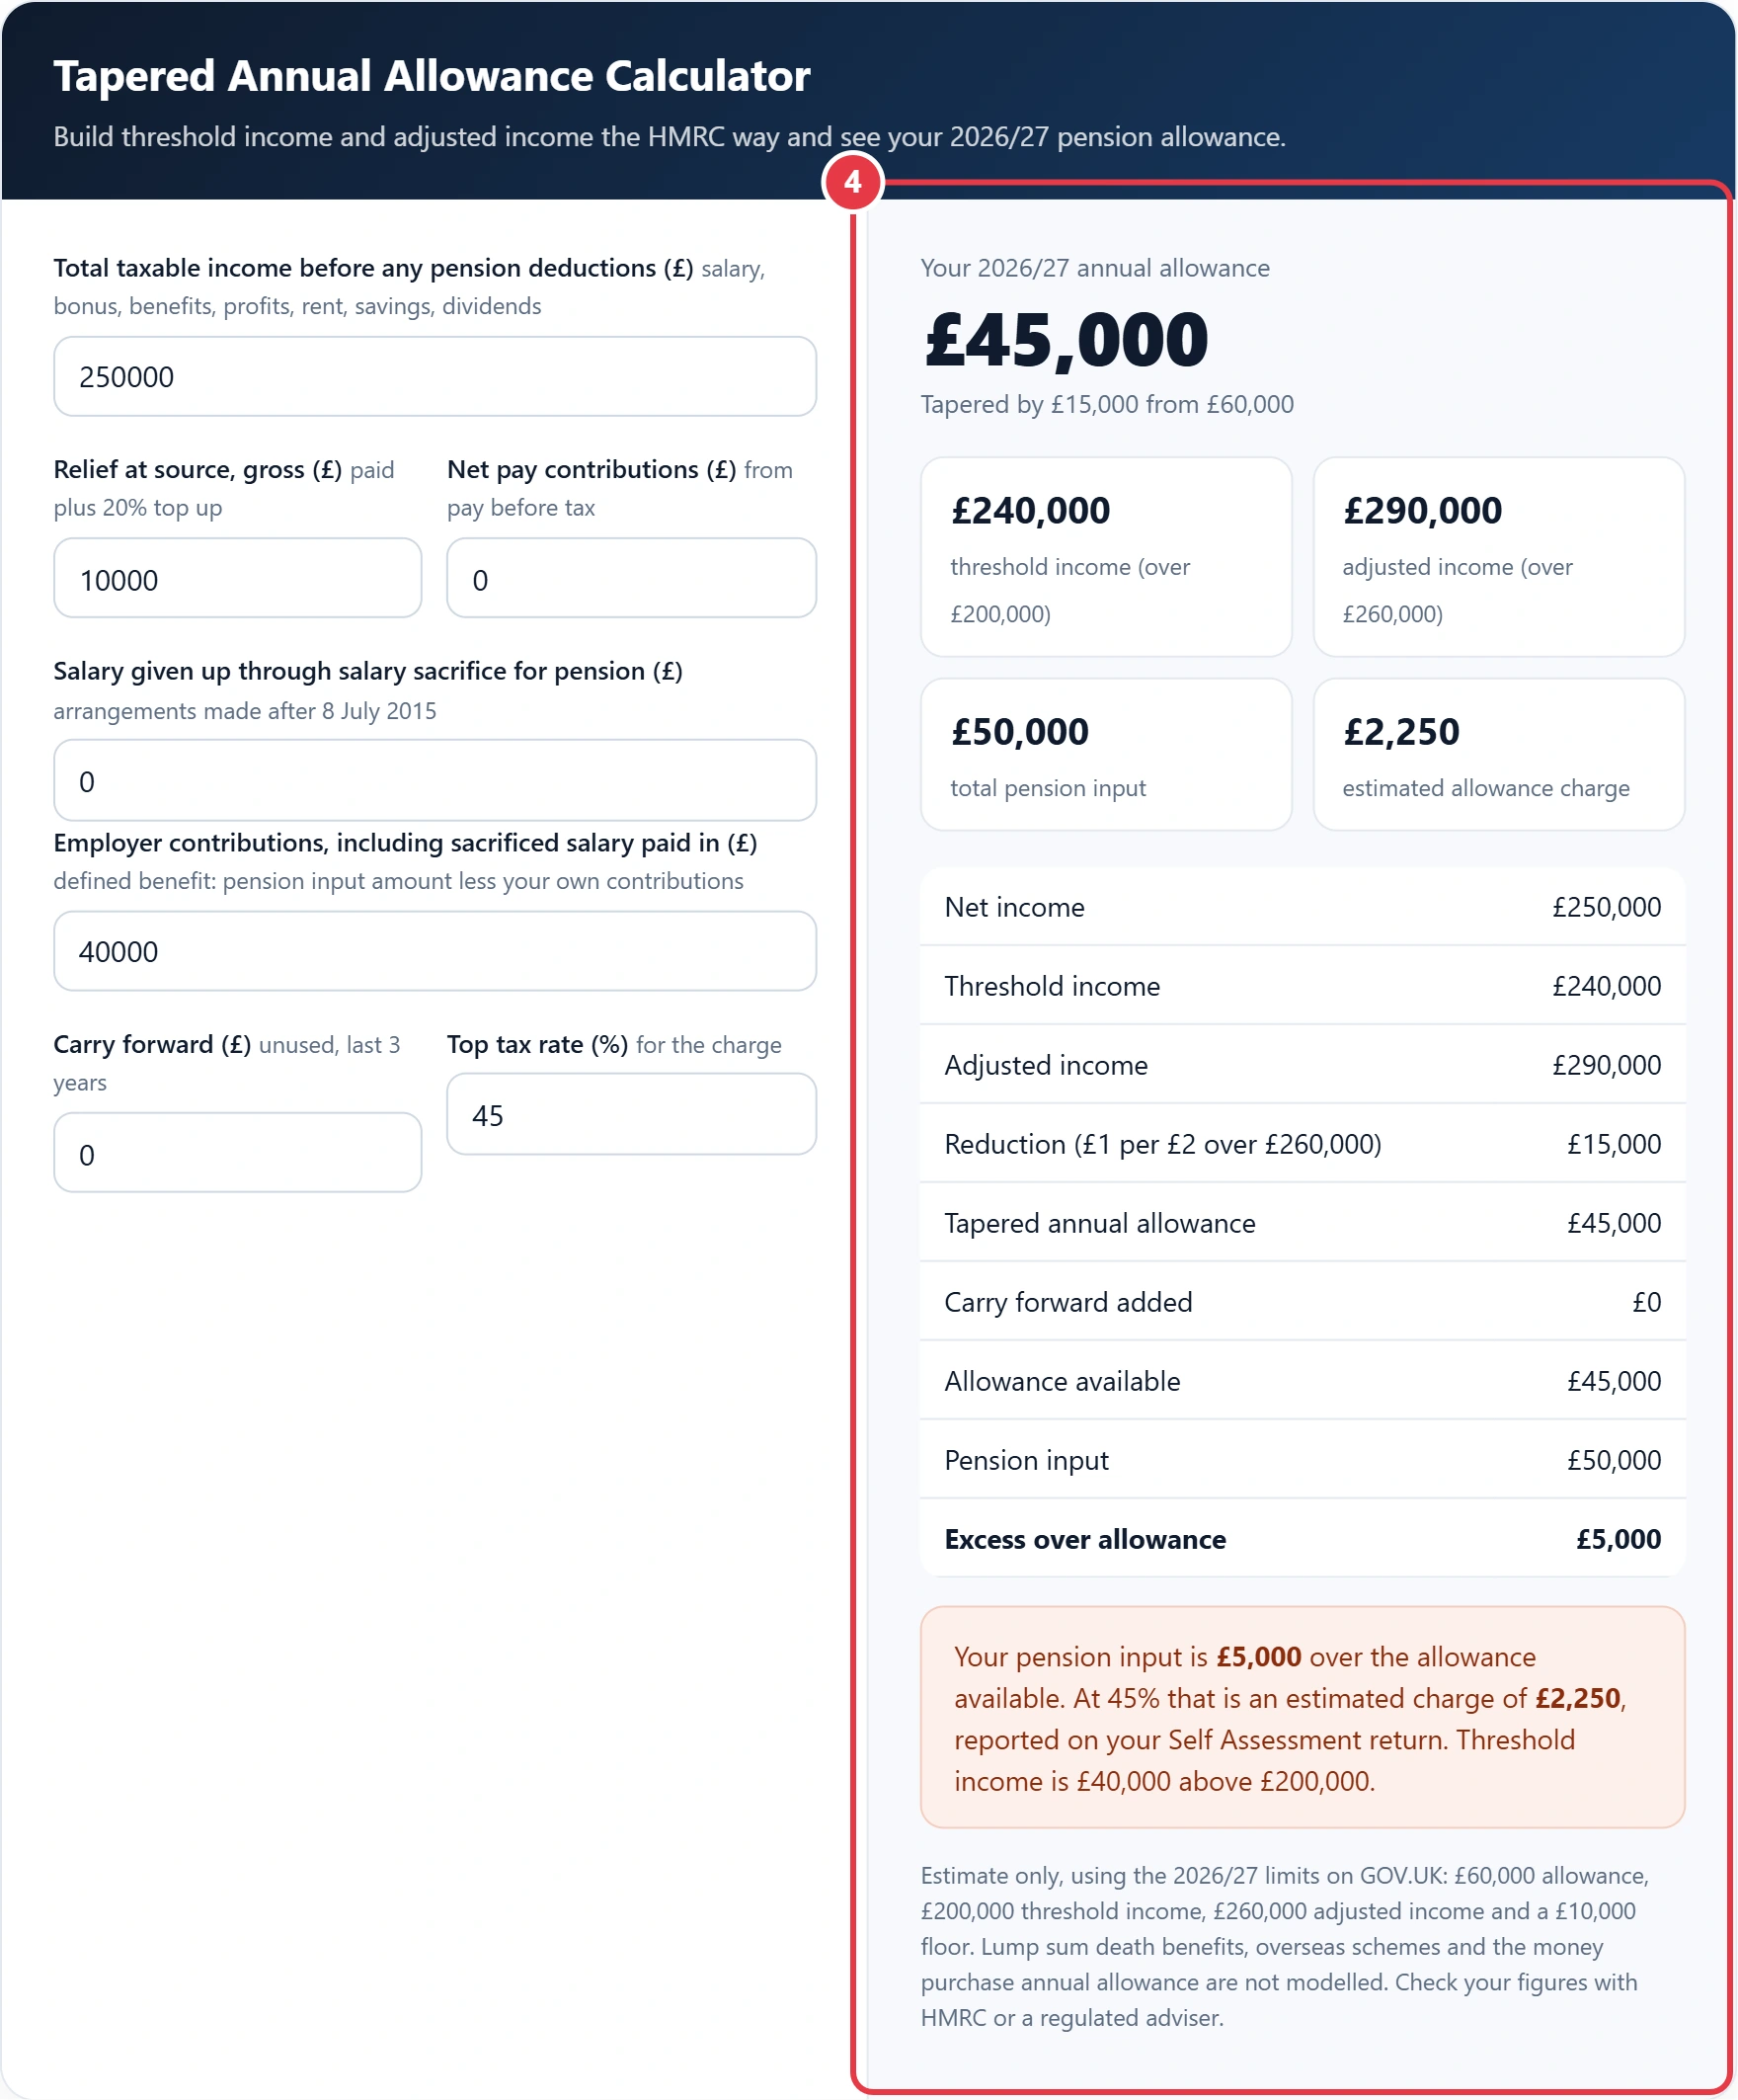
The headline shows your 2026/27 allowance and how much was tapered. The stats show both income tests with a pass or fail note, your total pension input and the estimated charge, and the table sets out each step so you can check it against your payslips, P60 and pension statements.
How Do You Work Out Threshold Income and Adjusted Income?
Both start from net income, which is your taxable income after net pay pension contributions and other reliefs, but they treat pensions differently. Threshold income removes the gross value of relief at source contributions and adds back post 2015 salary sacrifice. Adjusted income adds back net pay contributions and adds every employer contribution.
| Item | Threshold income | Adjusted income |
|---|---|---|
| Starting point | Net income | Net income |
| Relief at source contributions (gross) | Deducted | Not deducted |
| Net pay contributions | Stay deducted | Added back |
| Salary sacrifice after 8 July 2015 | Added back | Counted through employer contributions |
| Employer contributions | Ignored | Added |
| Limit for the taper | Over £200,000 | Over £260,000 |
That is why a large employer contribution can push adjusted income over £260,000 while threshold income stays lower. The rounding rule and both limits are set out in section 228ZA of the Finance Act 2004, which says the reduction is rounded down to the nearest pound.
How Much Is My Tapered Annual Allowance?
Your tapered allowance is £60,000 minus half of your adjusted income above £260,000, with £10,000 as the lowest possible figure. The table shows the allowance at common adjusted income levels when threshold income is over £200,000.
| Adjusted income | Reduction | Annual allowance 2026/27 |
|---|---|---|
| £260,000 or less | £0 | £60,000 |
| £280,000 | £10,000 | £50,000 |
| £290,000 | £15,000 | £45,000 |
| £300,000 | £20,000 | £40,000 |
| £320,000 | £30,000 | £30,000 |
| £340,000 | £40,000 | £20,000 |
| £360,000 or more | £50,000 or more | £10,000 (floor) |
Worked example: Daniel is a salaried partner at a Leeds law firm with £250,000 of taxable income in 2026/27. He pays £8,000 into a SIPP, which is £10,000 gross, and his firm pays £40,000. His threshold income is £240,000 and his adjusted income is £290,000, so both tests are failed. The reduction is £15,000, his tapered annual allowance is £45,000 and his pension input is £50,000. Without carry forward he is £5,000 over, an estimated charge of £2,250 at 45%.
A second example shows why the tests matter. Aisha earns £215,000 and sacrifices £20,000 of salary into her workplace scheme, with a further £15,000 from her employer. Her threshold income is £215,000, because post 2015 sacrifice is added back, but her adjusted income is £230,000, under £260,000, so she keeps the full £60,000.
What Happens If I Go Over My Tapered Annual Allowance?
You pay an annual allowance charge on the excess at your own marginal rate of income tax, after using any carry forward. To see how a smaller pension pot changes long term growth, the compound interest calculator projects any lump sum forward at a rate you choose. GOV.UK confirms the charge is reported in the pension savings tax charges section of a Self Assessment return, and either you or your pension scheme can pay it. Carry forward lets you use unused allowance from the previous three tax years, but each of those years uses its own allowance, which may also have been tapered.
One separate limit can also apply. If you have flexibly accessed a defined contribution pension, the money purchase annual allowance of £10,000 limits future money purchase saving, as HMRC's pensions tax manual states. This tapered annual allowance calculator does not model that interaction, so take advice if both rules could apply to you.
</>Embed this calculator on your website
Add the free Tapered Annual Allowance Calculator to your own site or blog. Copy the code below and paste it into an HTML block. It resizes itself and works on phones.
How we checked this tool: the Tools Veria Editorial Team built this tool by hand, checked it against the official rules or published standards where they apply, and tested it against worked examples. Results are estimates for planning, not personal financial or tax advice. Read our editorial policy and disclaimer, or report an error.
Frequently Asked Questions
What is the tapered annual allowance for 2026/27?
It is a reduced pension annual allowance for people whose threshold income is over £200,000 and adjusted income is over £260,000. The £60,000 allowance falls by £1 for every £2 above £260,000, down to a minimum of £10,000.
At what income does the tapered annual allowance reach £10,000?
The allowance reaches the £10,000 minimum when adjusted income is £360,000 or more, because £100,000 of excess income halved is a £50,000 reduction. Anyone with higher adjusted income still keeps £10,000, provided threshold income is over £200,000.
Are employer pension contributions included in threshold income?
No. Employer contributions are left out of threshold income but added in full to adjusted income. The exception is salary sacrifice set up after 8 July 2015, which is added back to threshold income as if you had been paid it.
Can I carry forward unused allowance if my allowance is tapered?
Yes. You can add unused allowance from the previous three tax years once you have used the current year's allowance. Each earlier year's unused amount is based on that year's own allowance, which may itself have been tapered, so check each year's pension savings statement.
How is the annual allowance charge taxed?
The excess over your allowance and carry forward is added to your income and taxed at your marginal rate. A £5,000 excess at the 45% additional rate gives a charge of £2,250, reported on your Self Assessment return or paid by your pension scheme.
Does the taper apply if only my adjusted income is over £260,000?
No. Both tests must be failed. If your threshold income is £200,000 or less, you keep the full £60,000 annual allowance even when adjusted income is well above £260,000 because of large employer contributions.